

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Gramlin is stocked at 241 licensed dispensaries across California and Oklahoma, 240 of them in California, with the deepest coverage in Los Angeles, Sacramento, San Francisco, San Jose, and San Diego. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
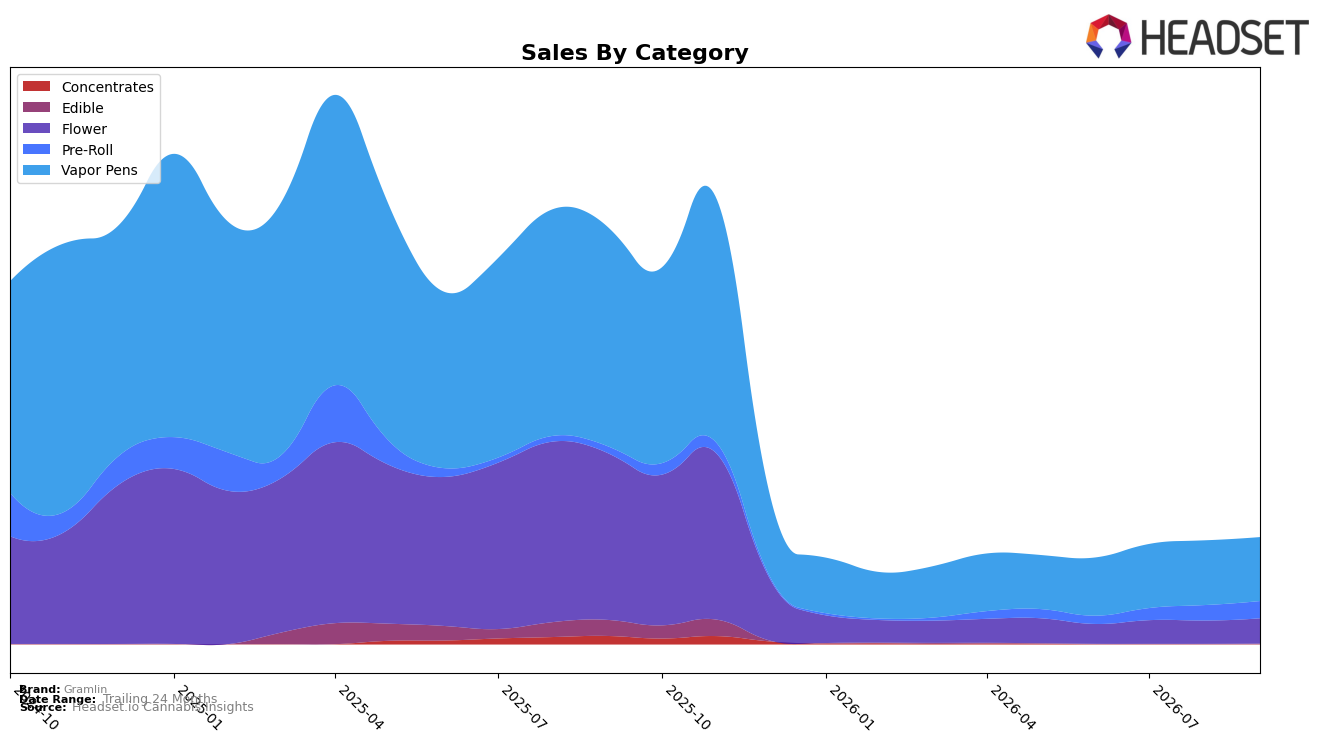
Vapor Pens held 60.06% share in September 2026 with a year-over-year decline of 70.89% and a month-over-month dip of 1.20%, while Flower accounted for 23.65% share with a 84.92% year-over-year drop but an 8.63% month-over-month gain. Pre-Roll rose to 15.99% share on 156.89% year-over-year growth and an 11.80% month-over-month increase, as Edible sat at 0.29% share with a 98.03% year-over-year decline despite a 265.51% month-over-month spike; Concentrates nearly exited the mix at 0.01% share with a 99.90% year-over-year fall. With total brand sales down 74.49% year over year and average price down 7.09%, the pattern indicates a pivot where Pre-Roll expansion is partially offsetting deep Vapor Pens and Flower contraction, concentrating Gramlin’s volume in fewer, faster-moving formats.
The mix shift toward Pre-Roll alongside a smaller, stabilizing Vapor Pens base (down 1.20% month over month) and a recovering Flower line (up 8.63% month over month) implies a repositioning from a single-category identity to a multi-format value play, reinforced by a 7.09% average price reduction. Holding rank 25 in Vapor Pens in California while Pre-Roll gains share to 15.99% suggests future emphasis on stackable, lower-price-per-unit occasions, with Pre-Roll as the acquisition engine and Vapor Pens as the retention anchor; the thesis is that Gramlin’s near-term path to stabilizing the 74.49% year-over-year sales decline runs through leaner price points and mix-led volume from Pre-Roll rather than premium-priced Flower.
Competitive Landscape
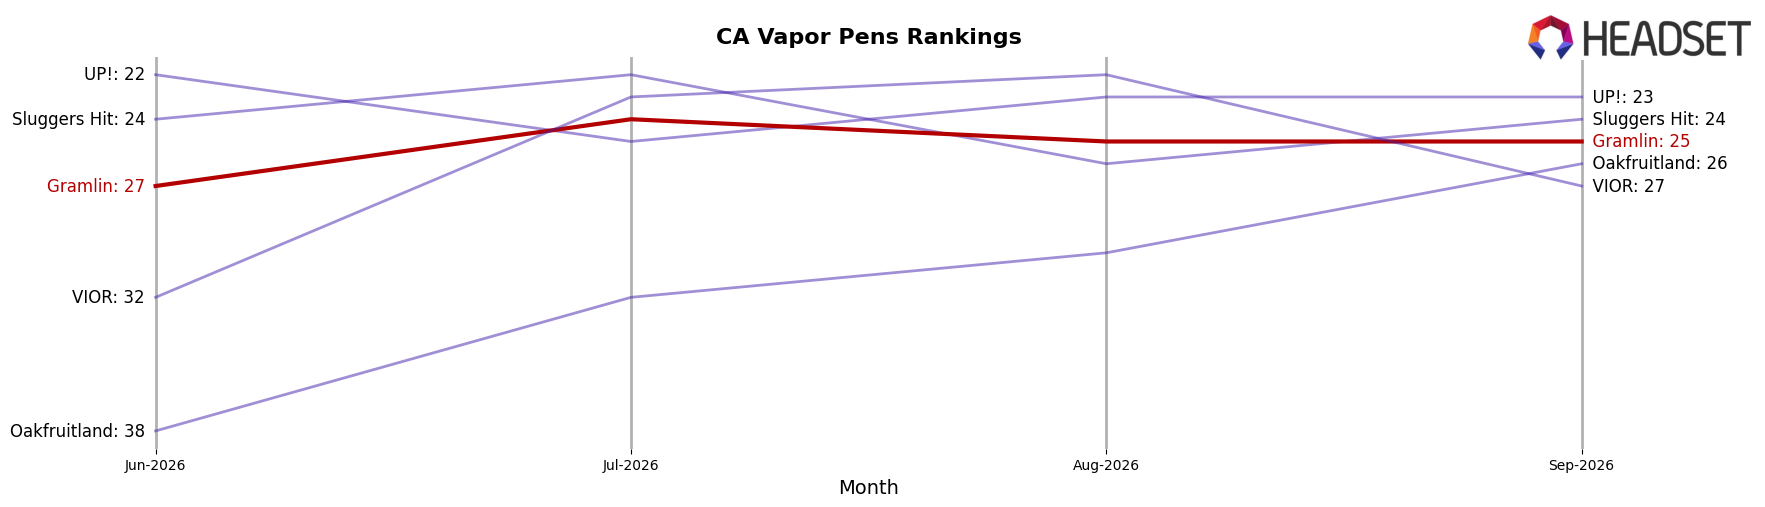
Gramlin sits at rank #25 in CA Vapor Pens in September 2026, improving 7 places year over year while edging up 2 positions from #27 in June 2026, and its historical peak was #4 in April 2025. Competitors are shifting unevenly: STIIIZY held #1 with a -16.7% year-over-year sales change, whereas Jetty Extracts climbed from #4 to #3 with a 45.2% year-over-year increase, and Plug Play slipped from #3 to #4 alongside a -13.5% year-over-year decline. The juxtaposition of Gramlin’s +7 rank gain against leaders with negative or mixed sales trends and an upward mover at the top suggests the brand is stabilizing into the mid-pack rather than re-accelerating toward its April 2025 peak, implying a consolidation phase unless momentum extends beyond incremental rank lifts.
Notable Products
Blue Dream Distillate Disposable (1g) posted the steepest shift in September 2026 with a -14.0% MoM drop while holding rank 3, contrasted by Raspberry OG Distillate Disposable (1g) soaring +132.6% MoM at rank 1. Strawberry Cough Distillate Disposable (1g) rose +17.1% MoM at rank 5 as Sour Apple Pie Distillate Disposable (1g) fell -21.7% at rank 9, and Pineapple Express Distillate Disposable (1g) slid -37.2% at rank 2. With nine of the top ten in Vapor Pens and only one Edible entry at rank 10, the mix points to an intensified tilt toward disposables where momentum is consolidating at the very top SKU despite volatility in mid-tier flavors, suggesting Gramlin’s commercial direction favors a narrower, higher-velocity pen portfolio.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

