

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
In The Flow is stocked at 45 licensed dispensaries across Colorado and West Virginia, 28 of them in Colorado, with the deepest coverage in Boulder, Denver, Aurora, Longmont, and Naturita. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
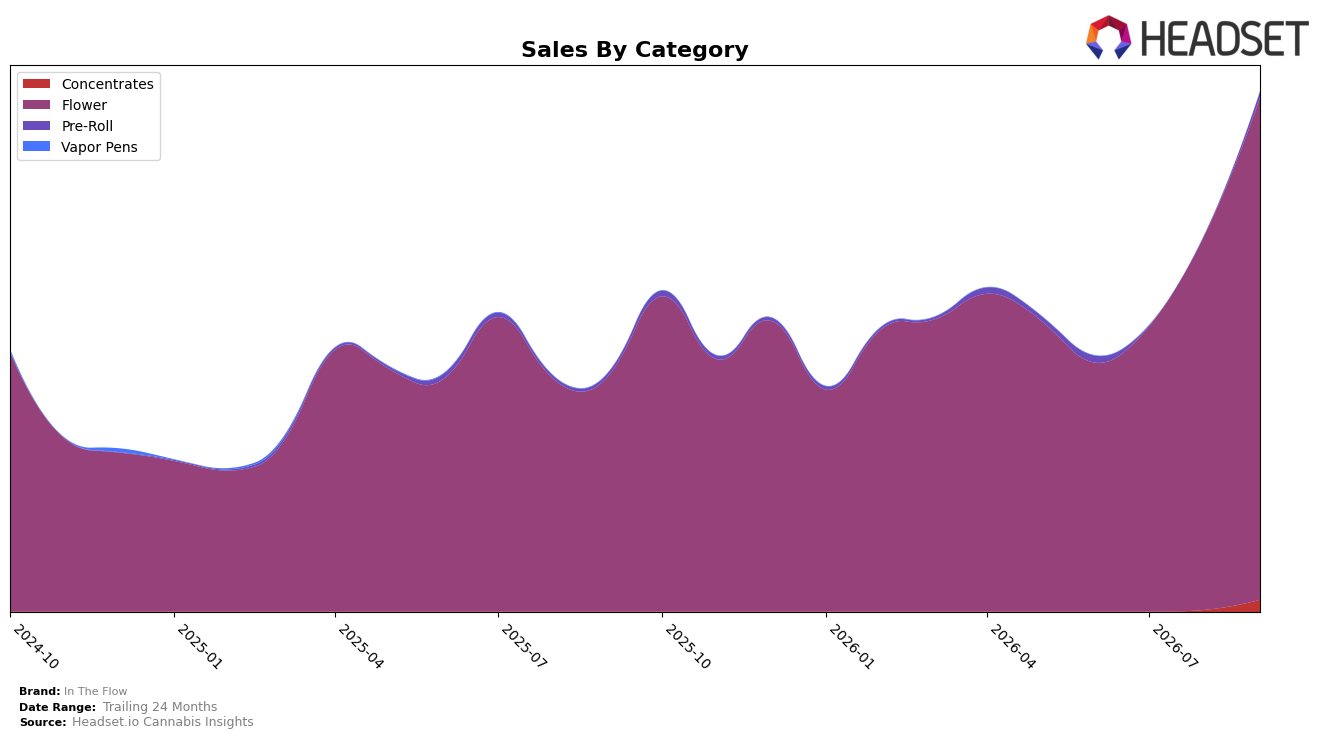
In The Flow concentrated 96.65% of September 2026 sales in Flower, with Flower up 113.55% year over year and 33.93% month over month, while the brand’s overall sales rose 118.08% year over year and average price increased 33.01%. Pre-Roll held 1.10% share with 83.68% year-over-year growth and a 6,700.10% month-over-month spike, and Concentrates reached 2.26% share with a 625.35% month-over-month jump; across this mix, the brand averaged $19.63 and ranked 5th in Flower in Colorado. The pattern implies a Flower-led engine that is widening the brand’s base while rapid month-over-month gains in Pre-Roll and Concentrates are testing adjacencies without yet diluting the Flower-led rank position.
The 33.93% month-over-month lift in Flower alongside a 625.35% jump in Concentrates and a 6,700.10% surge in Pre-Roll indicates incremental trial rather than cannibalization, supported by Flower still commanding 96.65% share and holding the number 5 Flower rank in Colorado. With average price up 33.01% year over year while Flower share remains above 95%, the brand is signaling pricing power within its core and using low-price entries in Pre-Roll (average $8.82) and Concentrates (average $8.61) as funnel extensions, implying a barbell positioning that can defend Flower rank while building optionality for mix-led margin management.
Competitive Landscape
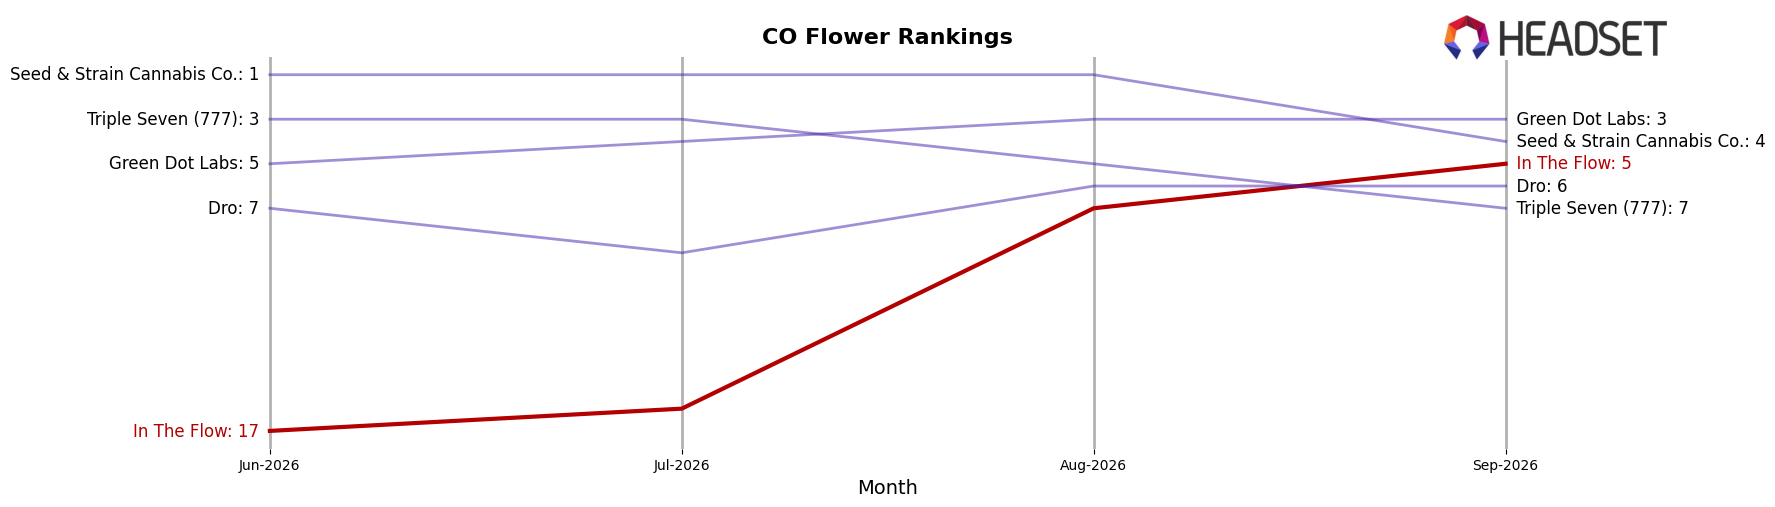
In The Flow ranks #5 in Colorado Flower in September 2026, up 7 positions year over year from #12, and up 12 ranks from June 2026 when it sat at #17; this climb to a new peak in September 2026 coincides with Seed & Strain Cannabis Co. sliding from #2 to #4 with a -33.5% YoY sales change, while Good Chemistry Nurseries advanced from #3 to #2 with +45.5% YoY growth. Against the category leader Green Label Cannabis holding #1 both this year and last with +38.0% YoY sales growth, In The Flow’s double-digit rank gains over both the year (+7) and the last three months (+12) indicate share is consolidating toward brands that either expanded distribution or tightened assortment, implying that In The Flow’s recent trajectory is driven more by competitive displacement than broad market lift.
Notable Products
The steepest movement in September 2026 is Chemmy Jones (1g) dropping 58.6% month over month to rank 6, while its sibling Chemmy Jones (3.5g) rose 6.8% to rank 7, indicating a shift from single-gram picks toward multi-gram value. Lemonhead Delight (Bulk) sits at rank 1 with $101,797 in sales and anchors a Flower-heavy lineup where eight of the top ten are Flower SKUs, whereas Chemmy Jones (Bulk) fell 43.7% at rank 5, pointing to pressure on bulk formats that are not tied to mid-size pack pricing. The concentration in Flower, combined with the split performance inside the Chemmy Jones family, implies In The Flow is migrating consumer demand toward mid-size Flower configurations over single grams and select bulk offerings.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

