


Where to Buy
LIT (CO) is stocked at 23 licensed dispensaries across Colorado, with the deepest coverage in Colorado Springs, Denver, Basalt, Aurora, and Avon. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
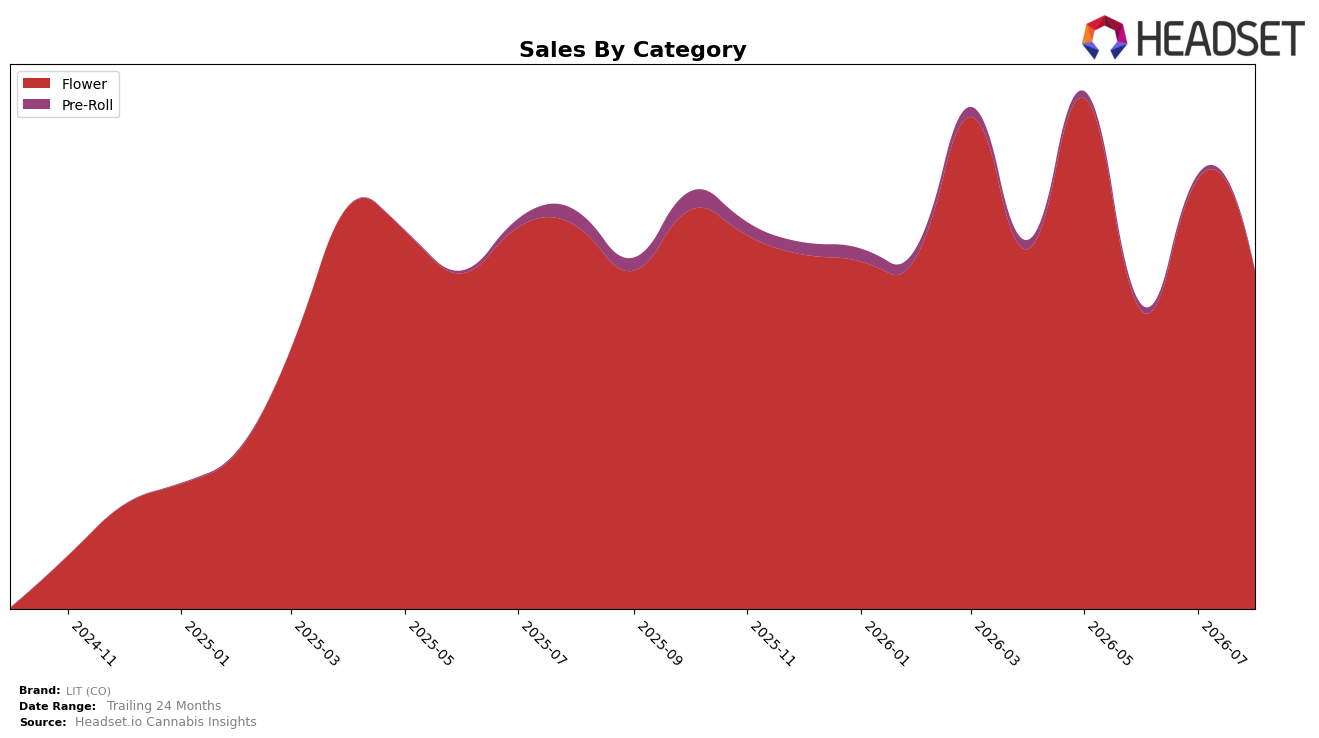
LIT (CO) concentrated 99.64% of August 2026 sales in Flower while Pre-Roll fell to 0.36% share, a configuration that coincided with a -12.43% year-over-year change in Flower and a -21.94% month-over-month pullback, alongside Pre-Roll declines of -91.82% year-over-year and -72.66% month-over-month. Despite an average price shift of -1.13% year-over-year to $22.12, the brand’s total sales moved -15.41% year-over-year, and its Flower rank sat at 14 in Colorado, implying that outsized exposure to a shrinking primary category concentrated the performance drag more than pricing did.
The August 2026 mix signals category concentration risk: with Flower at 99.64% share and down -21.94% month-over-month versus a far steeper -72.66% month-over-month in Pre-Roll, the portfolio lacks a counterweight when Flower volatility accelerates. Holding a rank of 14 in Colorado Flower while Pre-Roll erodes to 0.36% share suggests the brand’s positioning is tied to mid-pack Flower relevance rather than a multi-category footprint, implying that stabilization requires either deeper competitiveness within Flower or a deliberate re-entry into adjacent formats to buffer double-digit (-12.43% year-over-year) Flower swings.
Competitive Landscape
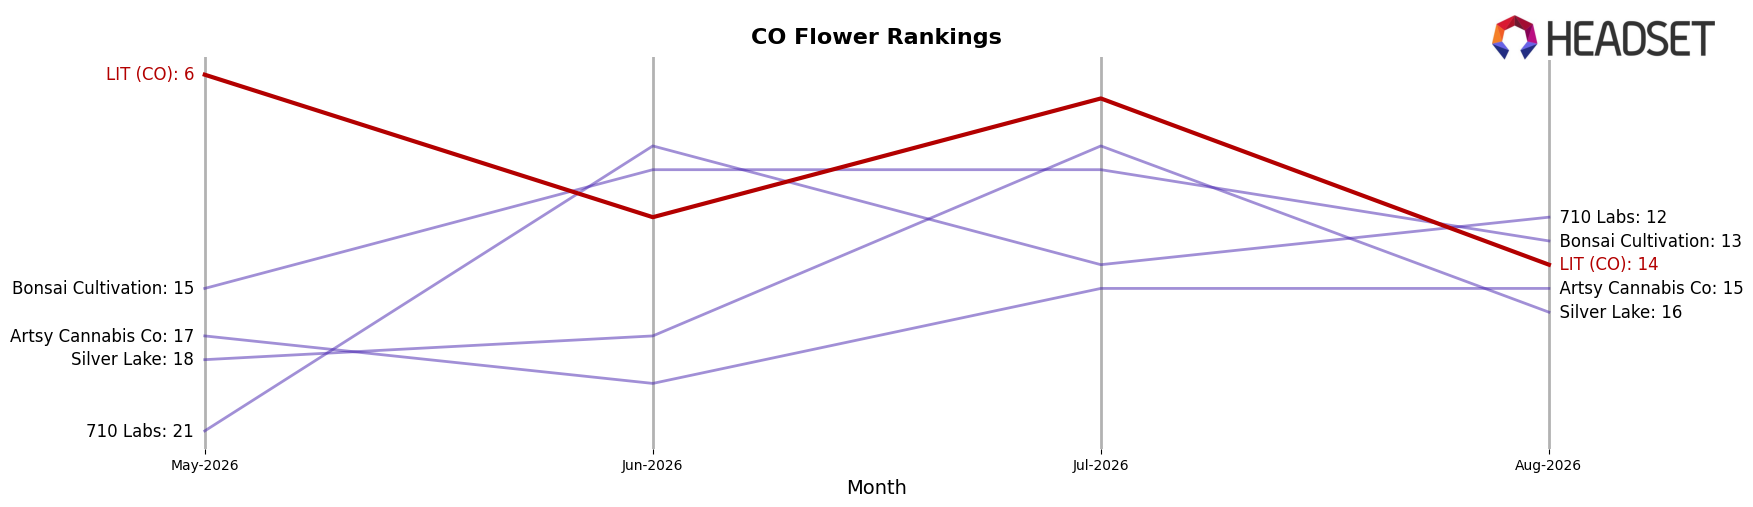
LIT (CO) sits at rank #14 in August 2026 after sliding 8 positions from #6 in May 2026, a drop that contrasts with Seed & Strain Cannabis Co. rising year over year from #2 to #1 and expanding sales by 44.85%, and with Green Dot Labs moving from #5 to #3 alongside a 36.47% sales lift; meanwhile, Good Chemistry Nurseries edged down from #3 to #4 with a 3.60% sales decline while Green Label Cannabis slipped from #1 to #2 despite a 1.27% sales increase, indicating that LIT (CO)’s fall from a peak rank of #6 in May 2026 to #14 in August 2026 reflects share being ceded to competitors gaining momentum even when their gains are modest.
Notable Products
Blue Garlic (Bulk) delivered the headline move in August 2026 with a +257.99% month-over-month surge into rank 1, while Blueberry Scone (Bulk) fell -52.92% at rank 9, indicating a rapid reallocation of demand within the same month. With Flower SKUs occupying all ten top positions and Blue Garlic (Bulk) at rank 1 versus Blueberry Scone (Bulk) at rank 9, the mix suggests a pivot toward high-velocity bulk formats even as certain bulk strains contract. Frozen Cola (28g) at rank 4 alongside Glue Ball (Bulk) at rank 2 signals that at least nine of the top ten are Flower, and the contrast between a triple-digit bulk gain and a -52.92% bulk decline points to strain-specific elasticity rather than a category-wide lift. This pattern implies LIT (CO) is consolidating around a few breakout Flower strains, prioritizing scale in bulk while cycling out underperforming varietals.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

