


Market Insights Snapshot
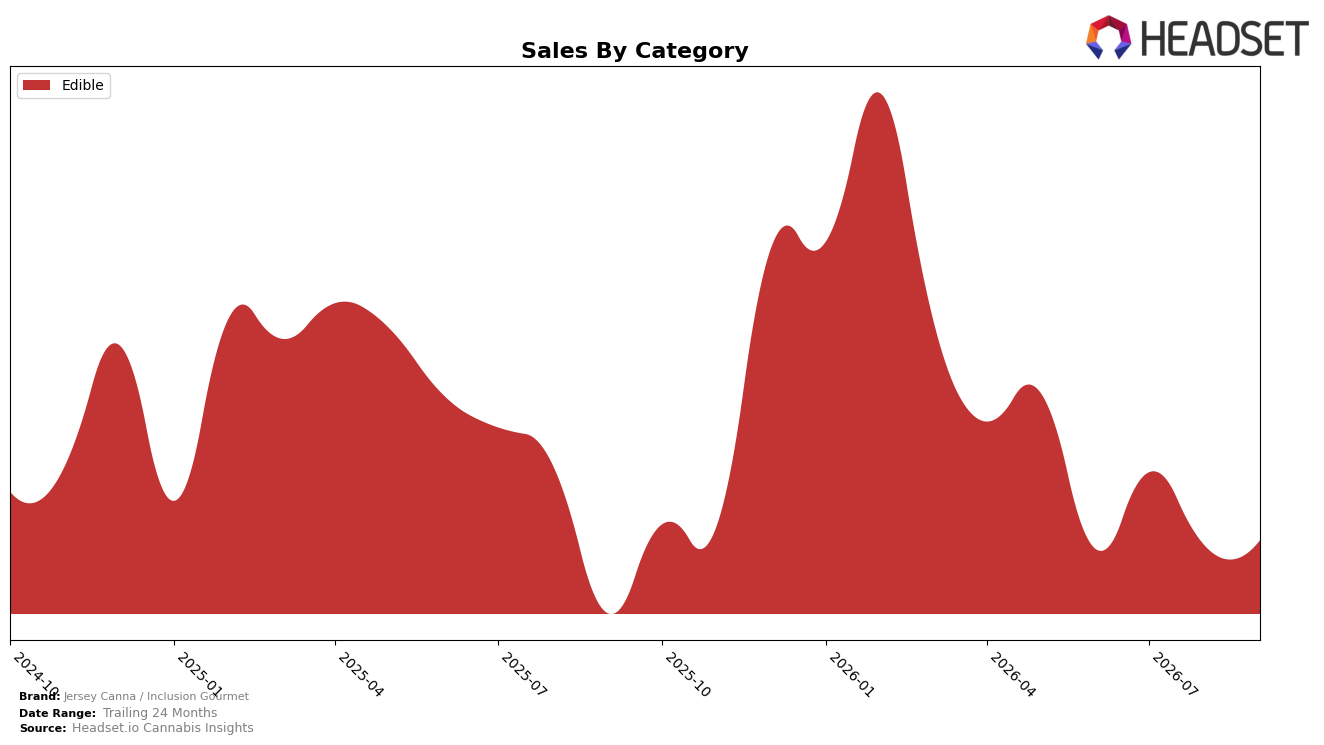
Jersey Canna / Inclusion Gourmet operated as a single-category brand in September 2026, with Edible at 100.0% of mix and a rank of 31 in New Jersey Edible, pairing 40.62% year-over-year sales growth with a 2.13% month-over-month lift. The average price fell 13.46% year over year to $22.21 while sales rose, indicating volume expansion despite a 47.04% decline over 24 months, and this combination implies the brand is trading price for velocity within Edible rather than diversifying categories.
The all-Edible focus and September 2026 rank of 31, alongside a 40.62% year-over-year gain and 2.13% month-over-month increase, suggest a mid-pack value positioning that leans on price elasticity more than premiumization. With Edible at 100.0% share and a 13.46% price decrease cushioning volume, the brand is consolidating around a single format to rebuild throughput after a 47.04% 24-month decline, implying that future share gains will depend more on sustaining lower price points and repeat rates than on expansion into adjacent categories.
Competitive Landscape
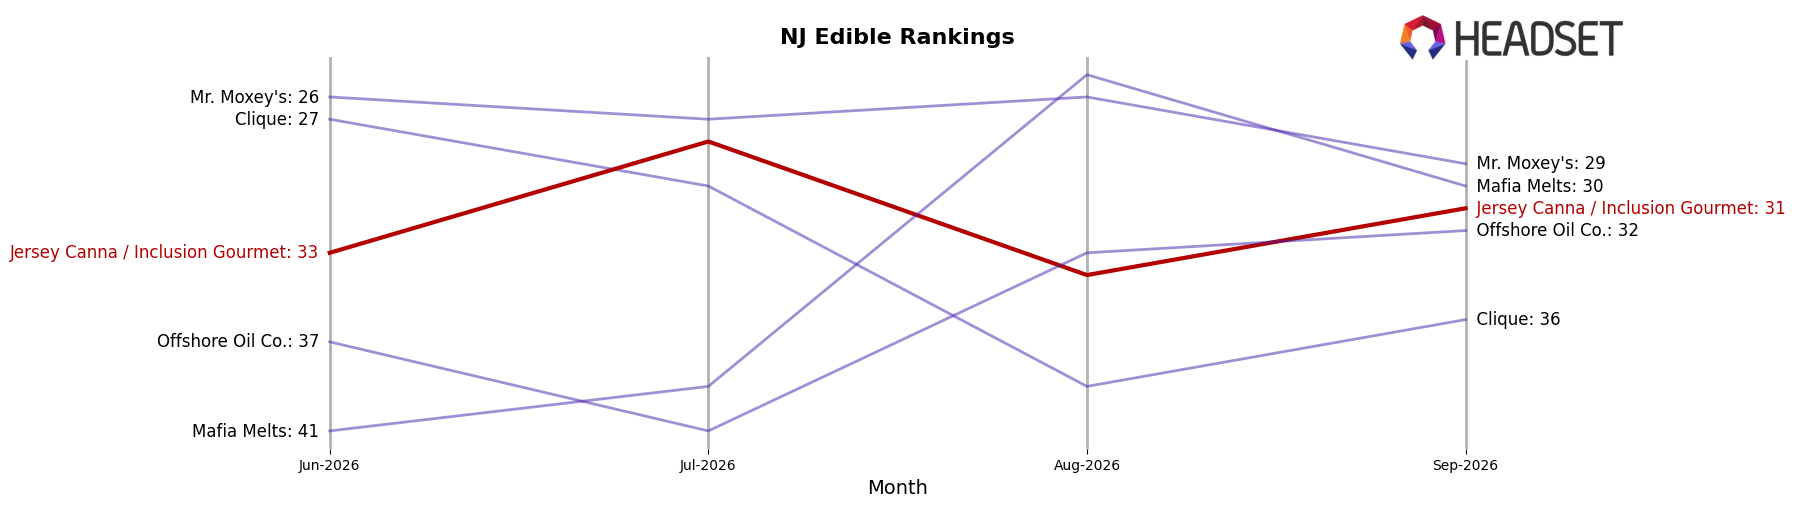
Jersey Canna / Inclusion Gourmet sits at rank #31 in New Jersey Edible with an 8-place improvement from #39 year over year, while slipping 2 positions from #33 in June 2026 to #31 in September 2026 on a three-month basis, and remaining 13 spots below its February 2026 peak at #18; in contrast, Wyld rose from #3 to #2 and Select fell from #2 to #4, indicating Jersey Canna / Inclusion Gourmet is gaining relative ground on brands losing rank even as it trails the category leaders; with Gron / Grön steady at #1 despite a 14.4% year-over-year sales decline and OGEEZ moving up from #7 to #5 on 21.6% year-over-year sales growth, the pattern implies Jersey Canna / Inclusion Gourmet’s upward year-over-year rank shift is tied to competitive churn at the top and positions the brand for incremental share capture if it can convert its February 2026 peak momentum back into consistent rank gains.
Notable Products
Peanut Butter Belgium Milk Chocolate Cup (50mg) posted the steepest decline at -26.6% MoM, slipping to a tied Rank 4 while Cannacubes - Sugar Free Dark Chocolate 10-Pack (100mg) fell -37.8% MoM to Rank 8, indicating price-sensitive or niche segments are retrenching as broader chocolate formats consolidate share. In contrast, Peanut Butter Cup Chocolate 2-Pack (100mg) rose +36.3% MoM to Rank 1 and Sativa Live Rosin Belgian Milk Chocolate 10-Pack (100mg) climbed +30.8% MoM to Rank 6, suggesting THC-forward, flavor-led SKUs are absorbing demand from underperforming variants. Four of the top ten are Cannabar bars, and total category momentum is clustering in classic milk and peanut butter profiles while specialty sugar-free and lower-dose options lose rank, a mix that implies a pivot toward fewer, higher-velocity core chocolates over experimental niches.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

