


Where to Buy
Jive is stocked at 59 licensed dispensaries across New York and Oklahoma, 50 of them in New York, with the deepest coverage in Depew, Queens, Brooklyn, Buffalo, and New York. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
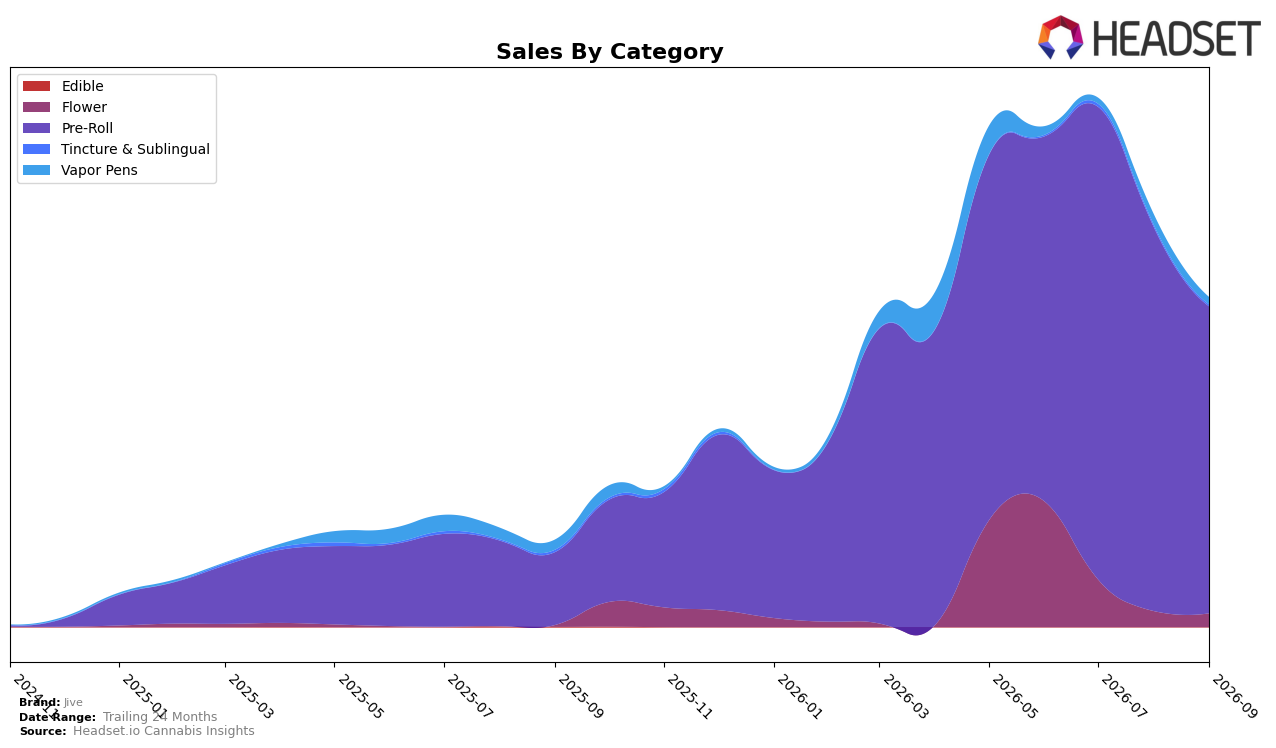
In September 2026, Jive concentrated 93.33% of sales in Pre-Roll, where year-over-year growth reached 322.66% even as month-over-month declined 20.15%; Flower held 4.10% share with an 842.31% year-over-year jump alongside a 14.26% month-over-month drop. Vapor Pens accounted for 2.11% share with a 29.14% year-over-year decline and a 32.54% month-over-month decline, while Tincture & Sublingual sat at 0.46% share with year-over-year down 21.69% and month-over-month down 16.75%. Against a brand-level year-over-year sales increase of 282.12% and an average price down 4.22%, the pattern implies volume-led expansion anchored in Pre-Roll, with diversification limited by double-digit month-over-month pullbacks outside Pre-Roll.
Jive’s positioning is anchored in Pre-Roll depth rather than multi-category breadth, as shown by a 93.33% share concentration and a New York Pre-Roll rank of 37, while Flower’s 842.31% year-over-year growth from a 4.10% share base suggests early traction rather than scale. With Vapor Pens down 29.14% year-over-year and 32.54% month-over-month, and Tincture & Sublingual also contracting 21.69% year-over-year, the mix tilts toward combustibles at lower average prices ($7.39 overall, $6.95 in Pre-Roll); this implies Jive competes most effectively in value-oriented Pre-Roll, with near-term upside coming from defending rank in New York while selectively nurturing Flower to reduce category concentration risk.
Competitive Landscape
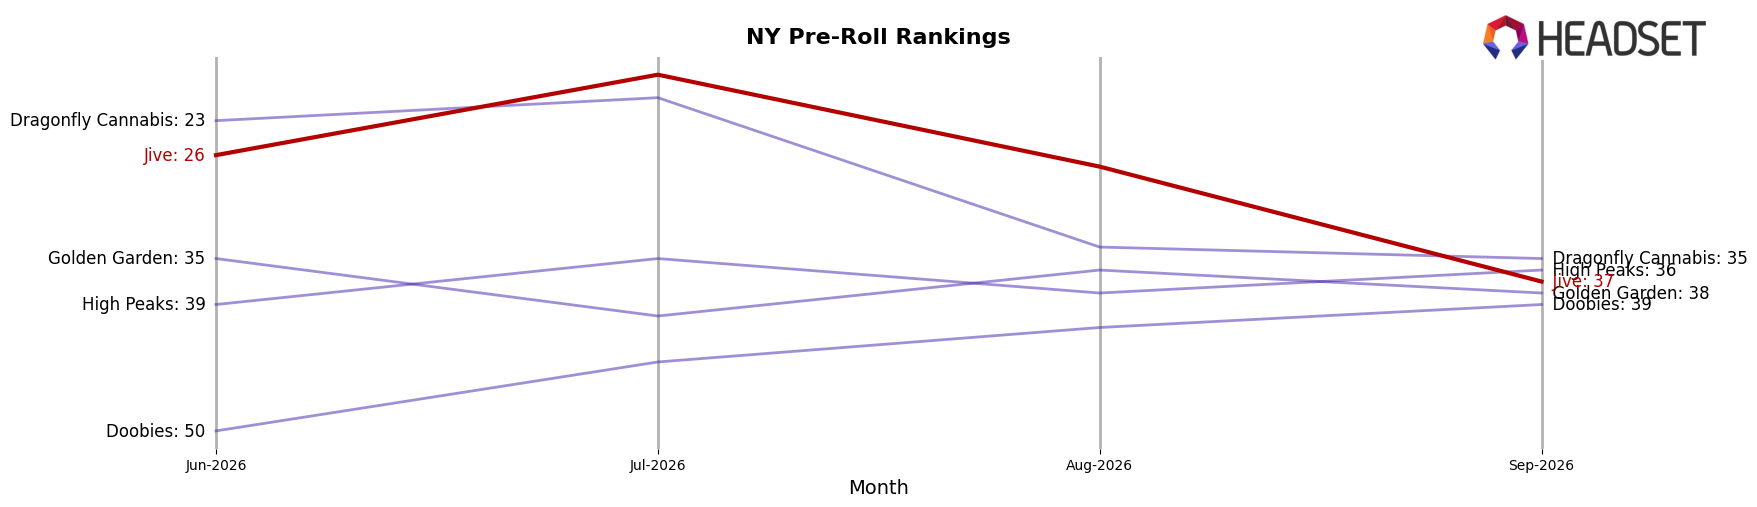
Jive sits at #37 in NY Pre-Roll in September 2026, a YoY climb of 53 ranks from #90, but it slipped 11 positions from #26 three months ago and remains 18 spots below its July 2026 peak at #19; meanwhile, Jeeter moved up from #6 to #2 with 122.48% YoY sales growth and Anthem advanced from #22 to #3 alongside 381.53% YoY growth, indicating that Jive’s rebound is outpaced by faster-rising rivals and its mid-year peak now looks like a transient spike rather than a sustained trajectory.
Notable Products
Blueberry Muffin Pre-Roll 2-Pack (1g) posted the standout move in September 2026 with a 189.9% month-over-month surge, vaulting to rank 4, while Don Carlos Pre-Roll 2-Pack (1g) fell 42.1% but still held rank 1. Planet of the Grapes Pre-Roll 2-Pack (1g) eased 6.4% at rank 2 as Humboldt Headband Pre-Roll 2-Pack (1g) slid 33.0% at rank 3, and Lemon Berry OG Pre-Roll 2-Pack (1g) advanced 42.8% at rank 5. With eight of the top ten skus in Pre-Roll and multiple steep declines alongside one outsized gain, the mix signals a pivot toward a few breakout Pre-Roll formats driving share while legacy Pre-Rolls compress.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

