
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Kush Masters (Kush Master LLC) is stocked at 71 licensed dispensaries across Colorado and Michigan, 69 of them in Colorado, with the deepest coverage in Denver, Colorado Springs, Boulder, Durango, and Aurora. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
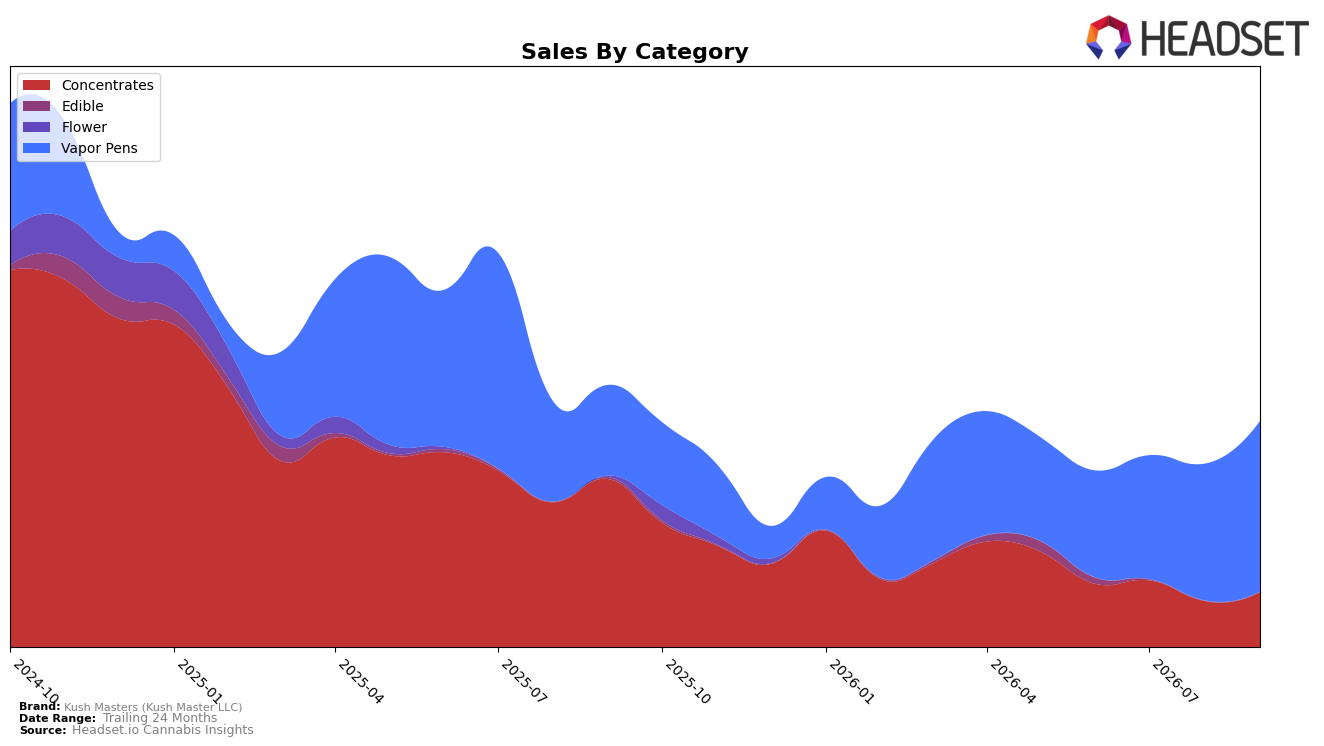
In September 2026, Kush Masters (Kush Master LLC) concentrated 75.62% of sales in Vapor Pens with year-over-year growth of 88.17% and month-over-month growth of 24.84%, while Concentrates fell to 24.38% share with a year-over-year decline of 67.34% but a 19.32% month-over-month uptick. Despite brand-level sales decreasing 13.82% year over year and average price rising 7.25% year over year to $16.53, Vapor Pens’ average price at $16.68 and Concentrates at $16.08 suggest mix-driven resilience against the 51.13% two-year sales decline. The pattern implies the brand is pivoting toward Vapor Pens as the primary engine, using category momentum to offset structural erosion in Concentrates.
With Vapor Pens now the dominant mix at 75.62% and ranked 44 in Colorado Vapor Pens, the brand is leaning into a category where scale and visibility can improve velocity even as overall brand sales are down 13.82% year over year. The concurrent 24.84% month-over-month gain in Vapor Pens versus a 19.32% month-over-month lift in Concentrates indicates near-term execution favors Vapor Pens, while the 67.34% year-over-year drop in Concentrates limits multi-category hedge. The positioning implication is clear: consolidating around Vapor Pens can stabilize share in Colorado, but sustaining traction will require either continued Vapor Pen share capture or selective revival of Concentrates to mitigate category concentration risk.
Competitive Landscape
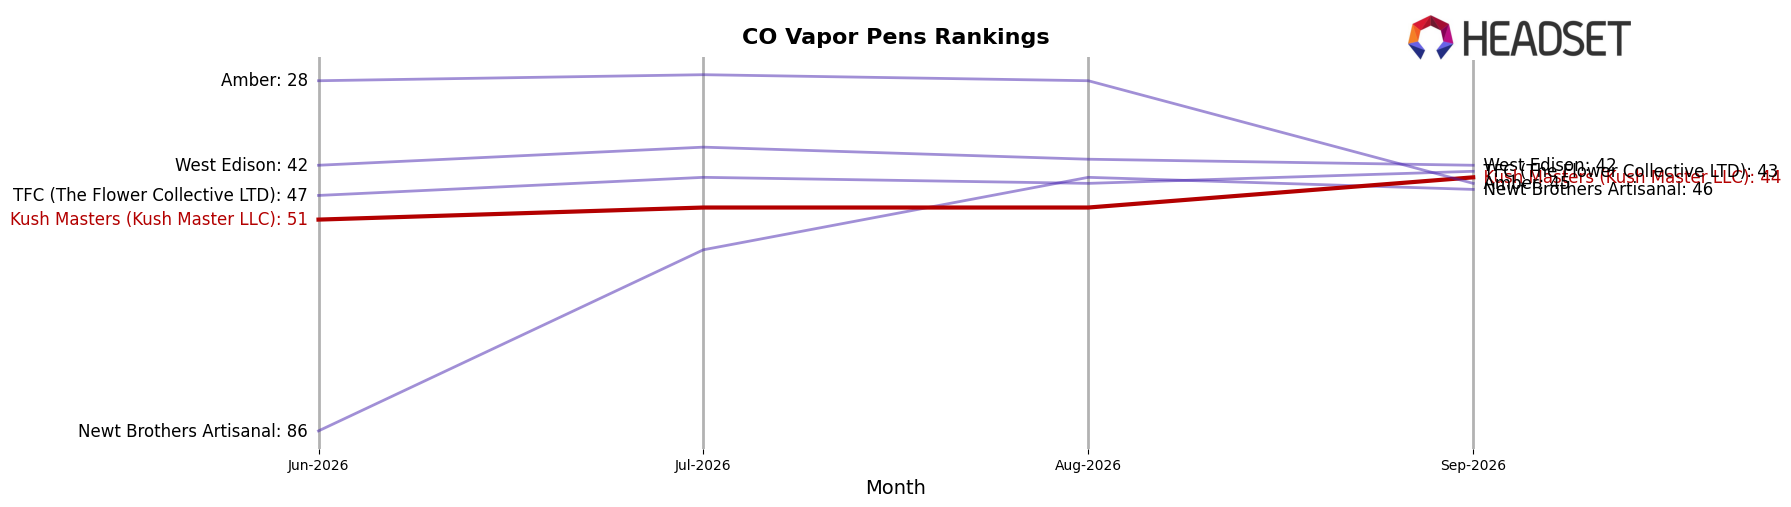
Kush Masters (Kush Master LLC) sits at rank #44 in CO Vapor Pens in September 2026, improving 15 positions from #59 year over year and 7 positions from #51 in June 2026, while still trailing its peak of #40 from July 2025; by contrast, PAX advanced from #3 to #2 with 34.7% YoY sales growth and Jetty Extracts leapt from #15 to #4 alongside a 150.9% YoY sales increase, indicating the middle tier is compressing as leaders widen separation. With Spherex holding #1 year over year and currently at #1 while Kush Masters (Kush Master LLC) remains outside the top 40, the split between modest rank gains (+15 YoY; +7 since June 2026) and faster-rising competitors implies share recovery is underway but pace must accelerate to convert into sustained top-40 reentry.
Notable Products
Spiced Peached Cured Resin Cartridge (1g) posted the headline move in September 2026 with a 133.7% month-over-month surge that vaulted it to rank 3, while Cherry Punch Cured Resin Cartridge (1g) slid 15.4% to rank 7, signaling a reshuffle within the mid-tier. Blueberry Limone Cured Resin Cartridge (1g) also accelerated 89.9% MoM to rank 4, whereas Apricot Scones Cured Resin Cartridge (1g) contracted 41.4% at rank 9, indicating polarization between winners and laggards inside the same Vapor Pens lineup. With eight of the top ten in September 2026 concentrated in Vapor Pens and two SKUs tied at rank 4, the mix points to Kush Masters (Kush Master LLC) leaning into a few breakout flavors while pruning underperformers, a shift that favors scaling hit cartridges over broad variety. The $6,772 result for Blueberry Limone Cured Resin Cartridge (1g) alongside the rank-1 Jet Fuel Cured Resin Cartridge (1g) implies the brand is consolidating share at the top of the portfolio through momentum SKUs rather than incremental launches.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

