

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
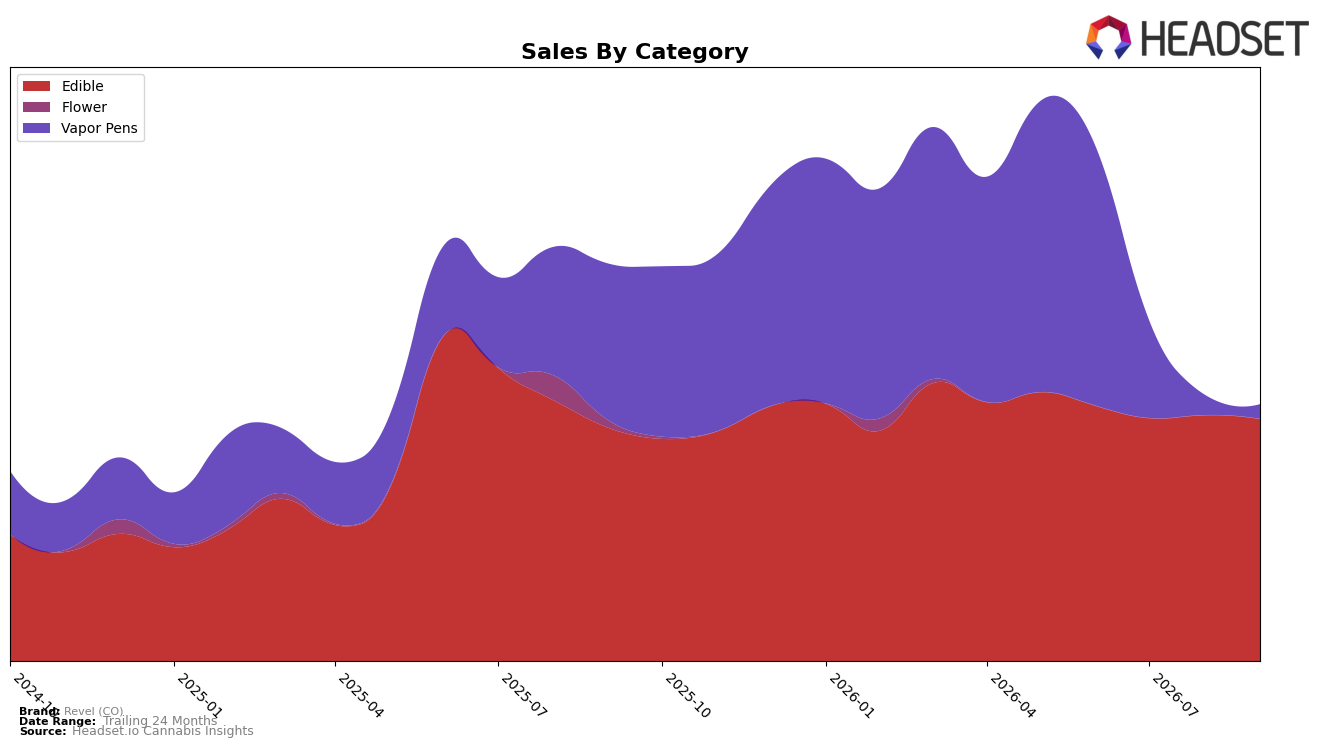
In September 2026, Revel (CO) concentrated 94.41% of sales in Edible, with Vapor Pens at 5.59%, marking a sharper tilt toward Edible versus August 2026 as Vapor Pens fell 29.08% MoM while Edible dipped only 1.51% MoM. Year over year, Edible grew 3.74% while Vapor Pens declined 90.85% YoY, reshaping mix toward the lower-priced Edible average of $10.72 versus $18.72 in Vapor Pens and aligning with a 14.32% YoY drop in overall average price; the pattern implies intentional or forced retrenchment into Edible to stabilize volume despite a brand-level sales decline of 35.46% YoY.
Within Colorado Edible, Revel (CO) held rank 8 in September 2026, pairing a 3.74% YoY Edible lift with a 1.51% MoM dip while total brand sales fell 35.46% YoY and the 24‑month trajectory rose 72.83%. The divergence—Edible resilience versus brand-wide YoY contraction and a collapsing 5.59% share in Vapor Pens—suggests pricing and assortment are pushing Revel (CO) toward a value-leaning Edible position where incremental price elasticity can offset unit softness, but sustained rank 8 implies headroom will likely come more from deepening Edible penetration than from reviving Vapor Pens in the near term.
Competitive Landscape
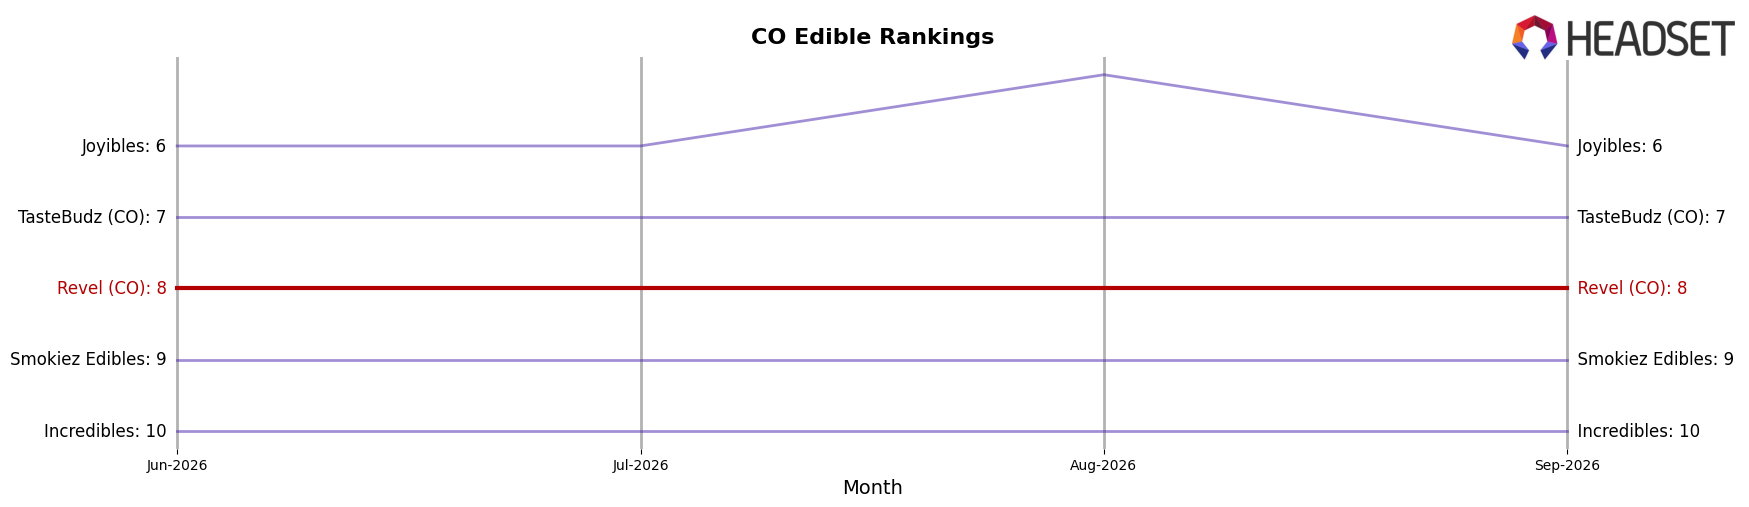
Revel (CO) sits at rank #8 in Colorado Edible for September 2026, unchanged from #8 in September 2025, with a flat three-month position at #8 and a historical peak of #7 in June 2025; meanwhile, Wana rose from #2 to #1 as its year-over-year sales grew 10.5%, while Wyld slipped from #1 to #2 with a -23.8% sales change, and Dialed In Gummies held #3 with 30.6% growth, indicating that stability at #8 amid leaders trading places suggests Revel (CO) is anchored in the mid-tier unless it converts incremental share gains into a move back toward its #7 peak.
Notable Products
The CBD:THC 1:1 Wild Blueberry Distillate Cartridge (1g) posted the steepest pullback at -51.4% month over month while sitting at rank 6, and the Carnival Floss Distillate Cartridge (1g) fell even harder at -66.6% at rank 10; in contrast, Galactic Grape Distillate Cartridge (1g) climbed 23.1% to rank 9. Edibles still anchor the top with THC/CBG 2:1 Uplifted Mango Tangerine Gummies 10-Pack (100mg THC, 50mg CBG) at rank 1 despite a -3.1% dip and the CBD/CBN/THC 1:1:1 Sleepy Strawberry Gummy 20-Pack (100mg CBD , 100mg CBN, 100mg THC) at rank 2 with +1.2%, while four of the top ten are Vapor Pens that collectively split between double-digit gains and double-digit declines. This bifurcation implies a portfolio tilting toward stable, mood- or function-specific edibles as the revenue spine, while Vapor Pens act as a volatile test bed where SKU rationalization could unlock steadier share.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

