

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Legend is stocked at 263 licensed dispensaries across New Jersey, Maryland, and 2 other states, 125 of them in New Jersey, with the deepest coverage in Jersey City, Atlantic City, Camden, Newark, and Trenton. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
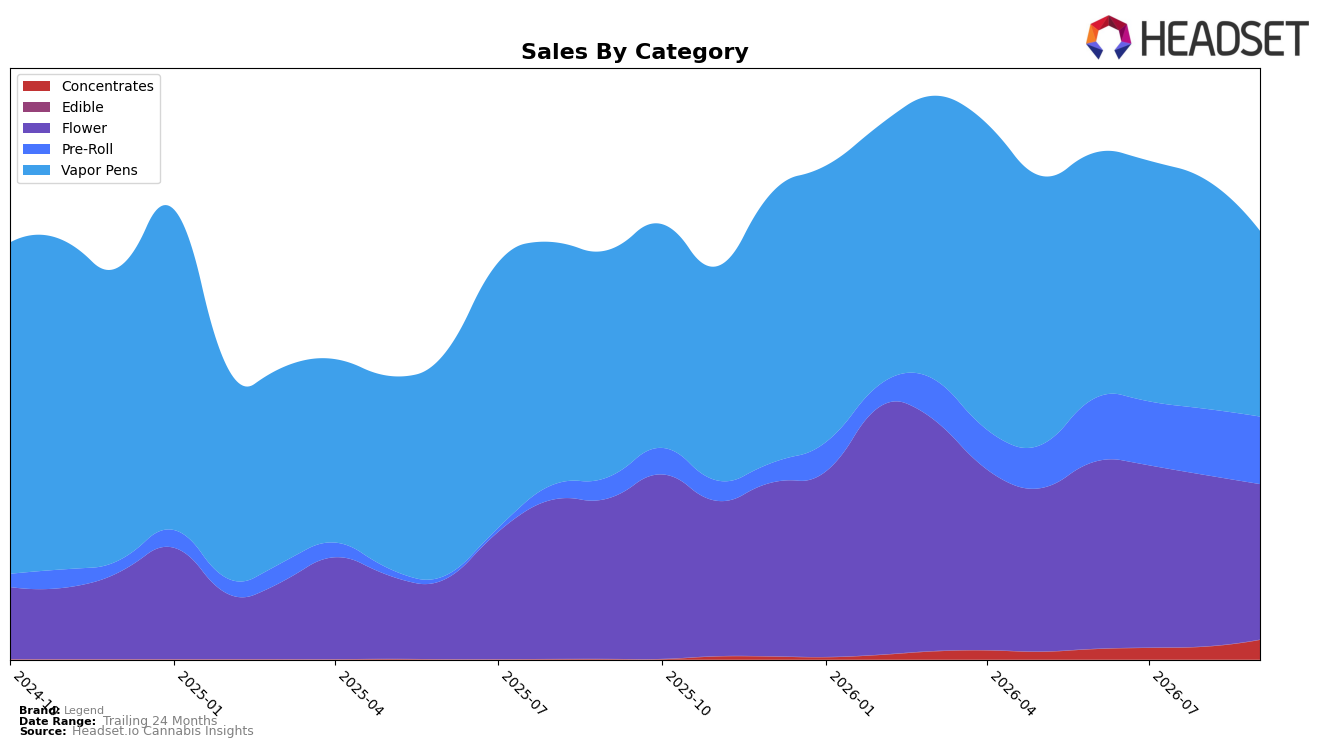
In September 2026, Vapor Pens held 43.38% share with year-over-year down 18.26% and month-over-month down 19.17%, while Flower at 36.32% share declined 3.15% YoY and 9.33% MoM. Pre-Roll expanded to 15.73% share with 220.02% YoY growth and a 1.98% MoM increase, and Concentrates, though only 4.57% share, surged 8,592.34% YoY and 53.70% MoM. Against a brand-level sales change of 4.67% YoY and a 25.13% YoY drop in average price to $35.45, the mix shift is pulling revenue toward lower-priced units while reducing dependence on categories with double-digit MoM declines; the thesis is that September 2026 marked a pivot from a Vapor Pens- and Flower-heavy portfolio toward faster-growing Pre-Roll and nascent Concentrates to stabilize growth.
Legend’s third-place rank in Vapor Pens in New Jersey signals that maintaining a 43.38% mix in a category with double-digit declines risks ceding aggregate momentum, whereas reallocating toward Pre-Roll’s 220.02% YoY and Concentrates’ 53.70% MoM growth could improve rank resilience outside a single category. With Flower falling 9.33% MoM and Vapor Pens falling 19.17% MoM, the expanding 15.73% Pre-Roll share and rising Concentrates penetration imply a positioning move toward breadth and price-accessible velocity, supported by the 25.13% YoY reduction in average price; the thesis is that Legend is trading mix toward faster-turning formats to buffer volatility in its lead category while preserving a premium anchor via Flower’s 36.32% share.
Competitive Landscape
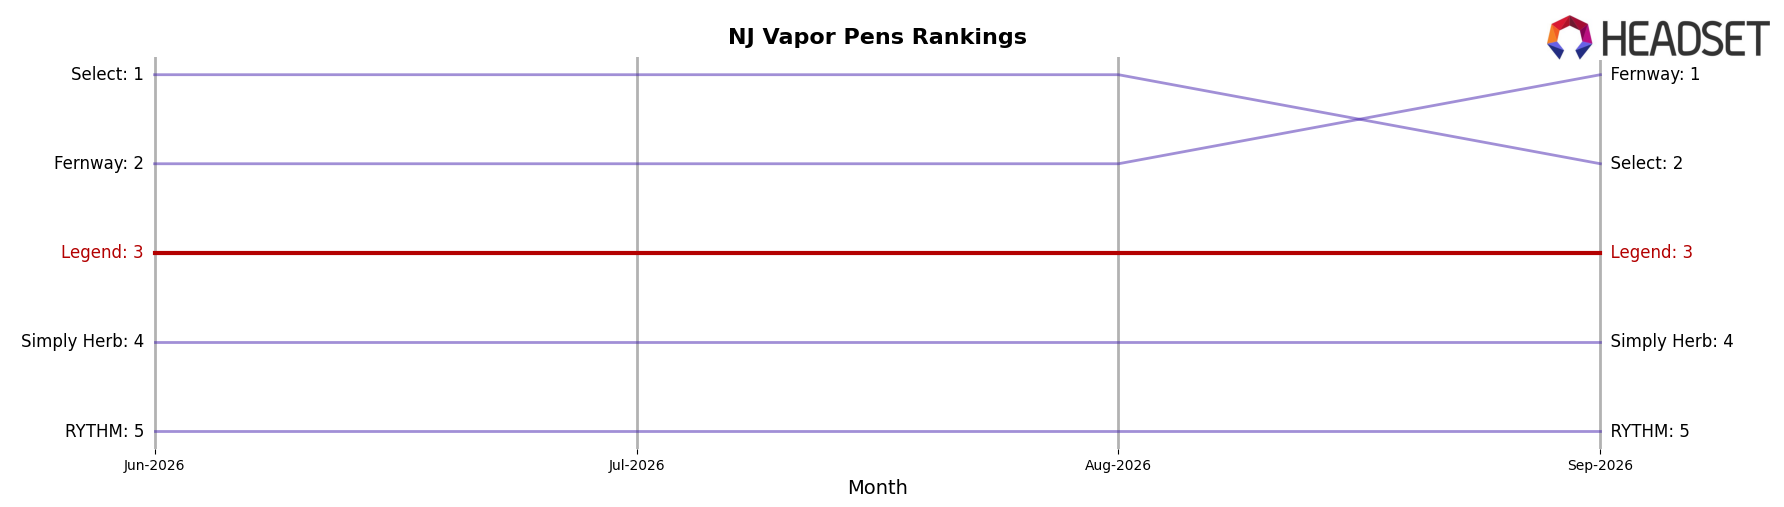
Legend sits at rank #3 in NJ Vapor Pens in September 2026, unchanged from #3 year over year and steady at #3 over the last three months, while peak rank also holds at #3 in September 2026; in contrast, Fernway climbed from #2 to #1 with a 19.2% YoY sales gain and Select slipped from #1 to #2 with a 24.0% YoY sales decline. Flanking pressure appears limited as Simply Herb remained at #4 with a 14.6% YoY decline and RYTHM stayed at #5 with a 9.2% YoY decline, positioning Legend between a rising leader and retreating followers. The pattern implies Legend’s unchanged #3 rank is a share-holding plateau: upside requires displacing a growing #1, while downside risk is muted by weakening competitors immediately below.
Notable Products
Sour Mango Distillate Cartridge (1g) posted the steepest movement in September 2026 with a -22.8% month-over-month drop while sitting at rank 2, and Kiwi Berry Distillate Cartridge (1g) also contracted by -10.0% at rank 3. Sour Diesel Pre-Roll (1g) held rank 1 with $29,791 in sales, and Vapor Pens concentrated four of the top ten while showing pressure at the very top two vapor SKUs. This pattern implies Legend’s mix is tilting toward Pre-Roll leadership even as Vapor Pens keep breadth, signaling a need to stabilize flagship cartridges while leaning into multi-pack and value-oriented Pre-Rolls.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

