

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Pacific Stone is stocked at 358 licensed dispensaries across California, with the deepest coverage in Los Angeles, San Diego, Sacramento, San Francisco, and Santa Ana. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
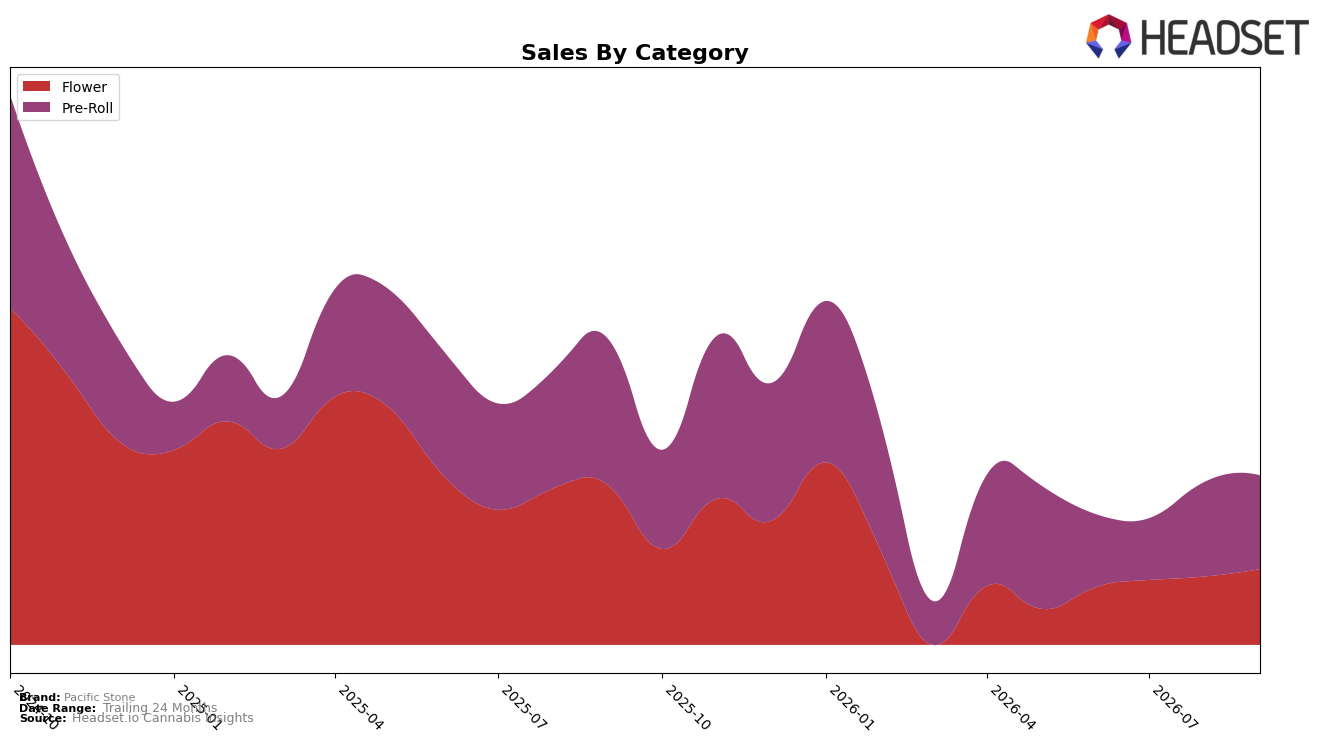
In September 2026, Pacific Stone split nearly evenly between Pre-Roll at 50.88% share and Flower at 49.12% share, but the balance shifted via divergent momentum: Pre-Roll declined 9.16% year over year and slipped 0.15% month over month, while Flower fell 14.23% year over year yet grew 1.47% month over month. Average price contracted 12.86% year over year to $22.71, with Pre-Roll averaging $20.84 and Flower $25.04, aligning with overall brand sales down 11.72% year over year and 23.21% over 24 months. In California Pre-Roll, the brand held rank 9, indicating that despite category pressure the portfolio still commands a top-10 foothold; the pattern implies a tactical tilt toward stabilizing Flower mix gains without eroding Pre-Roll’s rank-sensitive volume.
The mixed trend—Flower’s 1.47% month-over-month lift against Pre-Roll’s 0.15% month-over-month dip, coupled with a 12.86% year-over-year price compression—suggests Pacific Stone is leaning on price to defend share while rebalancing toward higher-ticket Flower. With Pre-Roll contributing 50.88% of sales but posting a 9.16% year-over-year decline versus Flower’s steeper 14.23% decline, near-term positioning likely benefits from protecting rank 9 in California Pre-Roll while selectively nurturing Flower’s month-over-month recovery; the implication is that incremental gains in Flower can improve mix economics if pricing discipline maintains basket value without accelerating volume loss.
Competitive Landscape
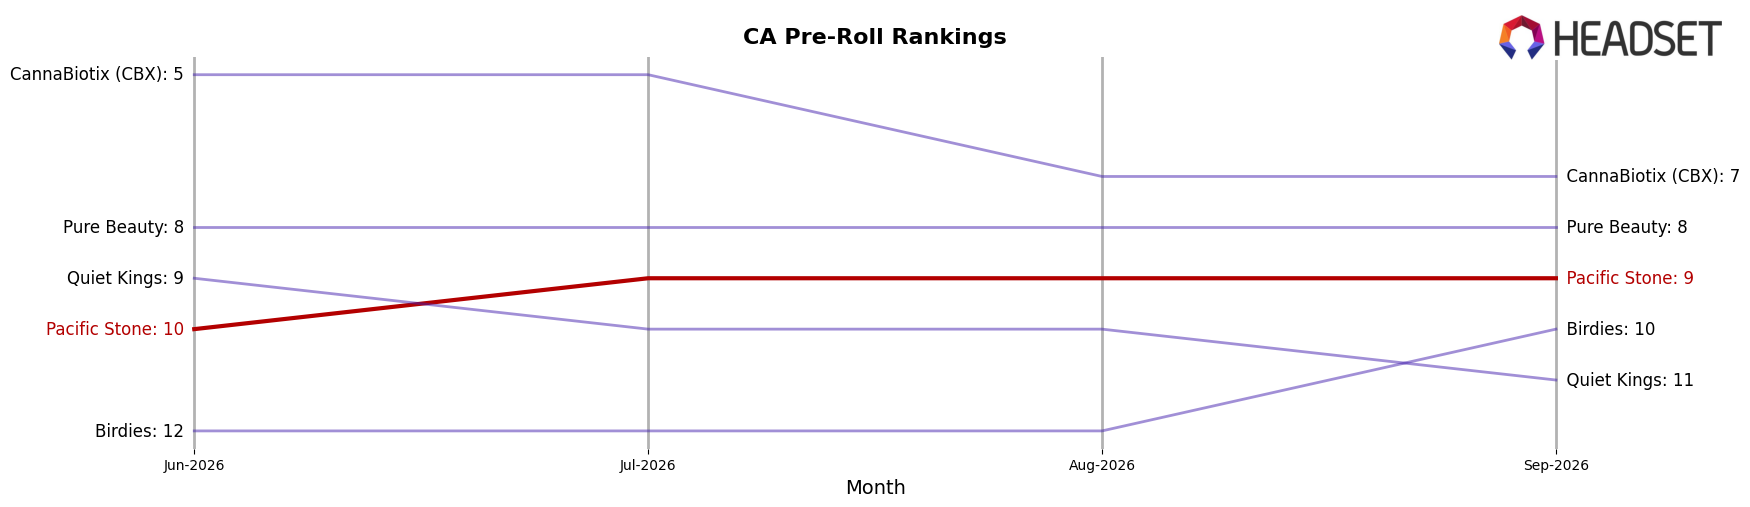
Pacific Stone sits at rank #9 in CA Pre-Roll for September 2026, down one spot from #8 in September 2025, while its three-month position edged from #10 in July 2026 to #9 in September 2026; the brand’s historical ceiling of #5 in October 2024 contrasts with the current two-rank gap behind that peak and a one-rank YoY decline. Against competitors, Jeeter held #1 year-over-year with a 16.0% sales lift and Claybourne Co. climbed from #6 to #4 with approximately 19.3% YoY growth, indicating that Pacific Stone’s slight YoY slippage and modest three-month uptick imply a plateauing position where incremental gains are not yet closing distance on faster-advancing leaders.
Notable Products
Wedding Cake Pre-Roll 2-Pack (1g) posted the steepest movement in September 2026 with a -17.2% month-over-month drop while holding rank 3, as Blue Dream Pre-Roll 14-Pack (7g) slipped -8.2% at rank 1. Across the top 10, seven SKUs are Pre-Rolls and occupy ranks 1, 2, 3, 5, 7, 8, and 10, indicating category concentration even as Flower entries like Wedding Cake (3.5g) rose +6.5% at rank 4 and Blue Dream (3.5g) advanced +23.9% at rank 6. This pattern implies Pacific Stone is leaning on multi-pack Pre-Rolls for scale while selectively nurturing Flower to buffer against double-digit volatility in smaller Pre-Roll formats.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

