


Where to Buy
Lit Labs is stocked at 119 licensed dispensaries across Michigan, Illinois, and Washington, 110 of them in Michigan, with the deepest coverage in New Buffalo, Detroit, Ann Arbor, Monroe, and Bay City. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
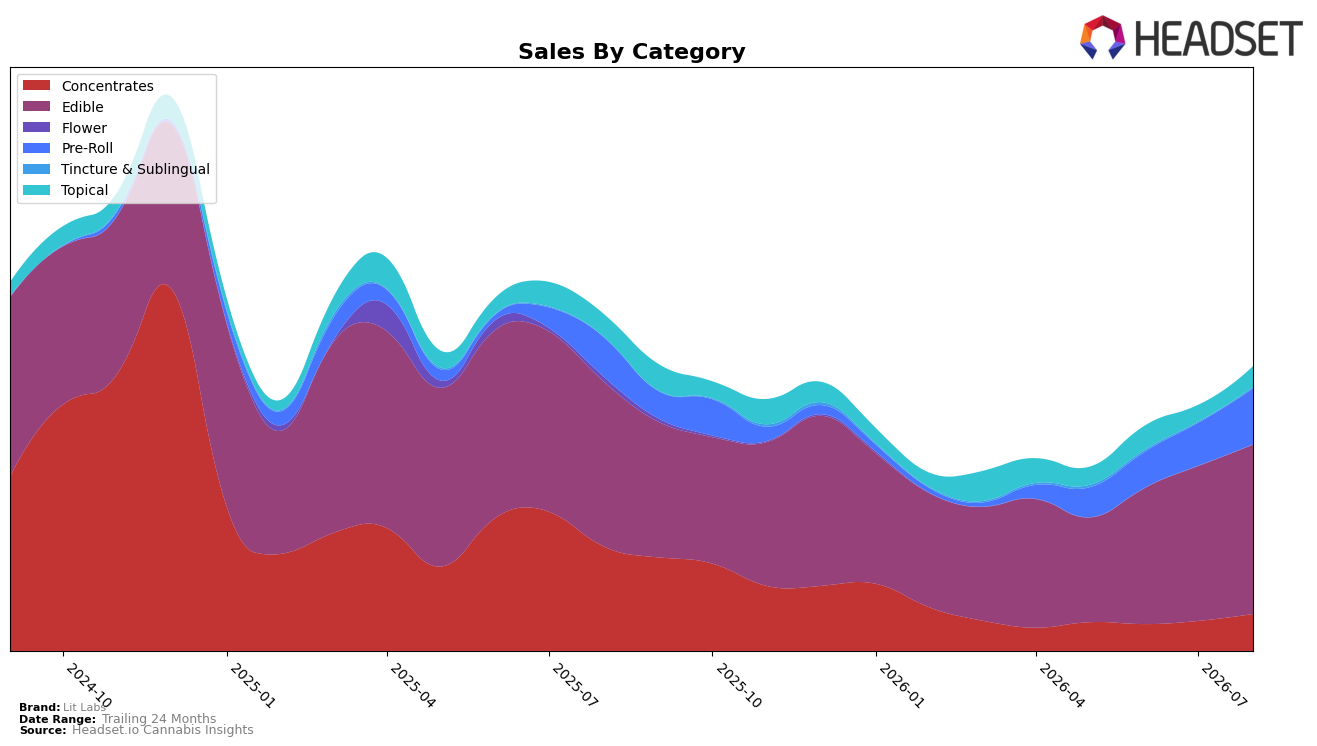
In August 2026, Lit Labs concentrated 59.74% of sales in Edible with year-over-year growth of 2.75% and month-over-month growth of 9.35%, while Pre-Roll expanded to a 19.69% share with 42.03% YoY and 30.76% MoM, and Concentrates contracted to 12.96% share with -64.78% YoY despite a 23.66% MoM rebound. Topical held 7.24% share with -8.90% YoY and 24.06% MoM, and Tincture & Sublingual remained niche at 0.37% share with a 41.87% MoM uptick and no YoY comp. Against a brand-level YoY sales decline of 15.53% and an average price drop of 13.94%, the mix shift toward Edible and Pre-Roll indicates reliance on lower-priced, faster-turning formats, while a rank of 52 in Edible in Illinois suggests mid-pack category presence that can scale if MoM gains persist.
The pattern implies Lit Labs is migrating demand toward volume-led categories: Edible, with a current average price of $3.40, and Pre-Roll, at $8.79, are offsetting Concentrates’ -64.78% YoY drag and Topical’s -8.90% YoY softness through double-digit MoM gains of 9.35% and 30.76%, respectively. With total average price down 13.94% YoY and Concentrates still only recovering MoM by 23.66% from a much lower base, the brand’s positioning tilts toward value-accessible occasions rather than premium potency, which aligns with a 59.74% Edible share and supports near-term share defense but limits pricing power unless Concentrates regains share above 12.96% or Topical steadies beyond 7.24%.
Competitive Landscape
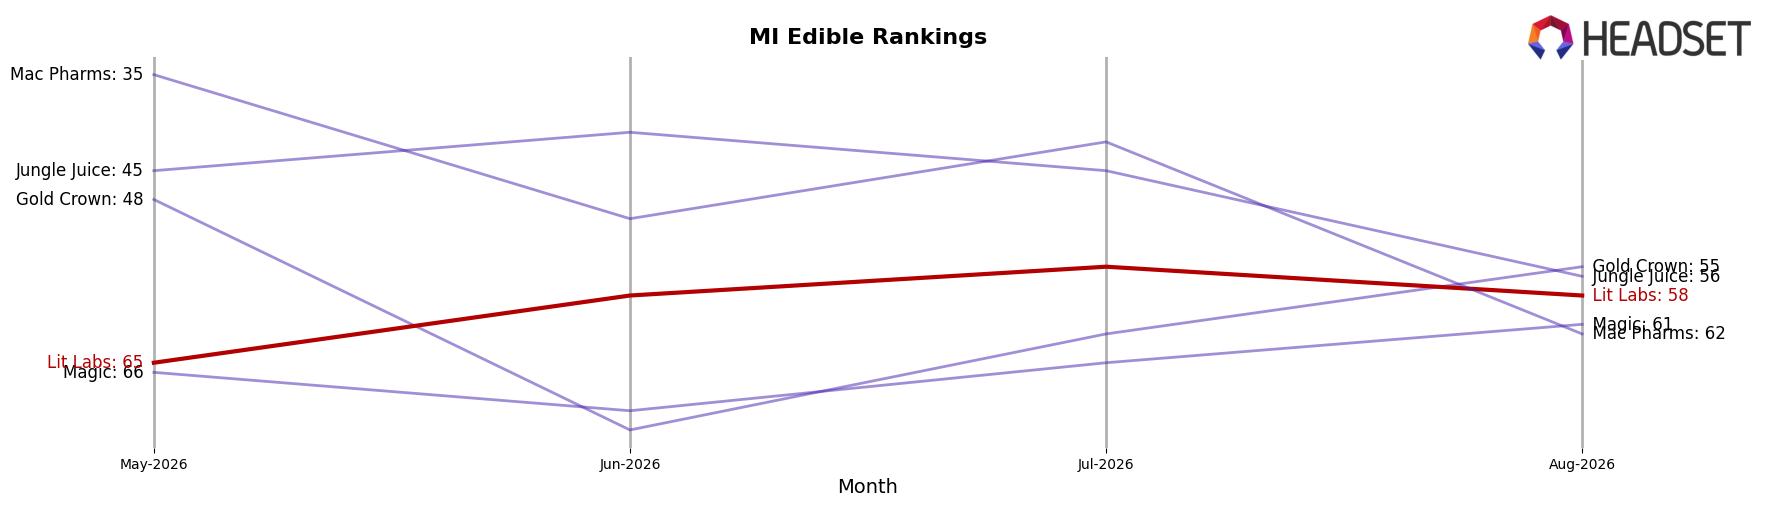
Lit Labs sits at rank #58 in MI Edible in August 2026, down 2 positions year over year from #56 and up 7 positions since May 2026 when it was #65; against this, category leaders moved in mixed directions, with Wyld steady at #1 while reporting a -22.8% sales change year over year and Play Cannabis climbing from #11 to #5 alongside a 22.7% sales increase, indicating that Lit Labs is holding share better quarter over quarter than year over year. Lit Labs remains 13 spots below its peak of #45 from September 2024 while MKX Oil Company slipped from #3 to #4 despite a 0.2% sales lift and Camino improved from #4 to #3 on 22.1% growth, suggesting that without a similar velocity gain Lit Labs’ current upward quarter is unlikely to translate into a sustained rank recovery.
Notable Products
Blue Razz Rosin + Resin Full Spectrum Gummies 10-Pack (200mg) posted the standout move in August 2026 with a +55.2% month-over-month surge to rank 1, while Pineapple Rosin + Resin Full Spectrum Vegan Gummies 10-Pack (200mg) fell -43.5% to rank 3. Mango Rosin + Resin Full Spectrum Vegan Gummies 10-Pack (200mg) also declined -14.5% at rank 4 as Tropical Medley Rosin + Resin Full Spectrum Vegan Gummies 10-Pack (200mg) climbed +40.6% to rank 5. With all top-10 SKUs in Edible gummies and four of the top five carrying the Rosin + Resin Full Spectrum positioning, the mix points to Lit Labs consolidating around solventless-forward gummies where flavor variety is being used to rotate demand across SKUs.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

