

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Loud + Clear is stocked at 98 licensed dispensaries across California, with the deepest coverage in San Diego, Sacramento, Lake Elsinore, Los Angeles, and San Jose. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
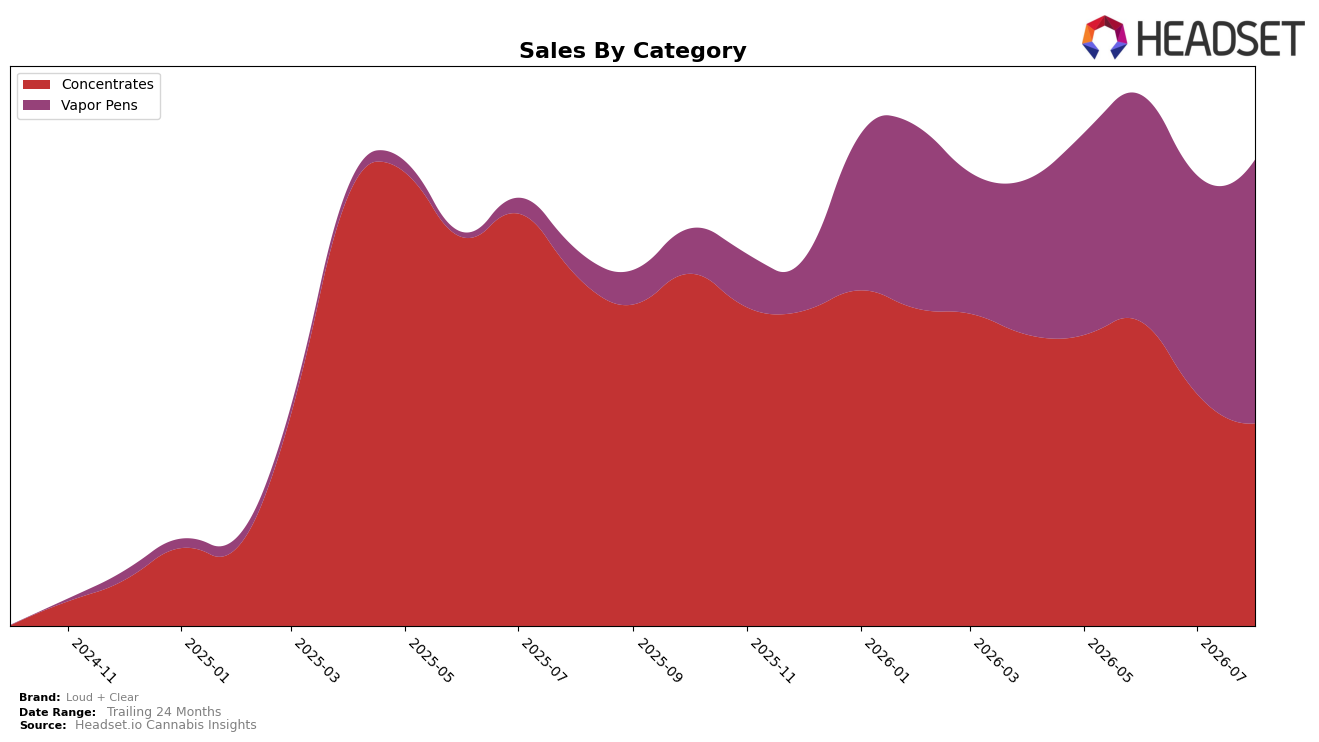
In August 2026, Vapor Pens expanded to 56.56% category share with a 916.65% year-over-year surge and a 20.64% month-over-month increase, while Concentrates contracted to 43.44% share with a -42.27% year-over-year decline and a -12.54% month-over-month slide. Despite a -28.46% year-over-year drop in average price to $17.73, overall brand sales rose 23.74% year over year, indicating mix-driven volume gains as Vapor Pens with a $16.51 average price outpaced Concentrates at $19.62. The pattern implies Loud + Clear is reorienting toward higher-velocity, lower-priced Vapor Pens, making category expansion rather than pricing the core driver of August 2026 performance.
The pivot sharpened Loud + Clear’s positioning in Vapor Pens, where the brand held rank 70 in California while gaining 20.64% month over month in that category and ceding 12.54% month over month in Concentrates. With Vapor Pens contributing 56.56% of mix and posting 916.65% year-over-year growth versus Concentrates’ -42.27% year-over-year decline, the brand’s competitive path centers on building depth where it already commands faster share momentum. The implication is a deliberate trade-off: prioritize distribution and assortment in Vapor Pens to climb from rank 70, accepting near-term share softness in Concentrates to consolidate identity around a value-leaning, volume-accretive pen portfolio.
Competitive Landscape
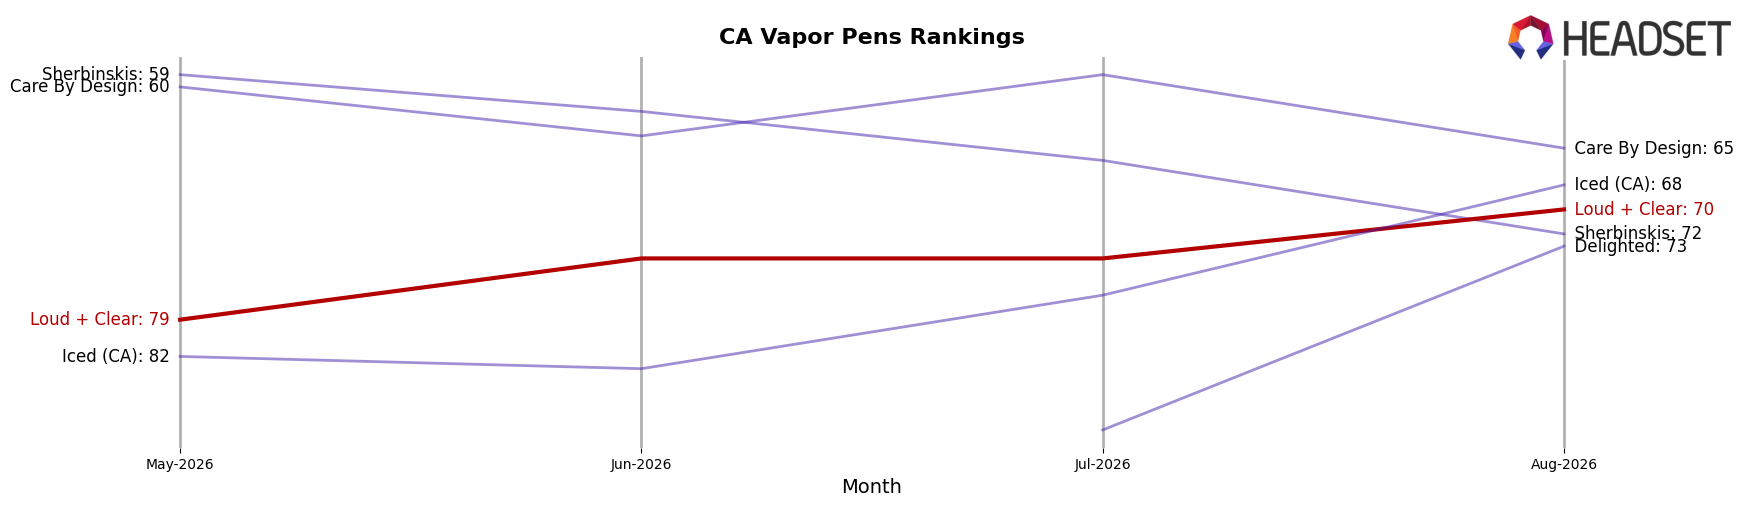
Loud + Clear sits at rank #70 in CA Vapor Pens in August 2026, improving 114 positions from #184 a year earlier and rising 9 spots from #79 three months ago; this new peak of #70 in August 2026 coincides with top-tier competitors holding steady or shifting at the top, as STIIIZY remained #1 year over year while contracting by 10.9% in sales and Jetty Extracts climbed from #4 to #3 with 40.5% sales growth. Relative to the upper tier where Raw Garden held #2 with flat (-0.0%) year-over-year sales and Plug Play slipped from #3 to #4 amid a 14.3% decline, Loud + Clear’s ascent from #184 to #70 indicates distribution or assortment expansion outpacing the mid-pack and suggests headroom for further share capture if the three-month improvement of 9 ranks persists.
Notable Products
The steepest movement came from Tropical Punch Liquid Diamonds Cartridge (1g), which fell 21.7% month over month to rank 9, while the category-leading Blueberry Diesel Live Resin Flavor Dab (2g) slid 9.0% at rank 1. In contrast, Tropical Punch Liquid Diamonds Disposable (1g) rose 25.4% to rank 2, and Pink Guava Liquid Diamonds Live Resin Disposable (1g) added 6.7% at rank 7. Eight of the top ten SKUs are Vapor Pens, and that concentration alongside a $24,346 month for the Tropical Punch Liquid Diamonds Disposable (1g) implies Loud + Clear is leaning into inhalable convenience formats where disposables are gaining share at the expense of cartridges.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

