


Where to Buy
ME Cannabis is stocked at 13 licensed dispensaries across Nevada, with the deepest coverage in Las Vegas, Henderson, North Las Vegas, Sparks, and Mesquite. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
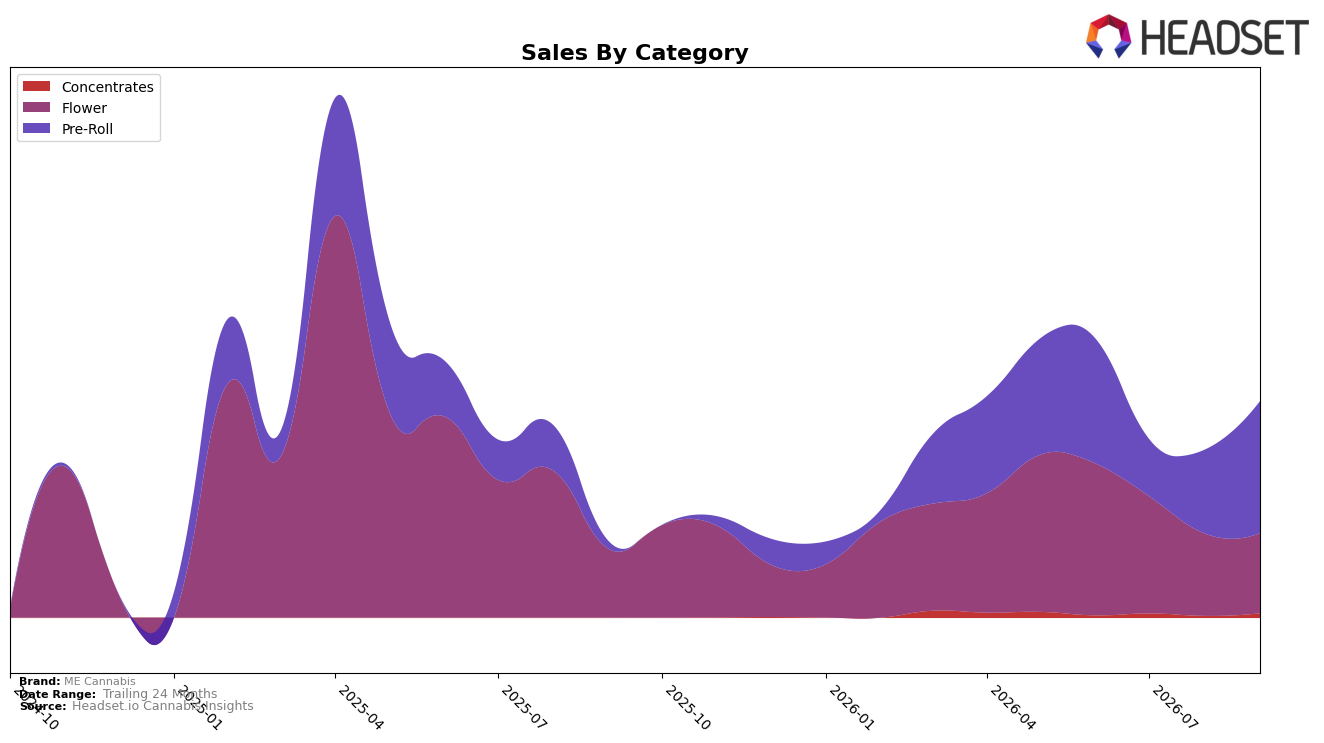
In September 2026, ME Cannabis concentrated 61.01% of sales in Pre-Roll with a 57.78% month-over-month lift and a 1,645.53% year-over-year surge, while Flower held 36.97% share with a -2.75% MoM decline and a 16.13% YoY increase; Concentrates was 2.02% share with a 145.49% MoM jump but no year-over-year baseline. Average price fell 66.58% YoY to $6.72, with category-level pricing split between a low Pre-Roll average ($4.62) and higher Flower pricing ($23.69). This mix shift implies ME Cannabis is pivoting toward value-led Pre-Roll volume while ceding relative weight in Flower, setting up a category-led expansion path anchored by rapid Pre-Roll velocity and opportunistic experiments in Concentrates.
Within Nevada Pre-Rolls, ME Cannabis sits at rank 24 alongside a 57.78% MoM share build in that category and a 1,645.53% YoY gain, indicating headroom to climb the rankings as price-driven trial converts to repeat. The simultaneous -2.75% MoM Flower dip and 145.49% MoM growth in Concentrates signals a deliberate reallocation toward formats with faster turn and promotional elasticity; combined with the 66.58% YoY price compression and a 36.97% Flower share base, this suggests a positioning strategy centered on accessible Pre-Roll scale with selective premium adjacencies rather than a broad premium basket.
Competitive Landscape
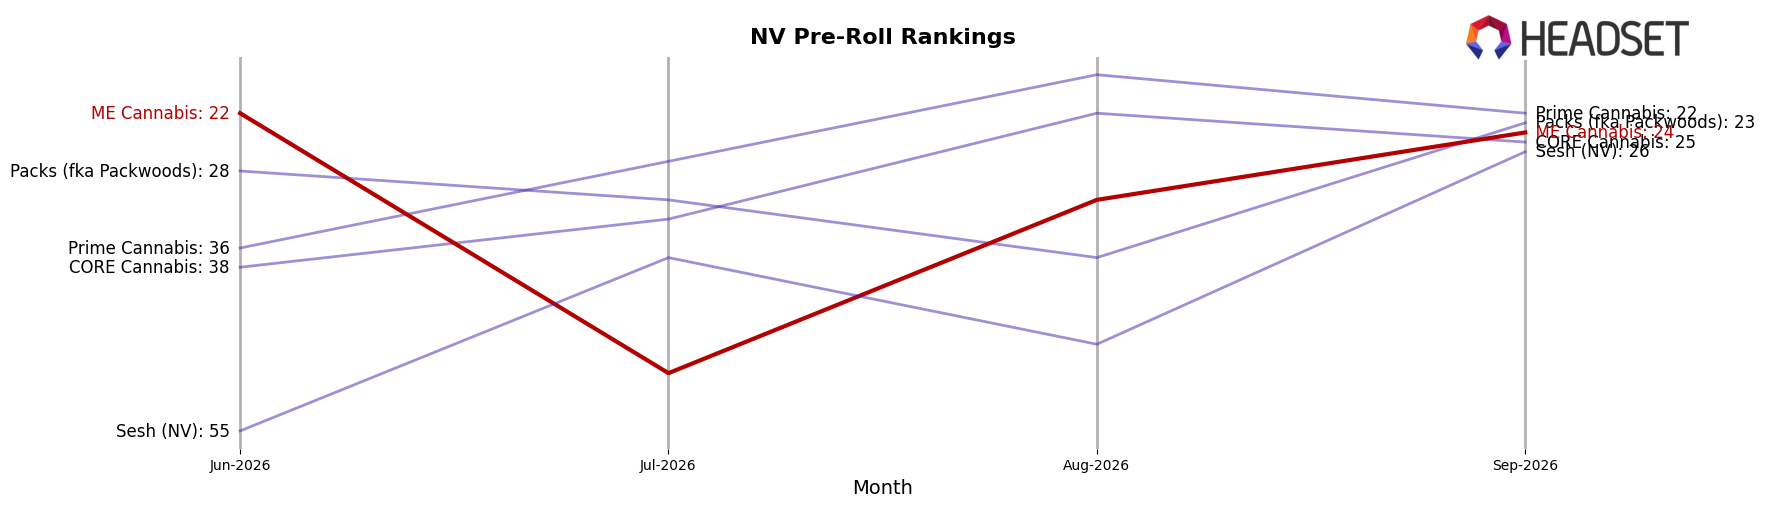
ME Cannabis sits at rank #24 in NV Pre-Roll in September 2026 after rising 60 positions year over year from #84, but slipping 2 spots from its June 2026 peak of #22 to #24 indicates recent softening against leaders. Against competitors, Rove climbed from #4 to #1 with a 44.6% YoY sales increase while STIIIZY eased from #1 to #2 with a -39.0% YoY sales change, signaling a reshuffle at the top that ME Cannabis has not yet translated into rank gains beyond its June 2026 high. The combination of a 60-rank YoY climb and a 2-rank quarter-over-quarter drift implies ME Cannabis is in recovery mode with momentum that now relies on converting mid-tier stability into sustained top-20 penetration.
Notable Products
Sourdough Pre-Roll (1g) posted the standout move in September 2026 with a +1,090.6% month-over-month surge to an estimated $20,061 and a jump to rank 1, while Poochie's Papaya Pre-Roll (1g) fell 34.1% to rank 3 and White Truffle Pre-Roll (1g) declined 38.0% to rank 5. Three of the top five SKUs are Pre-Rolls, and four of the top ten are also Pre-Rolls, indicating a category tilt even as Mimosa Pie (3.5g) held rank 7 with a marginal 0.6% dip. The combination of a newcomer spike at rank 1 and concurrent double‑digit declines among other Pre-Rolls implies sharp intra-category substitution rather than broad category expansion.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

