

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Mt Baker Homegrown is stocked at 53 licensed dispensaries across Washington, with the deepest coverage in Seattle, Tacoma, Spokane, Anacortes, and Bellingham. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
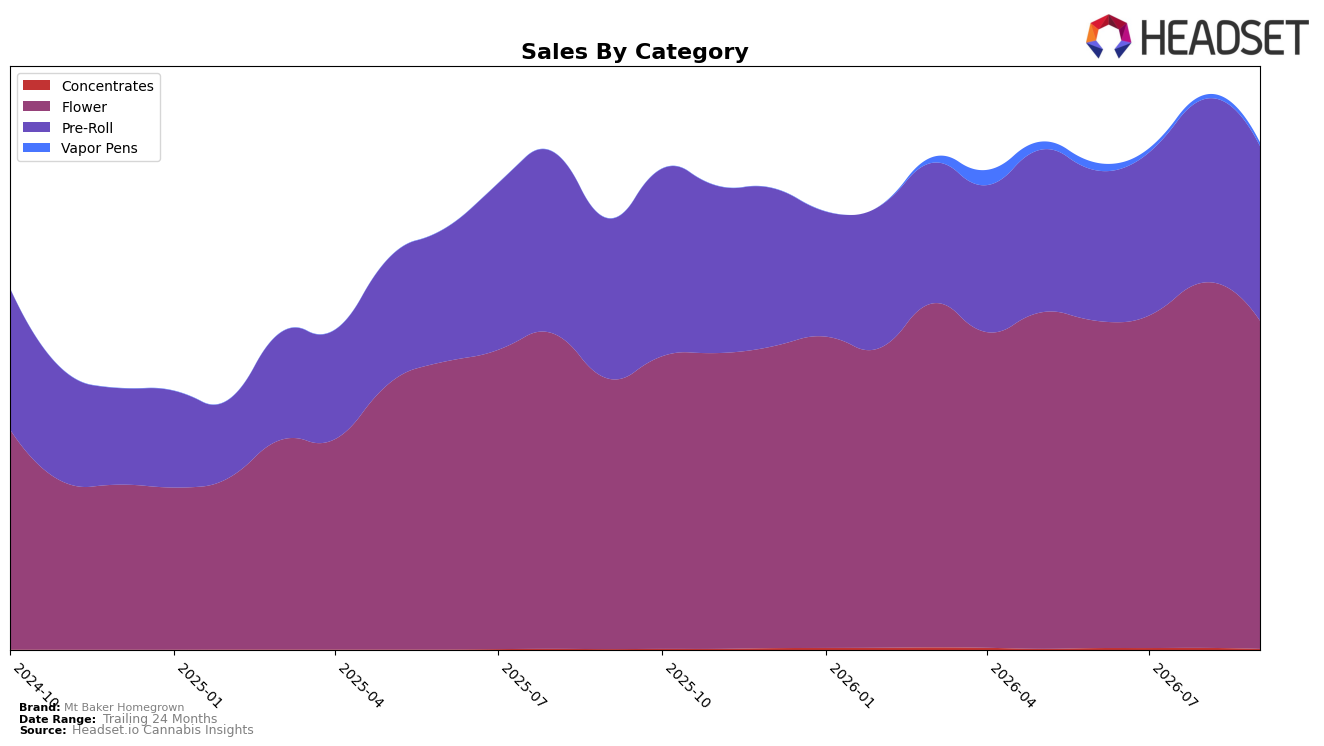
In September 2026, Mt Baker Homegrown concentrated 64.74% of sales in Flower and 34.46% in Pre-Roll, with Vapor Pens and Concentrates combining for just 0.81% share; that mix widens dependence on two categories as rank 20 in Flower within Washington meets a -10.23% month-over-month contraction in Flower and a -4.70% month-over-month dip in Pre-Roll. Year over year, Flower expanded 21.34% while Pre-Roll rose 9.12%, contrasting with a -14.75% month-over-month decline in Vapor Pens and a -55.46% month-over-month drop in Concentrates; with brand sales up 17.59% year over year and average price up 8.93%, the pattern implies a price-led, Flower-heavy portfolio that gains annually but softens sequentially at the category level.
The shift toward higher Flower weight alongside a 21.34% year-over-year increase and a -10.23% month-over-month pullback suggests positioning anchored in core inhalables where seasonal or promo cycles can swing volume more than price, while the 9.12% year-over-year rise in Pre-Roll and its -4.70% month-over-month slide indicate secondary support rather than a hedge. With Vapor Pens at 0.65% share and Concentrates at 0.16% share despite a 35.64% year-over-year uptick in Concentrates, the near-zero base constrains diversification; paired with rank 20 in Flower in Washington and an 8.93% average price increase, the pattern implies Mt Baker Homegrown is competing on mainstream Flower value tiers more than breadth, leaving headroom in accessories categories but requiring steadier Pre-Roll execution to buffer Flower volatility.
Competitive Landscape
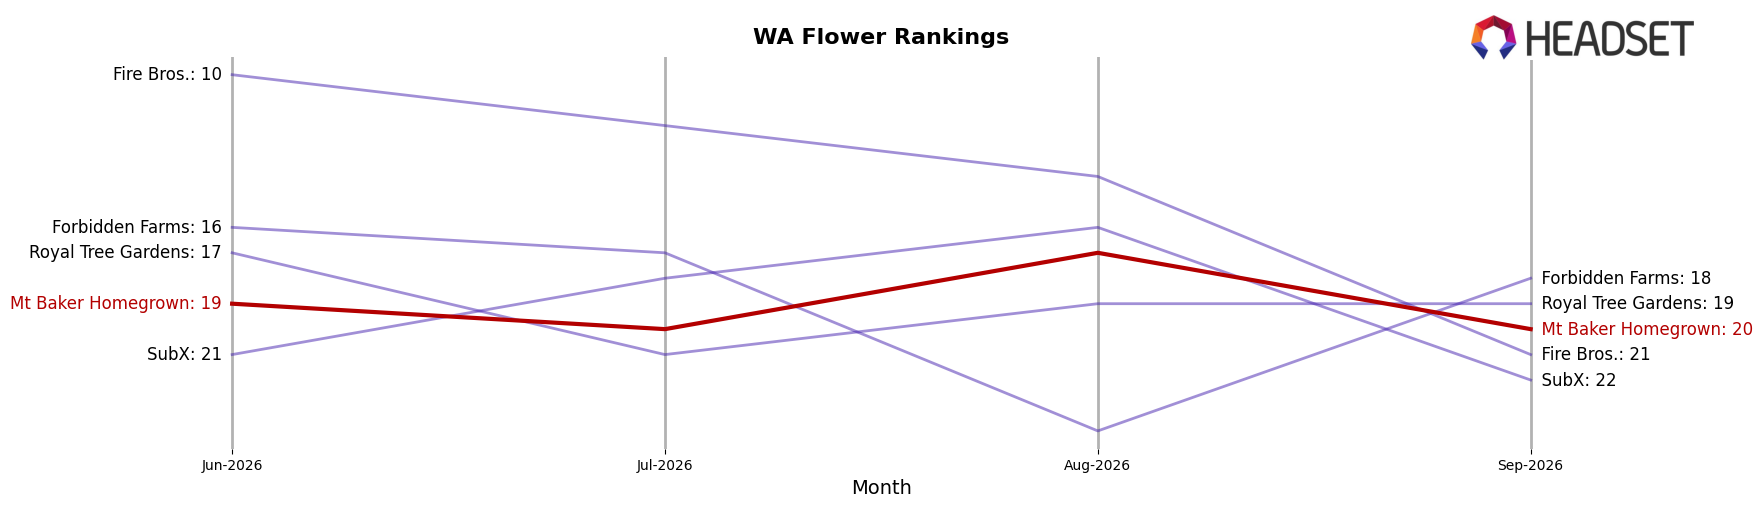
Mt Baker Homegrown sits at rank #20 in WA Flower for September 2026, improving 5 positions from #25 year over year, yet slipping 1 place from #19 in June 2026 after peaking at #17 in August 2026; meanwhile, Phat Panda held #1 with a 0-position YoY change while growing sales by 18.99%, and Hemp Kings vaulted from #24 to #5 with 105.09% YoY sales growth, indicating Mt Baker Homegrown’s mid-tier climb is being outpaced by top-end acceleration and late-entrant surges, which implies the current rank trajectory points to incremental gains that risk being capped unless velocity improves relative to fast-rising peers.
Notable Products
Gelato #33 (14g) posted the steepest decline in September 2026 with a -18.9% month-over-month drop while falling to rank 9, contrasting with Gelato 33 Pre-Roll 10-Pack (5g) at rank 4, which also slipped by -11.3%. Banana Jealousy Pre-Roll 10-Pack (5g) led the lineup at rank 1 and Banana Jealousy Pre-Roll 2-Pack (1g) followed at rank 2, placing two Banana Jealousy SKUs in the top two while at least eight of the top ten are Pre-Roll SKUs. The concentration of Pre-Rolls at 80% of top-ten slots alongside a double-digit Flower decline implies a pivot toward multi-pack Pre-Rolls as the commercial priority over larger-format Flower.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

