


Where to Buy
FINCA is stocked at 60 licensed dispensaries across New York, with the deepest coverage in New York, Queens, Staten Island, The Bronx, and Brooklyn. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
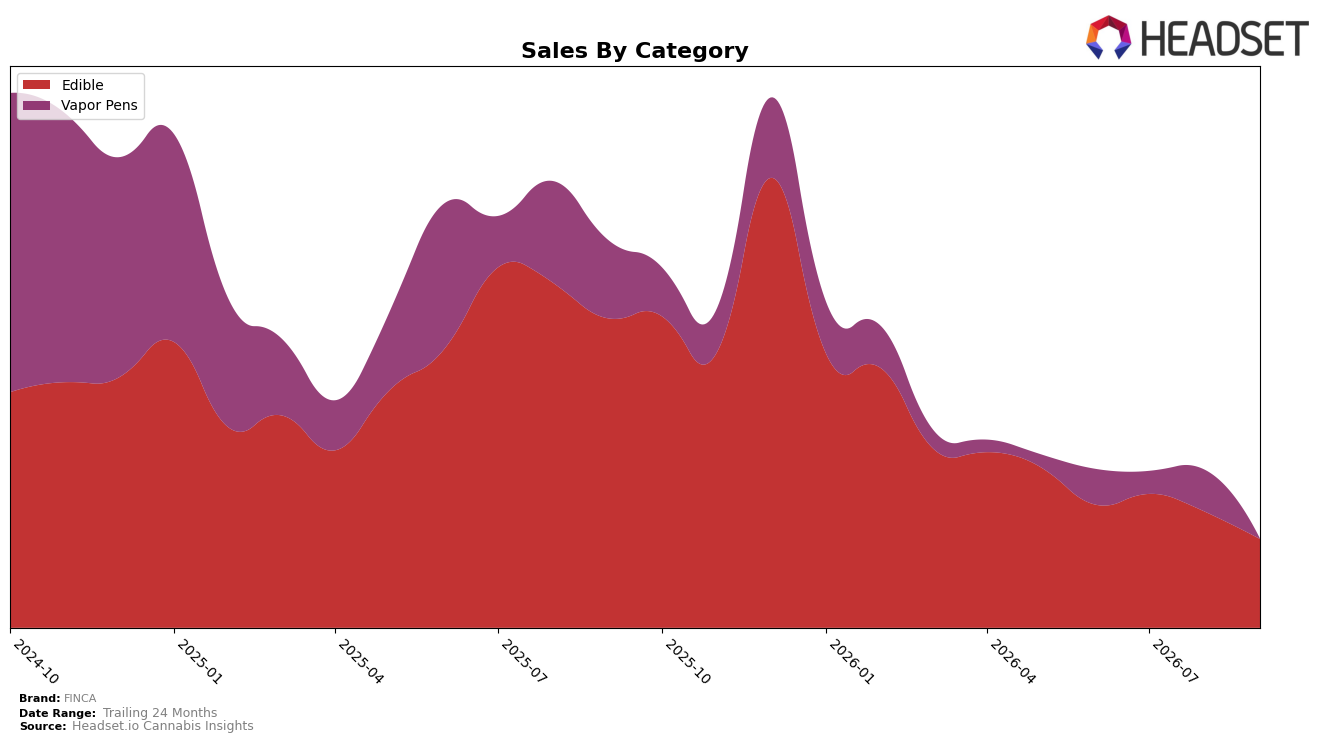
Edible holds 92.31% share in September 2026 with year-over-year down 69.59% and month-over-month down 22.16%, while Vapor Pens sits at 7.69% share with a 90.66% year-over-year decline and an 83.78% month-over-month drop. The average price is down 16.18% year-over-year to $25.13, with Edible priced at $24.14 and Vapor Pens at $49.71, and FINCA is ranked 45 in Edible in New York. This pattern implies FINCA is consolidating around lower-priced Edibles as Vapor Pens contract sharply, with the September 2026 mix skew creating exposure to category-specific demand softness and rank pressure in Edibles.
The steep month-over-month Vapor Pens contraction of 83.78% alongside a 22.16% Edible decline indicates a defensive tilt toward the larger Edible base rather than maintaining a two-category footprint, and the 16.18% year-over-year price decrease suggests trading down to protect volume against a 69.59% Edible year-over-year sales decline. With 92.31% of sales concentrated in Edibles but a rank of 45 in New York, FINCA’s positioning shifts toward a value-seeking Edible niche where price elasticity is being tested, implying that recovery hinges more on mix discipline and price-pack architecture than on Vapor Pen re-expansion.
Competitive Landscape
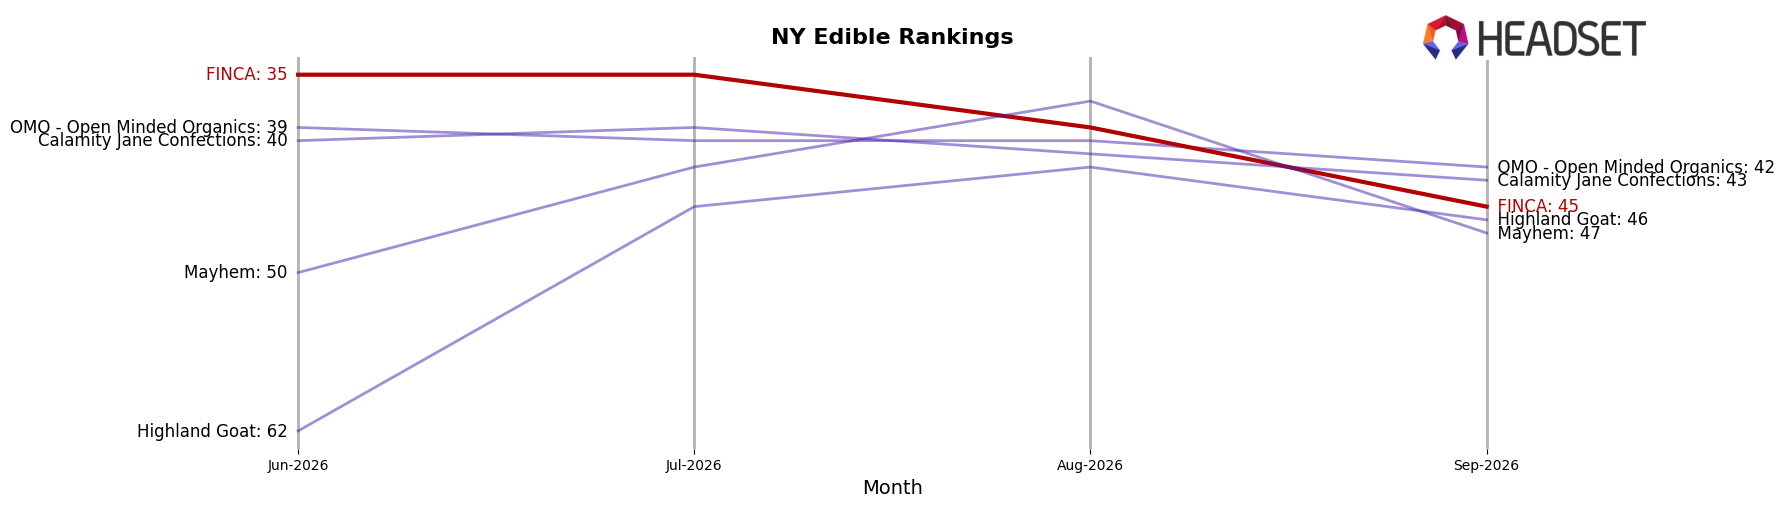
FINCA sits at rank #45 in NY Edible for September 2026, sliding 22 positions year over year from #23 and dropping 10 spots since June 2026 from #35, while its historical peak was #20 in July 2025; meanwhile, Camino climbed from #2 to #1 and Wyld improved from #3 to #2 with a 13.98% YoY sales lift, indicating FINCA’s relative share is being redistributed upward even as category leaders expand. Compared with Off Hours, which fell from #1 to #3 alongside a -28.14% YoY sales change, FINCA’s descent from #35 to #45 over three months contrasts with competitors that either advanced in rank or consolidated top-5 positions, and this divergence implies FINCA’s rank trajectory points to sustained mid-tier fade rather than a temporary fluctuation unless re-entry toward the #20–#30 band is re-established.
Notable Products
Siesta - CBN/THC 10:3 Guayaba Fresa Guava Strawberry Flavour Gummies 10-Pack (100mg THC, 30mg CBN) posted the largest movement in September 2026 with +79.6% MoM and climbed into rank 5 while the prior top duo slipped, as Buenos Dias - THC/THCv 2:1 Mandarin X Tangerine Flavour Energy Gummies 10-Pack (100mg THC, 50mg THCv) fell -19.8% at rank 3 and Fiesta - THC/CBG 1:1 Mango Pina Flavour Gummies 10-Pack (100mg THC, 100mg CBG) dropped -9.5% at rank 2. With four of the top five and eight of the top ten sitting in Edibles, the category concentration tightened even as the top-ranked Buenas Noches - THC/CBN 2:1 Agave Flavour Sleep Gummies 10-Pack (100mg THC, 50mg CBN) slid -8.4% at rank 1, implying mix shift within Edibles toward sleep and rest SKUs. The outlier contraction in Vapor Pens, where Super Sour Diesel Distillate Disposable (1g) plunged -83.7% to rank 9 on approximately $1.8k, contrasts with Edibles’ share of the leaderboard, indicating FINCA’s commercial direction is consolidating around functional gummy formats rather than inhalables.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

