

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
UpNorth Humboldt is stocked at 435 licensed dispensaries across California, Illinois, and Arizona, 292 of them in California, with the deepest coverage in San Francisco, Sacramento, Los Angeles, Fresno, and San Diego. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
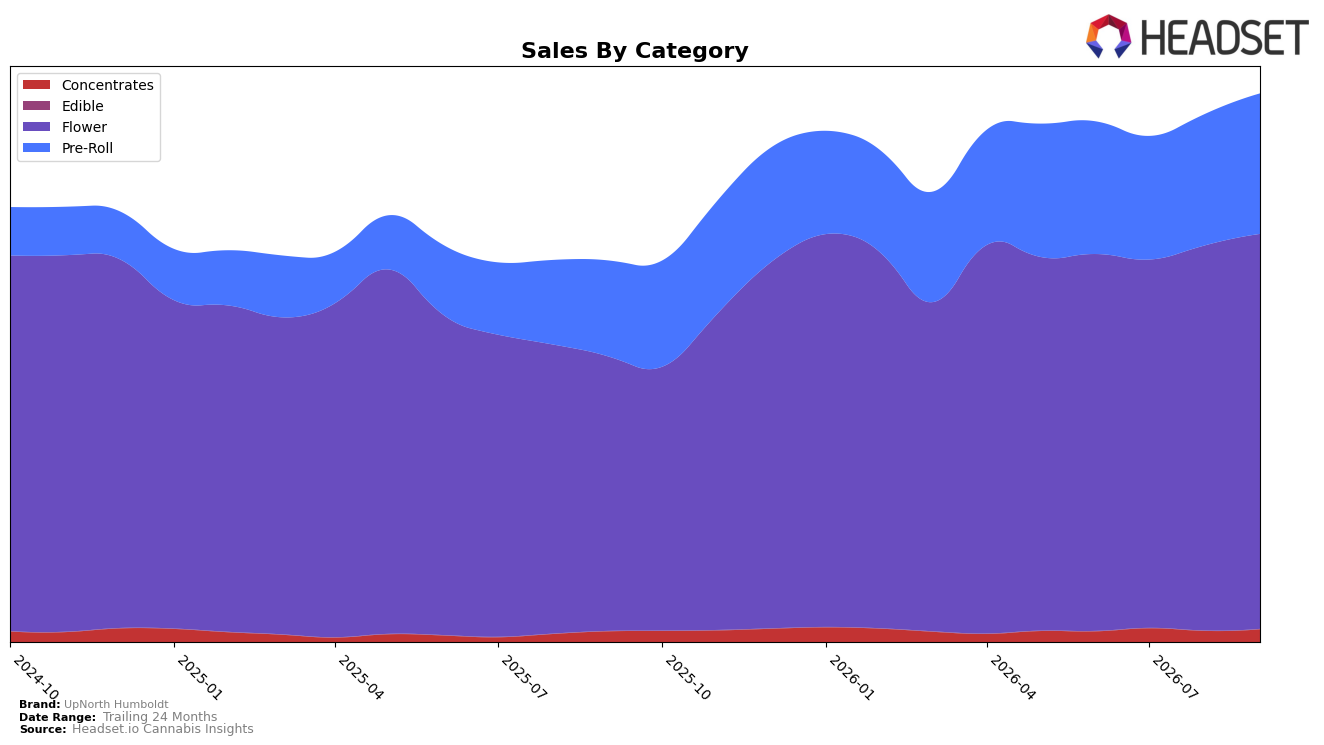
UpNorth Humboldt concentrated 72.06% of September 2026 sales in Flower with 43.96% year-over-year growth and a 2.58% month-over-month lift, while Pre-Roll held 25.60% share with 46.56% year-over-year and 6.97% month-over-month gains; Concentrates contributed 2.32% share with 18.86% year-over-year growth and 14.19% month-over-month growth, and Edible was 0.02% share with 27.92% year-over-year and 75.10% month-over-month spikes. Average price rose 3.70% year-over-year to $26.32 as Flower averaged $37.80 and Pre-Roll $14.08, indicating mix-led expansion alongside pricing stability; combined with a brand-level 43.91% year-over-year sales increase and an 8th-place Flower rank in California, the pattern implies the brand is leaning into volume growth in its core while seeding small but faster-moving niches that could hedge category concentration risk.
The shift shows positioning anchored in premiumized Flower depth (72.06% share, rank 8) with incremental reach from a faster-tilting Pre-Roll channel (6.97% month-over-month vs Flower’s 2.58%) and a nimble Concentrates uptick (14.19% month-over-month vs brand average price up 3.70% year-over-year). With Pre-Roll’s 46.56% year-over-year growth outpacing Flower’s 43.96% and Concentrates adding disproportionate month-over-month momentum off a 2.32% base, the mix implies an on-ramp strategy: defend Flower rank in California while allocating marginal inventory to Pre-Roll and Concentrates where elasticities convert to share gains without diluting average price.
Competitive Landscape
UpNorth Humboldt sits at rank #8 in California Flower in September 2026, improving 6 positions from #14 year over year, while holding flat versus June 2026 at #8; in contrast, STIIIZY moved from #2 to #1 with a 47.8% YoY sales increase and CannaBiotix (CBX) slipped from #1 to #3 alongside a 21.1% YoY sales decline, and Oakfruitland climbed from #11 to #5 with 73.5% YoY growth; this pattern—UpNorth Humboldt reaching a new peak rank of #8 in September 2026 yet not advancing quarter-over-quarter—implies the brand has broken into the top tier but must outpace faster risers to sustain upward movement.

Notable Products
The steepest movement in September 2026 is the decline for Sour Diesel (3.5g), down 25.1% MoM to $225,922 and sliding to rank 3, while Acapulco Gold (3.5g) fell 28.8% MoM at rank 8, signaling pressure within legacy Flower SKUs. In contrast, Durban Poison (3.5g) rose 7.0% MoM to hold rank 1 and Maui Wowie (3.5g) gained 20.5% MoM at rank 4, creating a split where winners are concentrated at the top while mid‑tier Flower weakens. Four of the top ten are Pre-Roll SKUs clustered at ranks 5–7 and 9–10 with no reported MoM shifts, indicating stability in format share even as Flower volatility drives the month’s outcome. The pattern implies UpNorth Humboldt is leaning on a narrowed set of flagship Flower strains for momentum while maintaining a steady Pre-Roll base, suggesting product strategy should rebalance exposure away from underperforming legacy Flower toward formats and strains showing sustained rank resilience.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

