

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Pleasantrees is stocked at 117 licensed dispensaries across Michigan, with the deepest coverage in Detroit, New Buffalo, Ann Arbor, Battle Creek, and Hazel Park. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
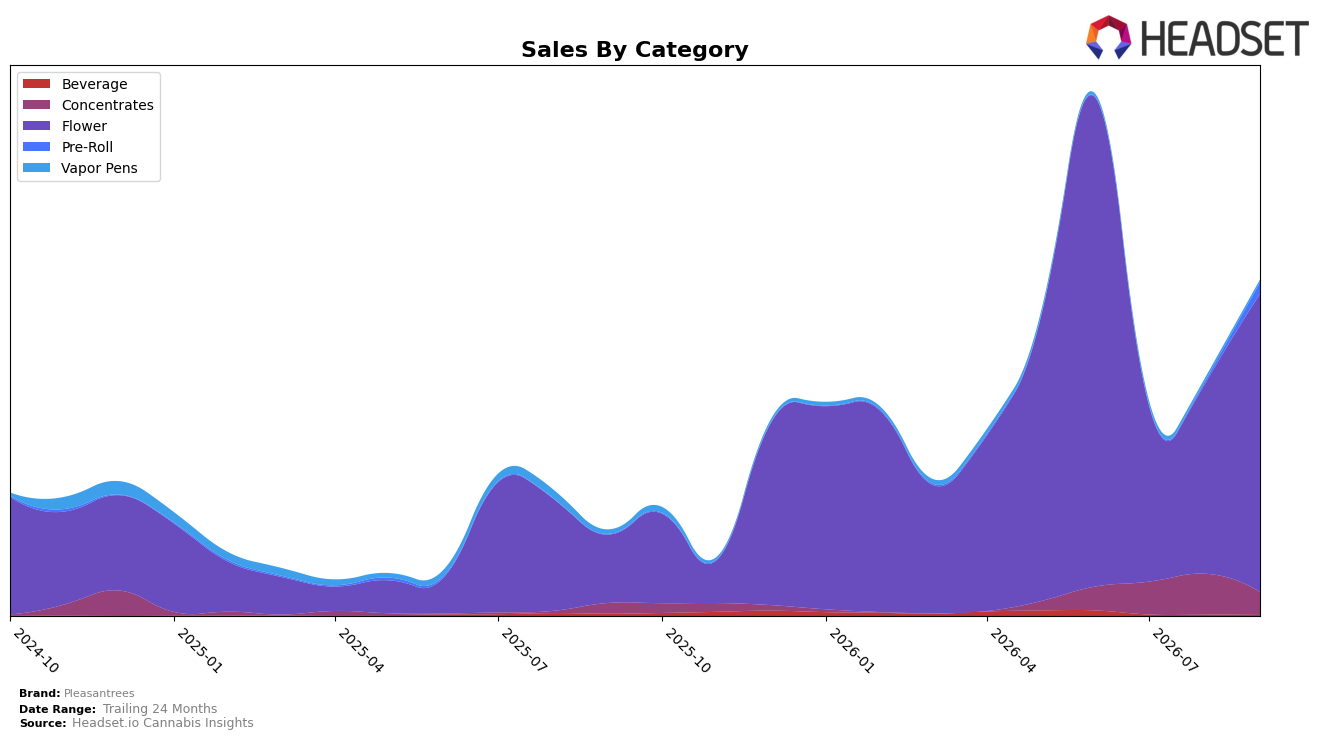
Pleasantrees concentrated 88.88% of September 2026 sales in Flower, with Flower up 337.85% year over year and 57.49% month over month, while the average price rose 89.70% YoY to $26.76, indicating mix and pricing both moved upward. Pre-Roll expanded share to 3.33% on 2,534.72% YoY growth and 408.40% MoM, while Concentrates held 6.78% share but fell 44.12% MoM despite 117.65% YoY growth; Vapor Pens and Beverage contracted with YoY declines of 39.36% and 59.50% and MoM drops of 14.96% and 23.43%. With Flower ranked 43rd in Michigan and commanding most of the mix, the pattern implies Pleasantrees is winning on core inhalables via aggressive Flower volume and price lifts, while niche formats are being deprioritized short term.
The surge in Pre-Roll (408.40% MoM alongside 2,534.72% YoY) paired with a 57.49% MoM jump in Flower suggests a deliberate shift toward fast-turn inhalables that scale quickly, whereas a 44.12% MoM pullback in Concentrates and double-digit MoM declines in Vapor Pens (14.96%) and Beverage (23.43%) point to tighter SKU focus. Given an 88.88% Flower share and a rank of 43 in Michigan Flower, the mix implies Pleasantrees is positioning as a value-to-mid price Flower and Pre-Roll player using price-led trade-up (average price +89.70% YoY) and mix expansion to build velocity, accepting lower presence in non-core categories to consolidate rank through depth rather than breadth.
Competitive Landscape
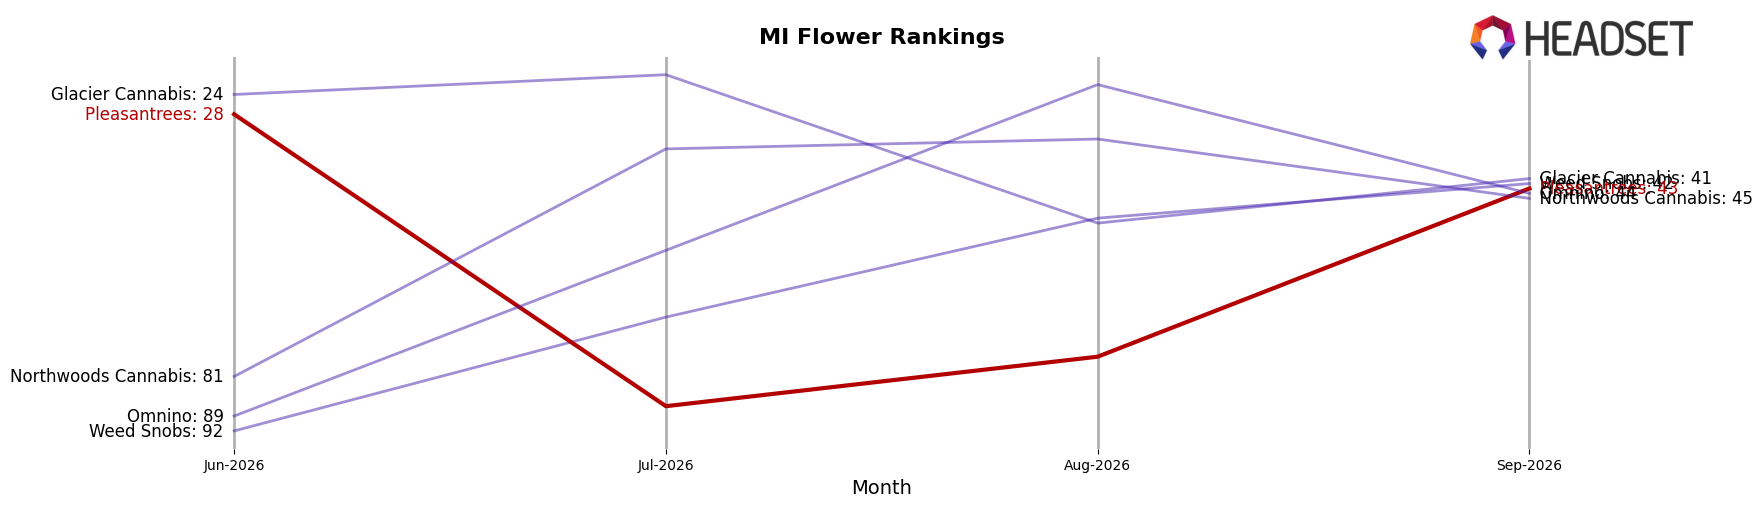
Pleasantrees sits at rank 43 in Michigan Flower for September 2026, a YoY climb of 135 positions from rank 178, while sliding 15 spots from rank 28 in June 2026 to rank 43 in September 2026. In the same window, High Minded held rank 1 year over year (1 to 1) despite a -3.3% YoY sales change, and Play Cannabis moved up from rank 7 to rank 2 with a 33.3% YoY sales increase, indicating competitors are consolidating top positions as Pleasantrees retreats from its June 2026 peak; the pattern implies Pleasantrees’ rapid YoY ascent has transitioned into mid-tier volatility that requires either sustained share capture or renewed velocity to reapproach its peak rank.
Notable Products
Traverse City Pie Smalls (7g) posted the steepest movement in September 2026 with a -30.9% month-over-month decline and slipped to rank 4, signaling demand erosion within a previously stable Smalls lane. Blue Zushi Smalls (Bulk) held rank 1 while Zlushiez (Bulk) sat at rank 2, creating a top-two bulk concentration even as Peanut Butter Gushers Smalls (1g) maintained rank 3, and the cluster of pre-ground 28g SKUs occupying ranks 5, 7, and 8 points to format-driven trade-down. With Flower accounting for all top-10 positions and at least three pre-ground 28g entries in the top eight, the assortment is consolidating around value-forward pack sizes rather than novel single grams, implying Pleasantrees will need to lean into bulk and pre-ground formats to defend share and margin mix.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

