

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Plus is stocked at 151 licensed dispensaries across California, with the deepest coverage in San Francisco, Los Angeles, San Jose, Sacramento, and San Diego. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
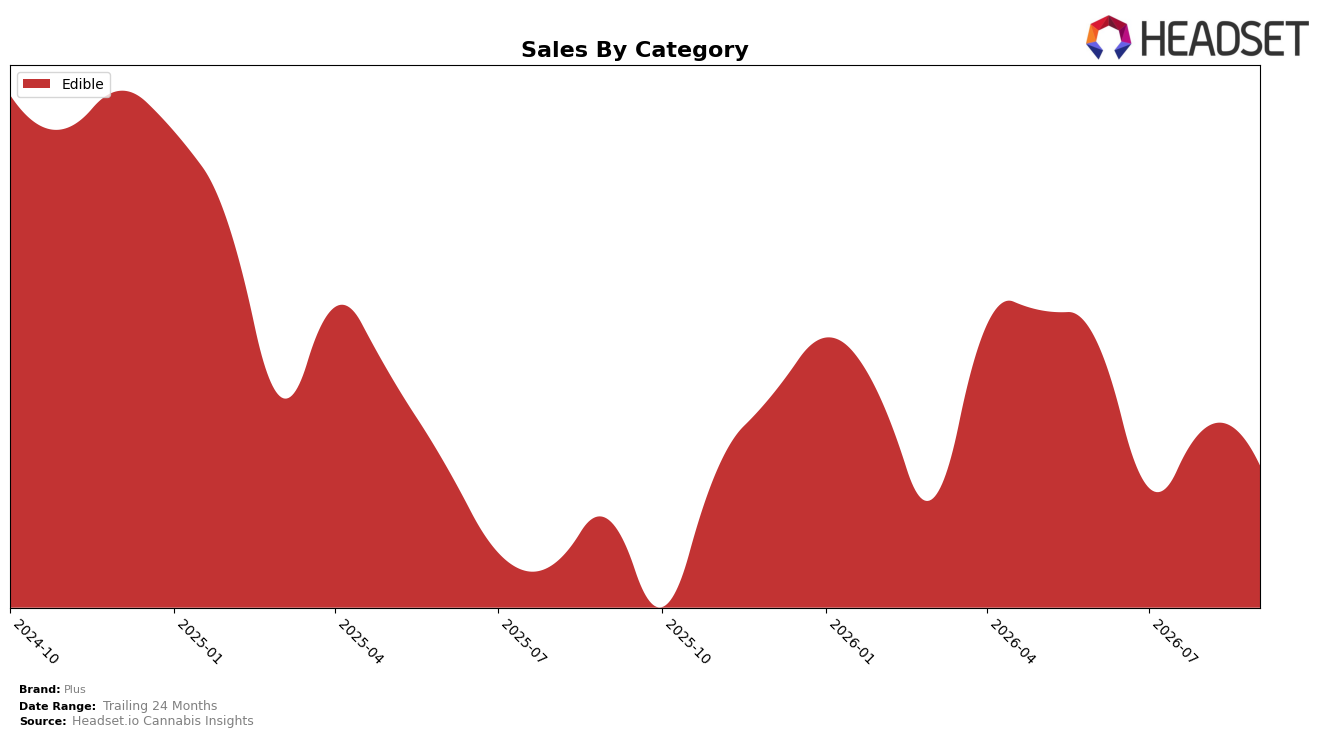
In September 2026, Plus operated as a single-category brand with Edible accounting for 100.0% of sales, posting a year-over-year change of 5.35% alongside a month-over-month decline of 3.36%. Average price fell 11.18% year over year while share within the mix remained concentrated at 100.0%, and the 24‑month sales change of -11.52% contrasts with the current 5.35% YoY lift. The pattern implies Plus is leaning on price elasticity within Edibles to offset longer-horizon contraction while accepting near-term volume softness, positioning the brand to trade price for share retention within a single-category footprint.
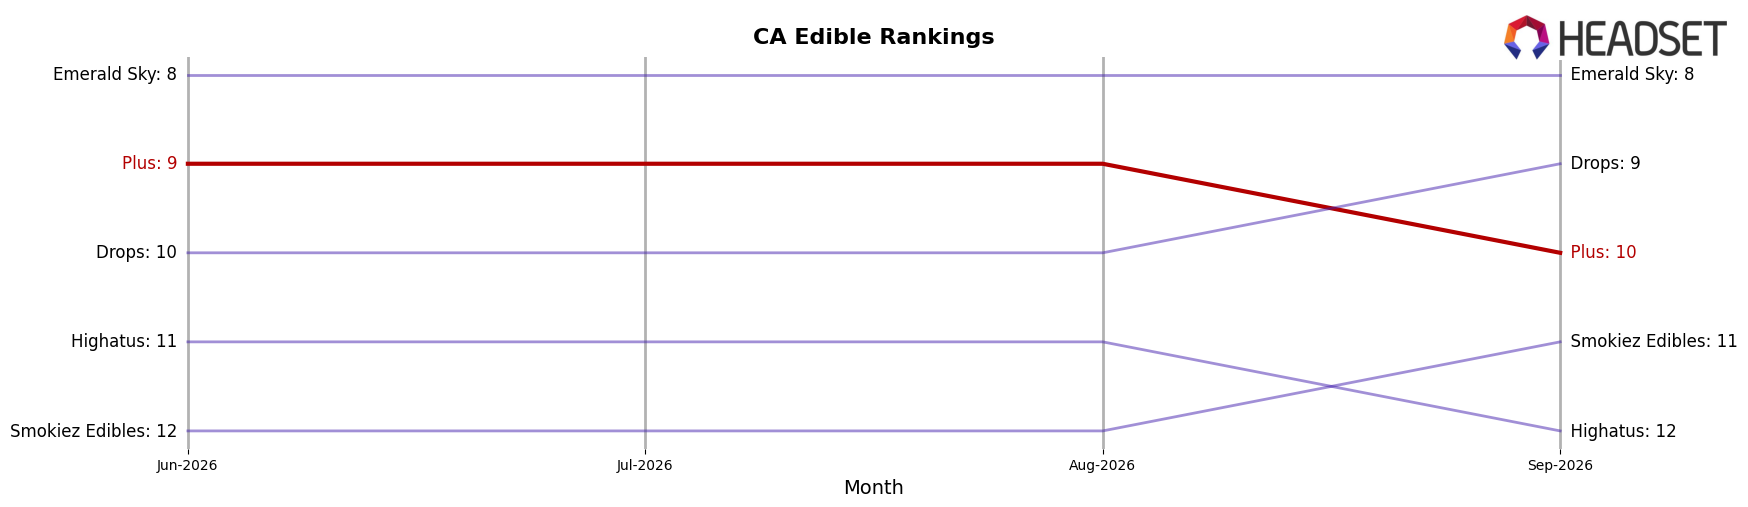
Within Edibles in California, Plus held rank 10 in September 2026, pairing a -3.36% MoM trend with a 5.35% YoY gain as average price declined 11.18%. The 24‑month decline of -11.52% against a current 100.0% category concentration and rank 10 signals a mid-pack position anchored to Edibles where price cuts support annual comp gains but do not lift monthly momentum. This implies Plus’s positioning is value-forward within Edibles, prioritizing price-driven accessibility to stabilize share at rank 10 rather than diversification or premiumization to climb the rankings.
Competitive Landscape
Plus sits at rank #10 in CA Edible in September 2026, improving 1 spot from #11 year over year but slipping 1 place from #9 three months ago, while its historic peak was #7 in October 2024; in contrast, Wyld held rank #1 with a 21.97% YoY sales decline and Camino remained #2 with a 10.39% YoY increase, indicating Plus is gaining ground against the category leader but losing relative momentum to a rising challenger. With Kanha / Sunderstorm steady at #3 alongside an 11.45% YoY sales lift and Lost Farm fixed at #4 despite a 0.56% YoY decline, the competitive stack is bifurcating between growers and decliners; Plus’s slight YoY rank improvement (+1) paired with a short-term dip (-1 versus June 2026) implies a stall near the edge of the top 10 unless it converts share from declining leaders rather than ceding pace to mid-pack climbers.
Notable Products
PLUS + CBD/THC 1:1 Raspberry Rosin Gummies 20-Pack (100mg CBD, 100mg THC) posted the steepest drop at -22.9% MoM and slid to rank 8, while PLUS Sleep - THC/CBD/CBN 5:1:1 Cloudberry Sleep Gummies 20-Pack (100mg THC, 20mg CBD, 20mg CBN) declined -14.5% to rank 4. In contrast, Sleep - THC/CBD/CBN 10:5:5 Midnight Berry Sleep Gummies 20-Pack (100mg THC, 50mg CBD, 50mg CBN) rose 9.6% MoM at rank 7, and Deep Sleep - CBN/CBD/THC 10:10:1 Elderberry Gummies 10-Pack (100mg CBN, 100mg CBD, 10mg THC) gained 6.7% at rank 5. Four of the top ten are Sleep formulations, and the top-ranked Deep Sleep - THC/CBD/CBN 1:1:1 Goodnight Cherry Gummies 10-Pack (100mg THC, 100mg CBD, 100mg CBN) held rank 1 with a -3.7% MoM dip and $241,940 in September 2026 sales. The mix points to sustained reliance on Sleep-led SKUs even as rosin-led general wellness softens, implying Plus should prioritize differentiated sleep ratios over broader 1:1 rosin extensions.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

