

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Pure Beauty is stocked at 284 licensed dispensaries across California and New York, 215 of them in California, with the deepest coverage in Los Angeles, San Francisco, San Diego, San Jose, and Sacramento. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
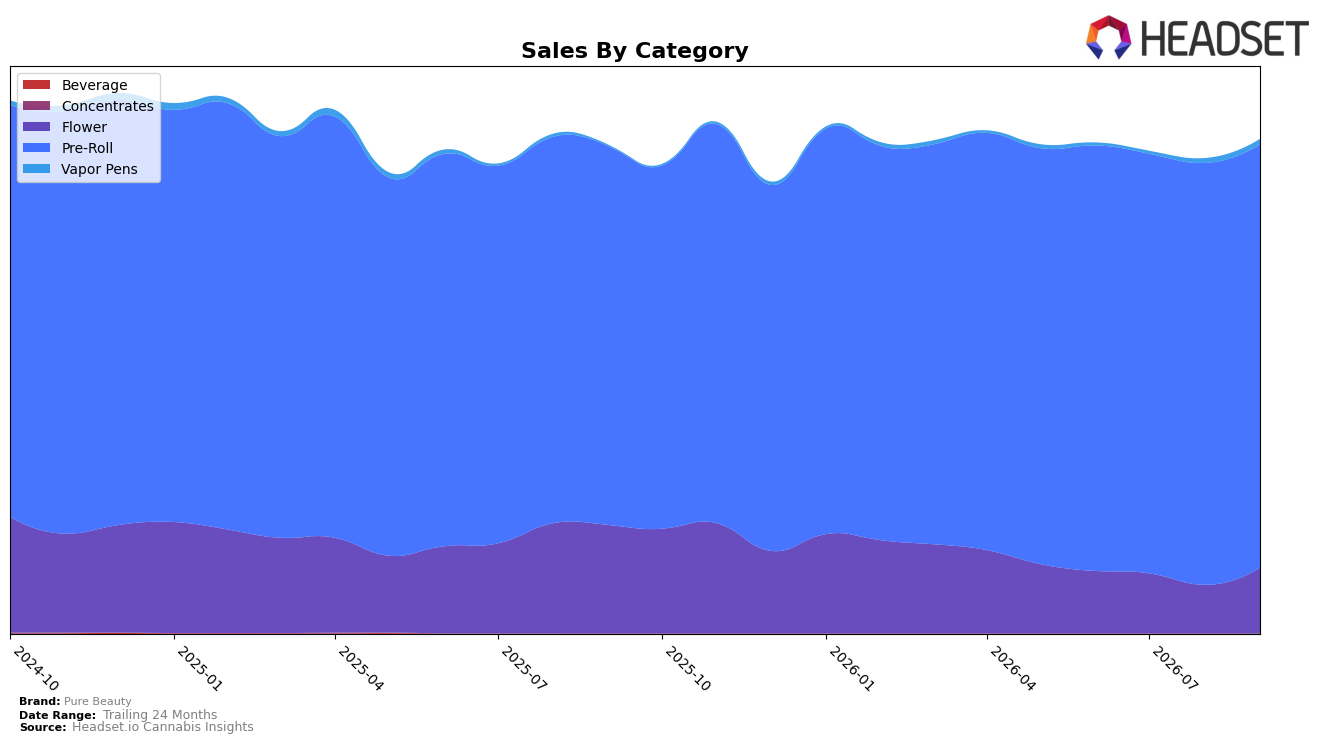
In September 2026, Pure Beauty concentrated 85.71% of sales in Pre-Roll with 11.70% year-over-year growth and a modest 0.33% month-over-month uptick, while Flower held 13.27% share with a -39.46% year-over-year decline but a 35.71% month-over-month rebound; Vapor Pens remained a small 1.02% share but expanded 409.45% year-over-year and 11.91% month-over-month. The brand’s average price fell 6.21% year-over-year to $35.82 as Pre-Roll averaged $35.63 and Flower $37.05, and within California Pre-Roll ranked 8th, indicating a scale position anchored in a single category but with early diversification signals from Vapor Pens. The pattern implies the portfolio is still Pre-Roll-led for September 2026, but price compression and a sharp Flower rebound alongside outsized Vapor Pens growth point to incremental mix widening rather than further concentration.
Given an 8th-place Pre-Roll rank in California and a 11.70% Pre-Roll year-over-year gain against a -39.46% Flower year-over-year drop, the brand’s competitive posture relies on defending Pre-Roll velocity while using the 35.71% month-over-month Flower recovery to re-enter value tiers shaped by a 6.21% brand-level price decrease. With Vapor Pens up 409.45% year-over-year but still 1.02% of mix, the near-term positioning opportunity is to leverage Pre-Roll scale to seed Vapor Pens distribution while managing Flower price-pack architecture; this suggests September 2026 is a pivot point where sustaining Pre-Roll rank and calibrating cross-category price ladders can convert category breadth into incremental share stability.
Competitive Landscape
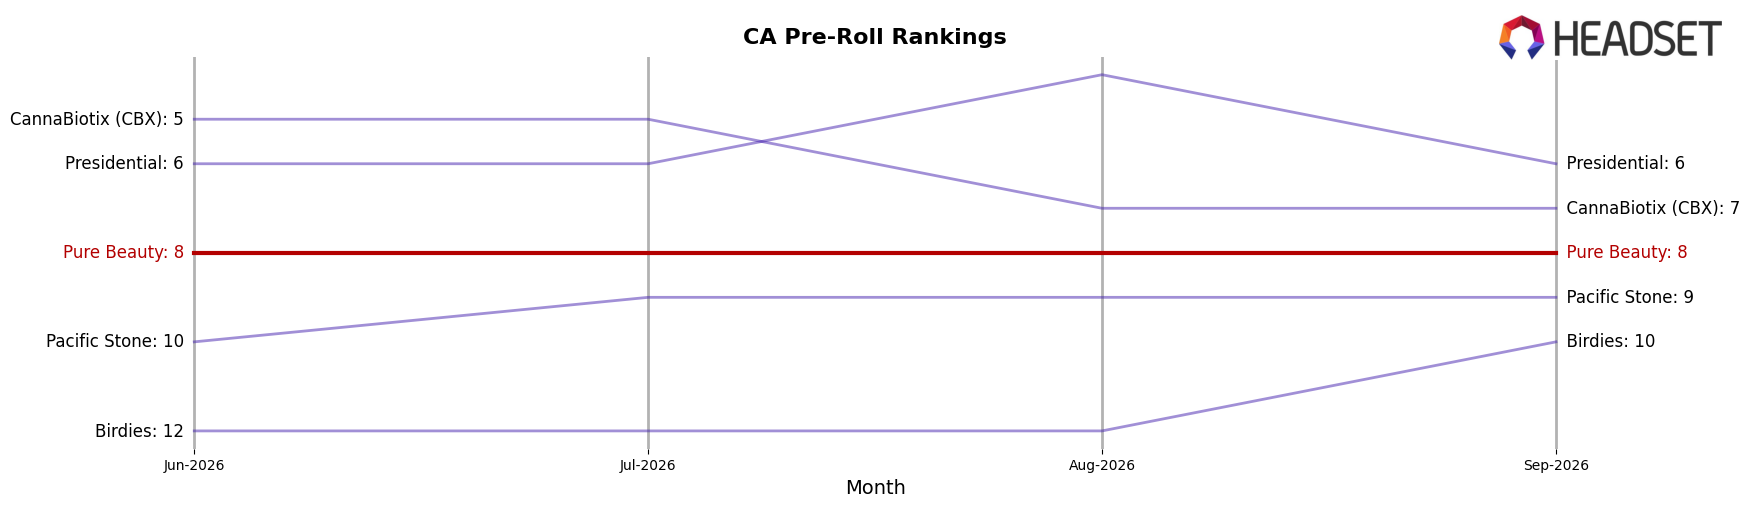
Pure Beauty sits at rank #8 in CA Pre-Roll for September 2026, improving 1 position YoY from #9, while holding flat versus three months ago at #8; this stability contrasts with Claybourne Co. rising from #6 to #4 and posting a 19.3% YoY sales gain, and Kingpen remaining #3 despite a 21.7% YoY sales decline, signaling that share is consolidating among leaders even as some see double-digit sales swings. Against category leaders, Jeeter held #1 with a 16.0% YoY increase and STIIIZY held #2 with a 15.6% YoY increase, while Pure Beauty’s peak rank of #6 in March 2025 and current plateau at #8 imply a ceiling just outside the top 5 unless momentum shifts.
Notable Products
Yellow Box - Sativa Blend Babies Solventless Infused Pre-Roll 5-Pack (2g) posted the standout move with +116.6% month over month and entered the top tier at rank 6, while Babies Pre-Roll 10-Pack (3.5g) fell -16.0% and slid to rank 7. Black Box Babies - Hybrid Blend Mini Pre-Roll 10-Pack (3.5g) held rank 1 with a modest +2.1% MoM versus Pink Box Babies - Indica Blend Mini Pre-Roll 10-Pack (3.5g) at rank 3 with +6.4% MoM, and five different Mini Pre-Roll 10-Packs occupy ranks 1 through 5 even as Orange Box - THCV Mini Pre-Roll 10-Pack (3.5g) dropped -21.4% at rank 8. With nine of the top ten in Pre-Roll and the sole Flower entry Bolinas (3.5g) only at rank 10 and $30,294 in September 2026, the mix implies near-term emphasis on differentiated Pre-Roll formats—especially infused variants—over expanding traditional Flower.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

