


Market Insights Snapshot
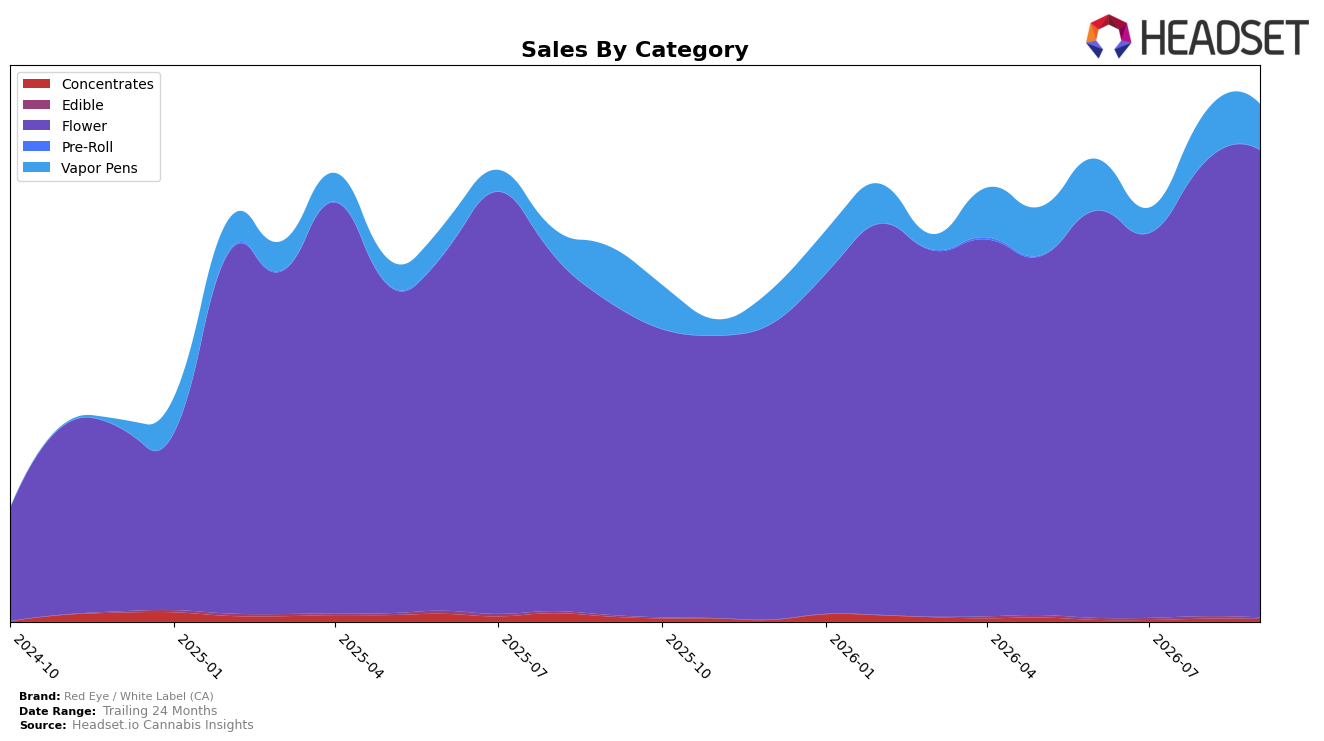
In September 2026, Red Eye / White Label (CA) concentrated 90.48% of sales in Flower with year-over-year growth of 49.29% and month-over-month expansion of 3.00%, while Vapor Pens held 8.82% share with a 17.06% YoY decline and a 6.31% MoM drop. Smaller lines compressed further: Concentrates fell 49.44% YoY and 7.98% MoM to 0.49% share, and Edible contracted 12.31% YoY and 48.06% MoM to 0.21% share. Average price rose 17.21% YoY to $22.25 alongside brand sales growth of 38.03% YoY, and within the core, Flower pricing averaged 25.13. The pattern implies a deliberate tilt toward higher-priced Flower as the growth engine while peripheral categories are being deprioritized, consolidating the mix around a single category that aligns with the brand’s rank of 30 in Flower in California.
These mix shifts indicate the brand is trading up on core Flower while allowing non-core categories to contract, with Flower’s 90.48% share and 49.29% YoY growth outpacing the overall 38.03% YoY brand increase, and the 3.00% MoM in Flower cushioning the 6.31% MoM decline in Vapor Pens. The widening gap between Flower and Vapor Pens, now 81.66 percentage points of share with opposing YoY trajectories (+49.29% vs. −17.06%), positions the brand as a Flower-first player rather than a balanced multi-category portfolio. This concentration, paired with a 17.21% YoY price lift and a Flower rank of 30 in California, implies the path to further gains depends on deepening Flower penetration and price-pack architecture, not near-term recovery in sub-scale categories.
Competitive Landscape
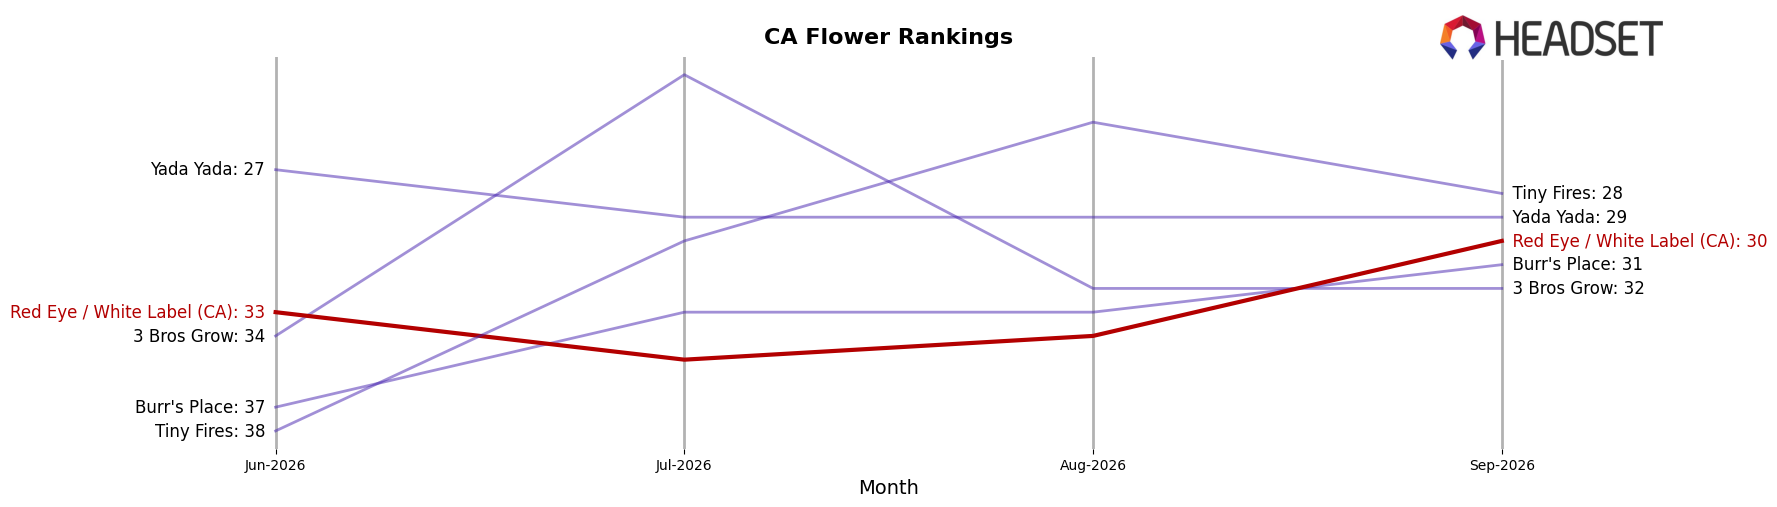
Red Eye / White Label (CA) ranks #30 in California Flower in September 2026, improving 12 positions from #42 year over year, and edging up 3 spots from #33 in June 2026; this new #30 also marks its peak-to-date. In the same period, STIIIZY rose from #2 to #1 with 47.8% year-over-year sales growth while CannaBiotix (CBX) slipped from #1 to #3 alongside a 21.1% sales decline, indicating Red Eye / White Label (CA) is gaining relative position as leadership at the top reshuffles and momentum concentrates among climbers.
Notable Products
Cheetah Piss (3.5g) had the steepest movement in September 2026 with a -23.5% month-over-month drop while sliding to rank 6, contrasting with Oklahoma Coma (14g) at rank 5, which dipped a milder -4.9% MoM. Flower occupied 8 of the top 10 ranks, with three large-size Flower packs at ranks 2, 3, and 7 anchoring share, indicating a tilt toward higher-volume formats even as smaller 3.5g units lose velocity. Grease Monkey x Triple OG (3.5g) held rank 1 despite limited MoM context, suggesting unit-led leadership coexists with bulk-pack momentum that consolidates revenue at the upper ranks. The pattern implies Red Eye / White Label (CA) is concentrating demand into bulk Flower while culling underperforming 3.5g SKUs, orienting the mix toward fewer, higher-throughput formats over breadth.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

