

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Redbird (formerly The Virginia Company) is stocked at 168 licensed dispensaries across Washington and Oklahoma, 131 of them in Washington, with the deepest coverage in Seattle, Tacoma, Vancouver, Spokane, and Olympia. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
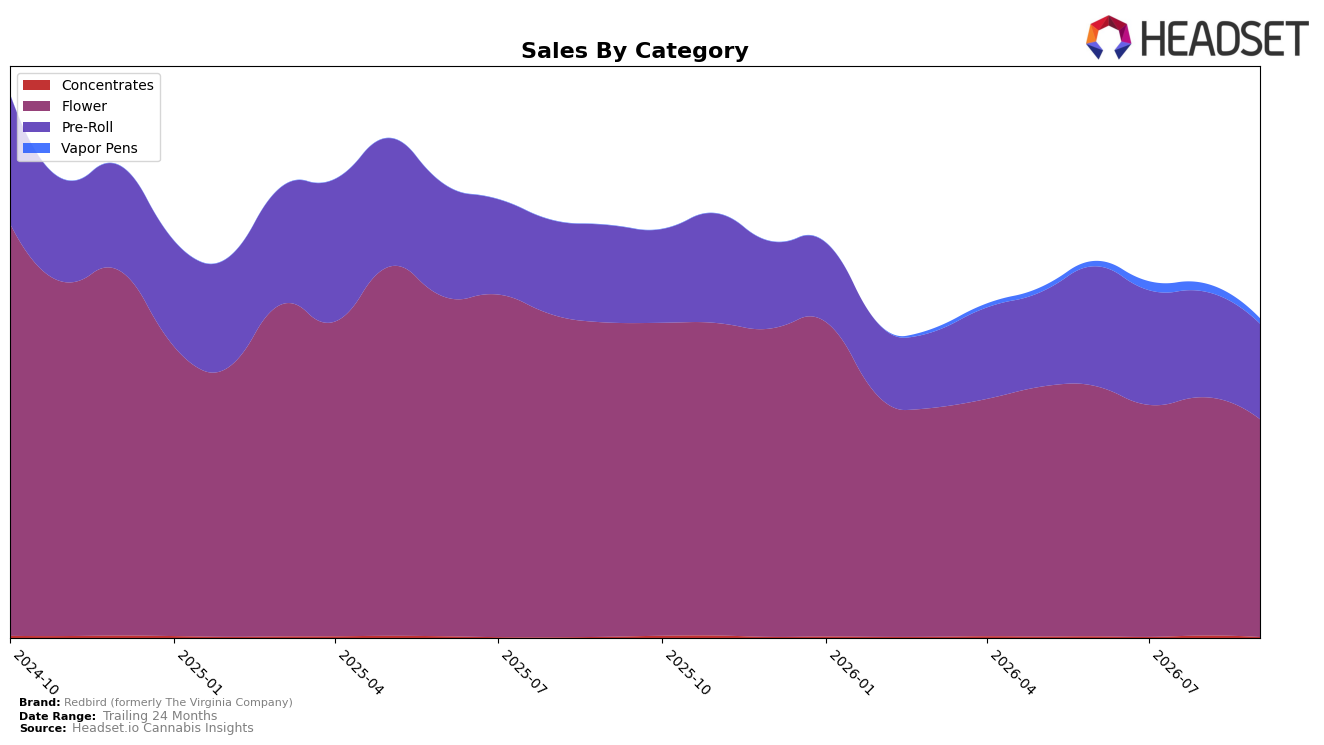
In September 2026, Redbird (formerly The Virginia Company) concentrated 68.23% of sales in Flower while Pre-Roll held 29.87%, with Vapor Pens and Concentrates together at 1.91%, indicating a tighter two-category core. Flower contracted 30.72% year over year and 8.62% month over month, while Pre-Roll slipped just 1.98% year over year but fell 9.65% month over month, and Vapor Pens and Concentrates declined 35.64% and 59.98% month over month respectively. With brand-wide sales down 22.69% year over year and average price down 20.60%, and Flower ranked 13 in Washington, the pattern implies reliance on Flower that is underpricing to protect share but not preventing volume loss, while Pre-Roll mitigates some volatility without offsetting the broader retreat.
The shift toward a 98.09% split between Flower and Pre-Roll, alongside a 31.27% two-year sales decline and a 20.60% average price drop, implies a value-led positioning anchored in Flower where rank 13 limits visibility and pricing power. With Flower’s deeper year-over-year contraction than the brand overall (-30.72% vs. -22.69%) and Pre-Roll’s comparatively minor year-over-year dip (-1.98%) but sharper month-over-month pullback (-9.65%), the mix suggests a defensive trade-down strategy that stabilizes near-term unit mix but compresses margins and constrains premium-line expansion; to regain trajectory, the brand’s positioning would need to pivot Pre-Roll from volume ballast to gateway, while arresting Flower share erosion within Washington.
Competitive Landscape
Redbird (formerly The Virginia Company) sits at rank #13 in Washington Flower in September 2026, down 8 positions from #5 year over year and 5 spots from #8 in June 2026, after previously peaking at #4 in January 2026; meanwhile, Phat Panda holds #1 with a 18.99% YoY sales increase and Hemp Kings surged from #24 to #5 on 105.09% YoY growth, indicating that Redbird’s relative share is being pressured as faster-rising rivals consolidate top-tier ranks and that its recent downward rank trajectory implies a need to counter accelerating gains from competitors to avoid further share erosion.

Notable Products
Chocolate Bars (3.5g) posted the steepest pullback in September 2026 with a -10.1% MoM slide while sitting at rank 7, contrasting with GMO (3.5g) up 30.2% MoM at rank 1. Blueberry Haze (3.5g) added 13.7% MoM at rank 2, and five of the top ten are Flower SKUs concentrated in 3.5g formats, indicating buyers are consolidating around core eighths even as one legacy Flower SKU turns negative. GMO (3.5g) also anchored category dollars at $28,855, while GMO Pre-Roll (1g) dipped -5.3% at rank 10, signaling format preference is tilting toward eighths over single pre-rolls. The pattern implies Redbird (formerly The Virginia Company) is pivoting toward a Flower-led mix where momentum is concentrated at the top, making portfolio pruning around underperforming Flower and single-stick Pre-Rolls the near-term route to protect rank and share.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

