

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
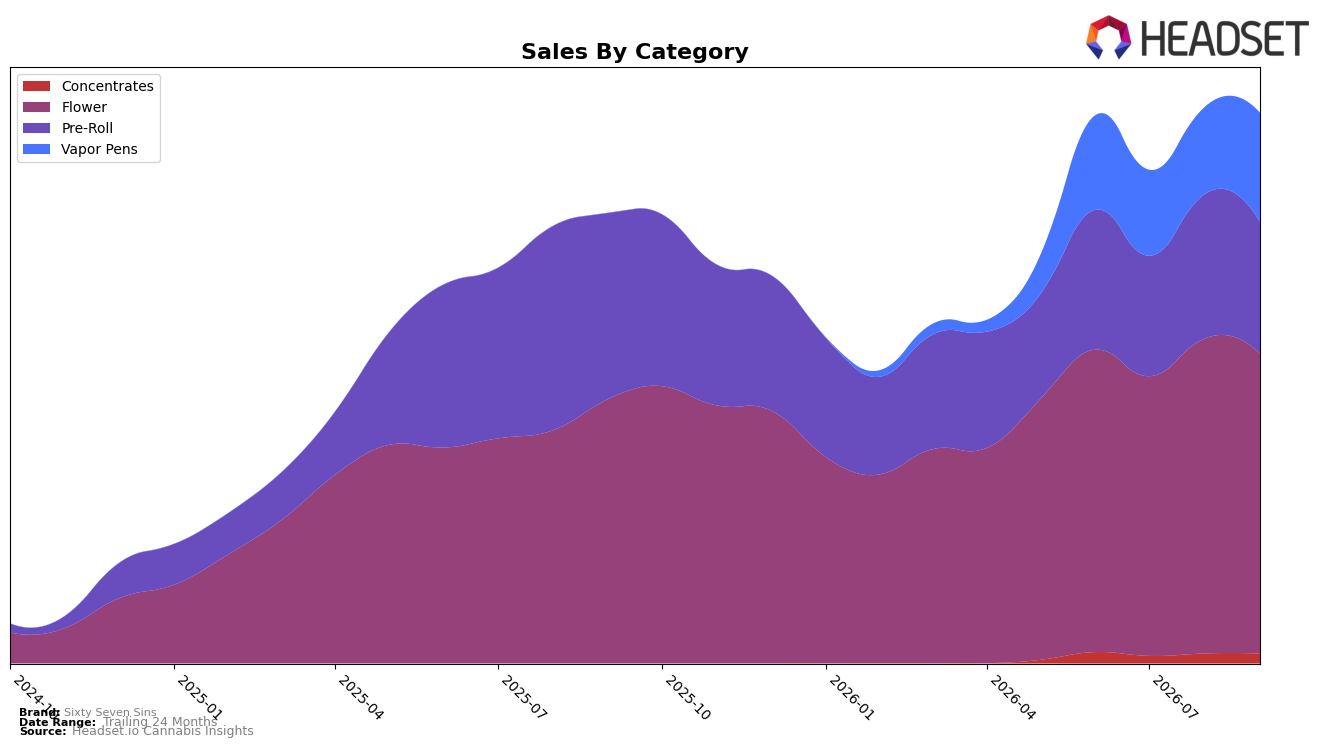
Sixty Seven Sins concentrated 54.54% share in Flower with 13.62% YoY growth while rank sat at 18 in Flower in Ontario, and Pre-Roll held 23.89% share with a -29.36% YoY decline; meanwhile Vapor Pens reached 19.83% share with a 25.31% MoM increase and Concentrates were 1.74% share with a -1.50% MoM dip. Despite a -4.71% MoM contraction in Flower and an -8.84% MoM drop in Pre-Roll, total brand sales rose 22.22% YoY alongside a -10.66% YoY move in average price, implying volume expansion concentrated in higher-share Flower while Vapor Pens provided the only MoM tailwind among non-Flower formats.
The mix shift toward Vapor Pens’ 25.31% MoM growth alongside Flower’s 54.54% share and rank 18 in Ontario suggests a portfolio balancing act: defending Flower scale while using Vape momentum to offset Pre-Roll’s -29.36% YoY slide and -8.84% MoM pressure. With a -10.66% YoY price decrease against a 22.22% YoY sales lift and Flower’s -4.71% MoM softness, the brand’s positioning tilts toward value-led volume in Flower plus incremental penetration in Vapor Pens, implying near-term gains will come from sustaining Vape velocity and stabilizing Pre-Roll to reduce dependence on a single category rank position.
Competitive Landscape
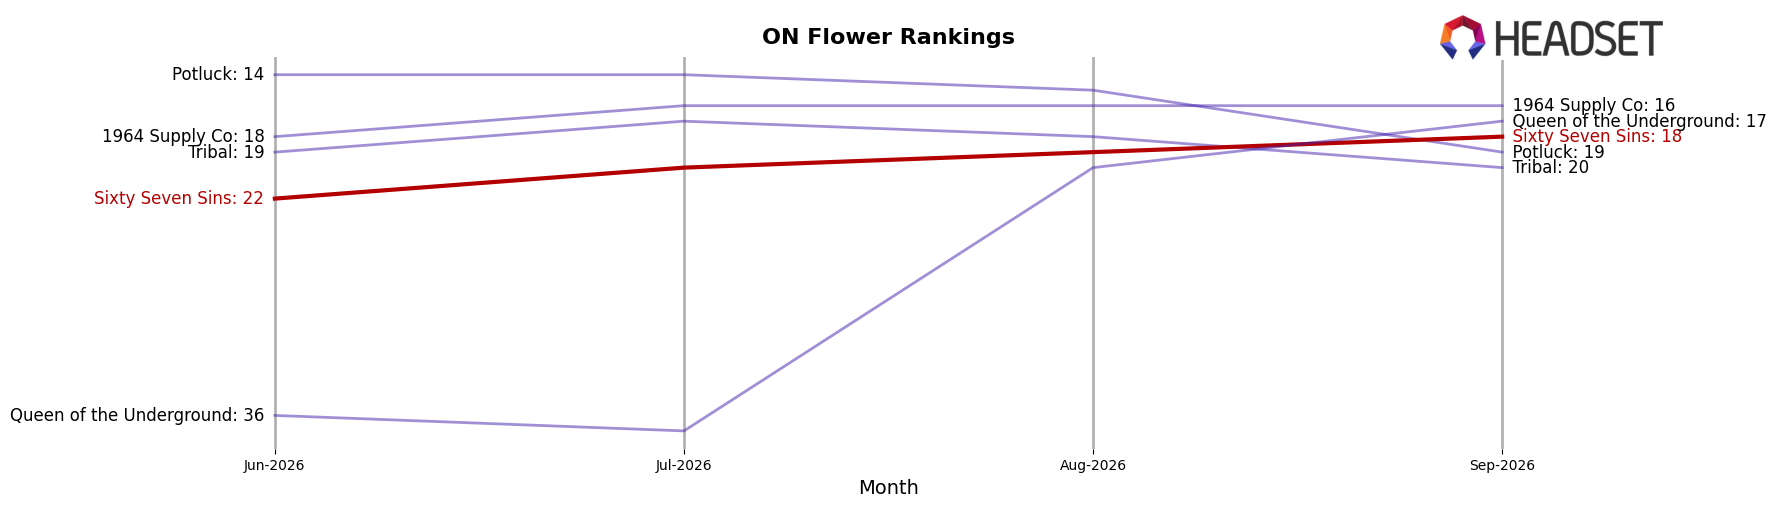
Sixty Seven Sins sits at rank #18 in ON Flower in September 2026, improving 5 positions from #23 year over year, while also moving up 4 spots from #22 in June 2026 to its peak at #18 in September 2026; in contrast, Spinach advanced from #3 to #1 with a 15.7% YoY sales increase and FIGR jumped from #14 to #5 on 51.7% YoY sales growth. Meanwhile, Back Forty / Back 40 Cannabis slid from #1 to #3 alongside a -7.4% YoY sales change and Shred held steady at #2 with 13.4% YoY sales growth, indicating that Sixty Seven Sins’ climb into the top-20 reflects share being contested more by upwardly mobile mid-pack brands than by the entrenched top-two, implying a trajectory that can continue if it captures volatility among ranks #5–#15.
Notable Products
67 Reserve Pre-Roll (1g) posted the steepest movement in September 2026 with a -25.9% MoM drop while slipping to rank 5, whereas Gas Face (3.5g) fell -16.5% MoM but retained rank 1. Gas Face Cured Resin Disposable (1g) in Vapor Pens rose +5.9% MoM at rank 2, contrasting with a -2.6% MoM dip for Gas Face Infused Pre-Roll (1g) at rank 3. With four of the top ten positioned in Flower and three in Pre-Roll, the skew toward inhalables concentrates mix risk in two inhalation formats, implying the brand is leaning into high-velocity Flower leadership supported by selective Vapor Pens momentum rather than broad format diversification.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

