


Where to Buy
SmartBud is stocked at 127 licensed dispensaries across New York, with the deepest coverage in New York, Brooklyn, Queens, The Bronx, and Staten Island. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
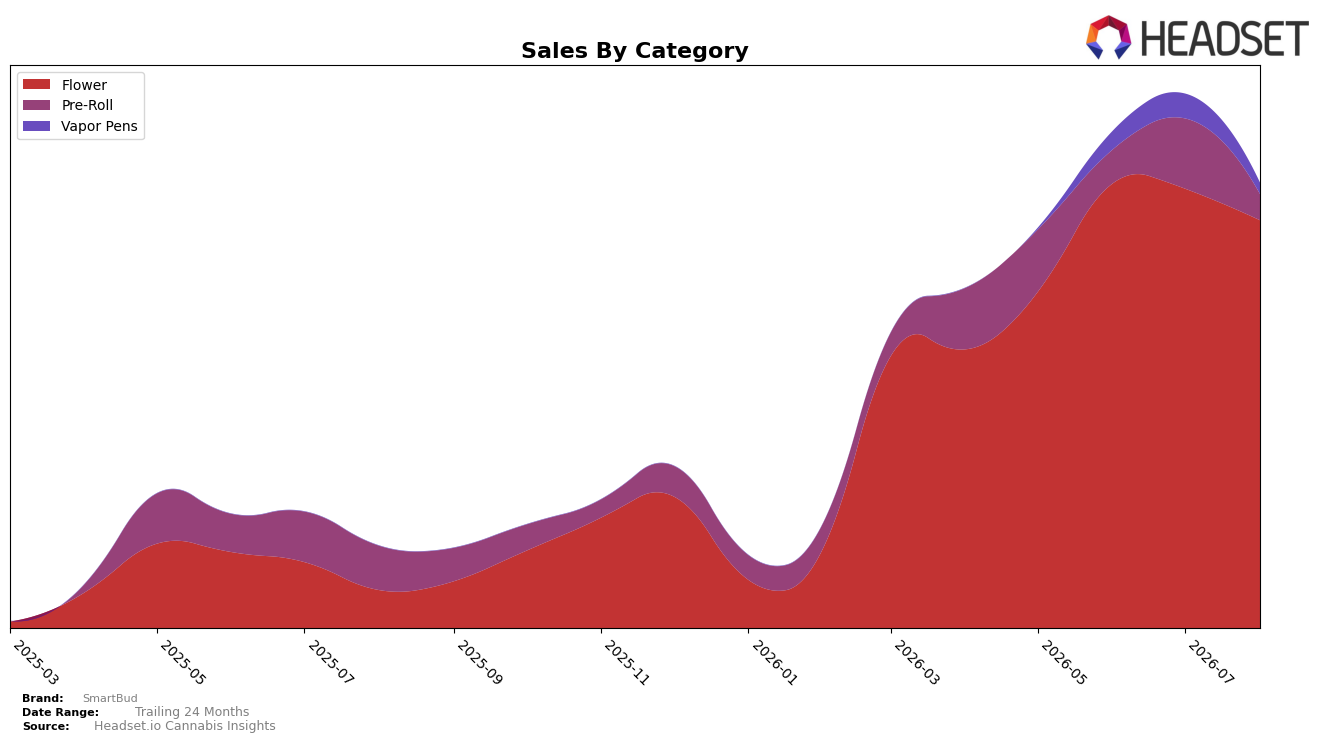
SmartBud concentrated 91.70% of August 2026 sales in Flower, where year-over-year growth reached 985.99% while month-over-month declined 7.18%; Pre-Roll held 5.80% share with a 41.31% YoY decline and a 63.11% MoM drop, and Vapor Pens accounted for 2.50% share with a 54.61% MoM decline and no YoY comp. Average price rose 39.55% YoY to $39.69 as Flower’s average price sat at $44.51, contrasting with Pre-Roll at $14.98; this skew, combined with a 445.63% brand-level YoY sales increase and a rank of 25 in Flower in New York, implies SmartBud’s momentum is narrowly anchored in higher-priced Flower despite broad MoM pullbacks across smaller formats.
The steep MoM contractions in Pre-Roll (down 63.11%) and Vapor Pens (down 54.61%), alongside Flower’s smaller 7.18% MoM dip and 91.70% mix weight, indicate a portfolio over-reliant on one category for scale and pricing power; the 985.99% YoY surge in Flower versus a 41.31% YoY decline in Pre-Roll suggests channel and assortment choices are reinforcing that single-cylinder model. With August 2026 average prices up 39.55% YoY and Flower positioned at a premium to the brand average ($44.51 vs. $39.69), holding a Flower rank of 25 in New York implies the path to improved placement runs through defending Flower share while selectively rebuilding Pre-Roll and Vapor Pens to reduce volatility.
Competitive Landscape
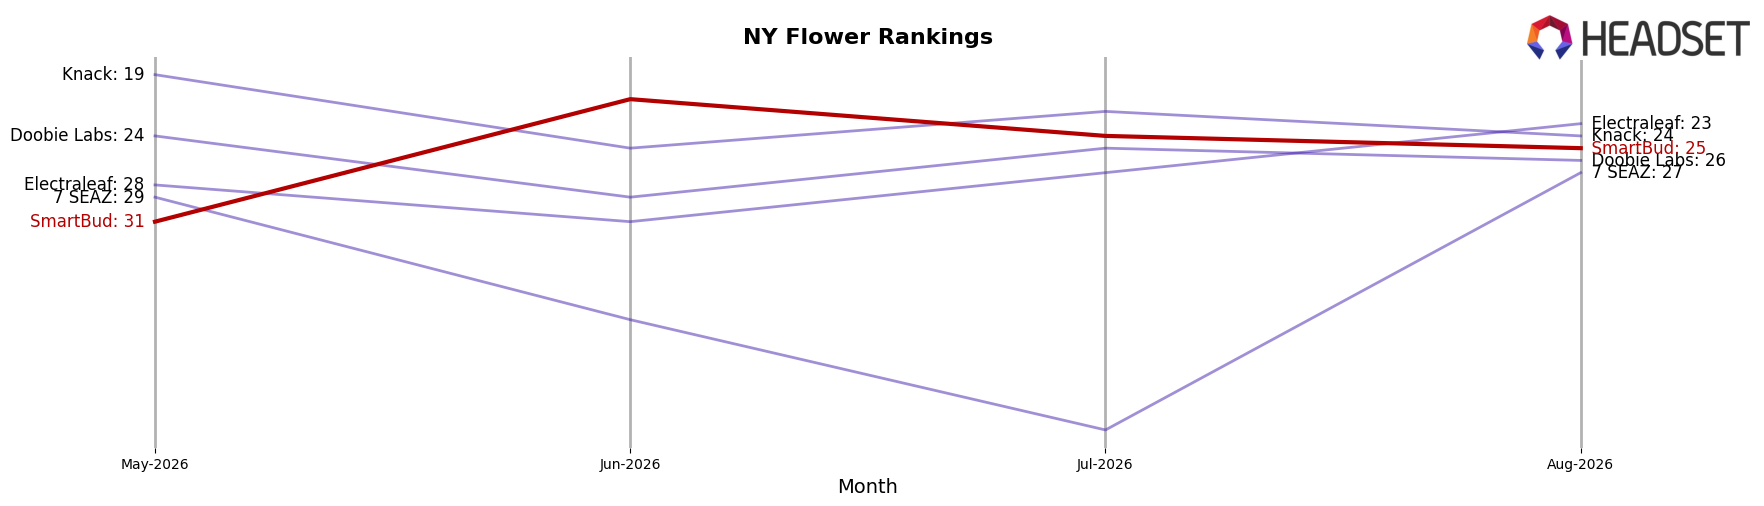
SmartBud sits at rank #25 in NY Flower for August 2026, a 99-position climb from #124 year over year, while moving up 6 spots from #31 in May 2026 and still 4 positions shy of its peak at #21 in June 2026; in contrast, Find. advanced from #6 to #1 and Rolling Green Cannabis slid from #2 to #5 with a -36.1% sales change YoY. With top rivals like Leal shifting from #7 to #2 and Grassroots jumping from #14 to #4 alongside an 88.4% YoY sales increase, SmartBud’s rise into the mid-20s suggests momentum is improving but headroom to re-enter the low-20s or teens will depend on converting the June 2026 peak into sustained share gains amid faster-moving leaders.
Notable Products
Girl Scout Cookies (3.5g) posted the steepest decline at -35.6% MoM while sitting at rank 5 in August 2026, and Double Blue Dream Pre-ground (14g) also fell -27.5% to rank 8. Despite these drops, Strawberry Cough Pre Ground (14g) holds rank 1 and Wedding Cake Pre-Ground (14g) sits at rank 2, indicating the brand’s leadership is concentrated at the top of the ranking table. With eight of the top ten SKUs in Flower and only one Pre-Roll at rank 9 declining -32.3%, the sales mix is consolidating around large-format Flower rather than smaller units. This pattern implies SmartBud is leaning into higher-quantity Flower formats for volume, even as select 3.5g and Pre-Roll offerings retrench.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

