

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
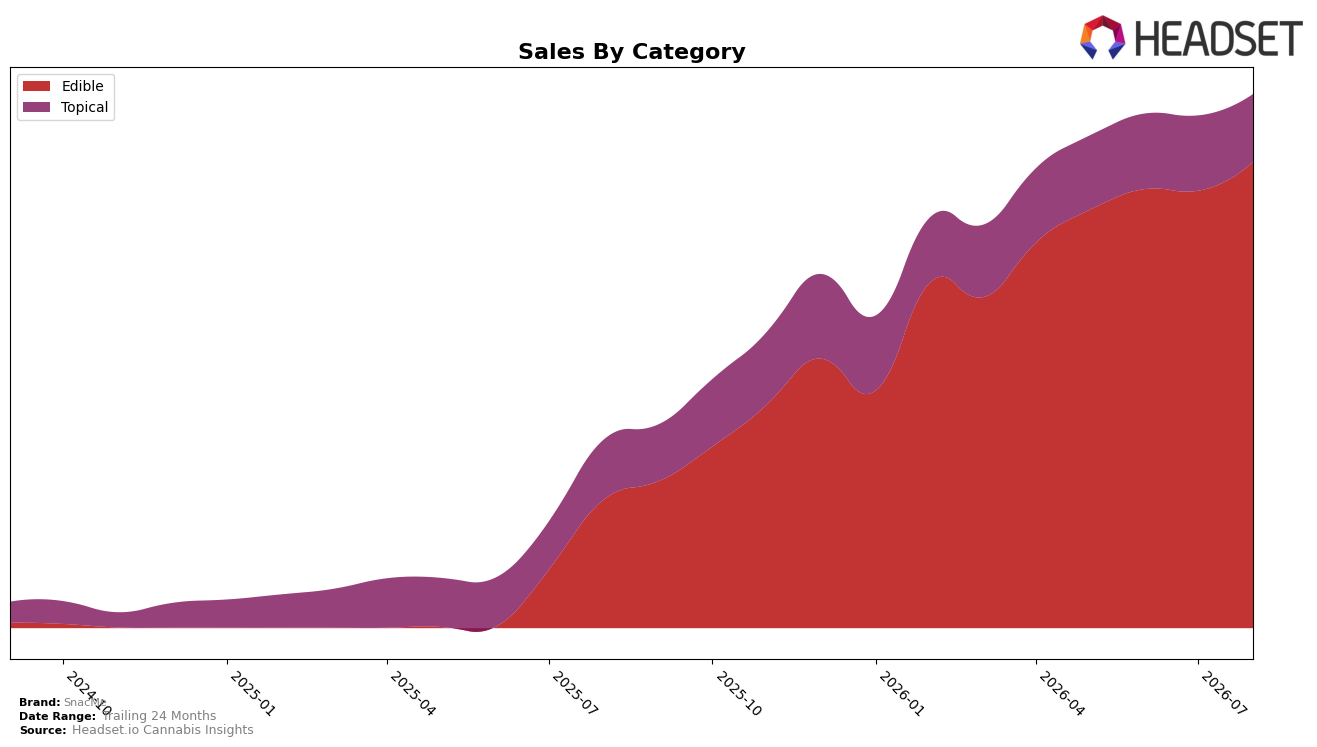
In August 2026, SnacMe concentrated 87.33% of sales in Edible with a 263.18% year-over-year gain and a 6.57% month-over-month uptick, while Topical held 12.67% share with a 13.17% year-over-year increase but a -9.78% month-over-month decline. The overall average price fell -6.54% year over year to $6.15, with Edible priced at $5.86 versus Topical at $9.24, indicating a mix-shift toward lower-priced volume even as total brand sales grew 183.75% year over year. The thesis is that category concentration and relative price positioning are accelerating volume-led growth in Edible while Topical’s month-over-month contraction tempers diversification.
With Edible now anchoring share at 87.33% and ranking 18 in Washington Edible, the 6.57% month-over-month lift alongside a -6.54% year-over-year average price move signals a scale strategy that prioritizes unit throughput over margin per unit; conversely, Topical’s -9.78% month-over-month decline at a $9.24 price point caps premium mix contribution despite a 13.17% year-over-year rise. Given brand sales up 183.75% year over year and 1,272.55% over 24 months, the pattern implies that sustaining rank gains in Washington will depend on defending Edible velocity while selectively stabilizing Topical to avoid over-reliance on a single category.
Competitive Landscape
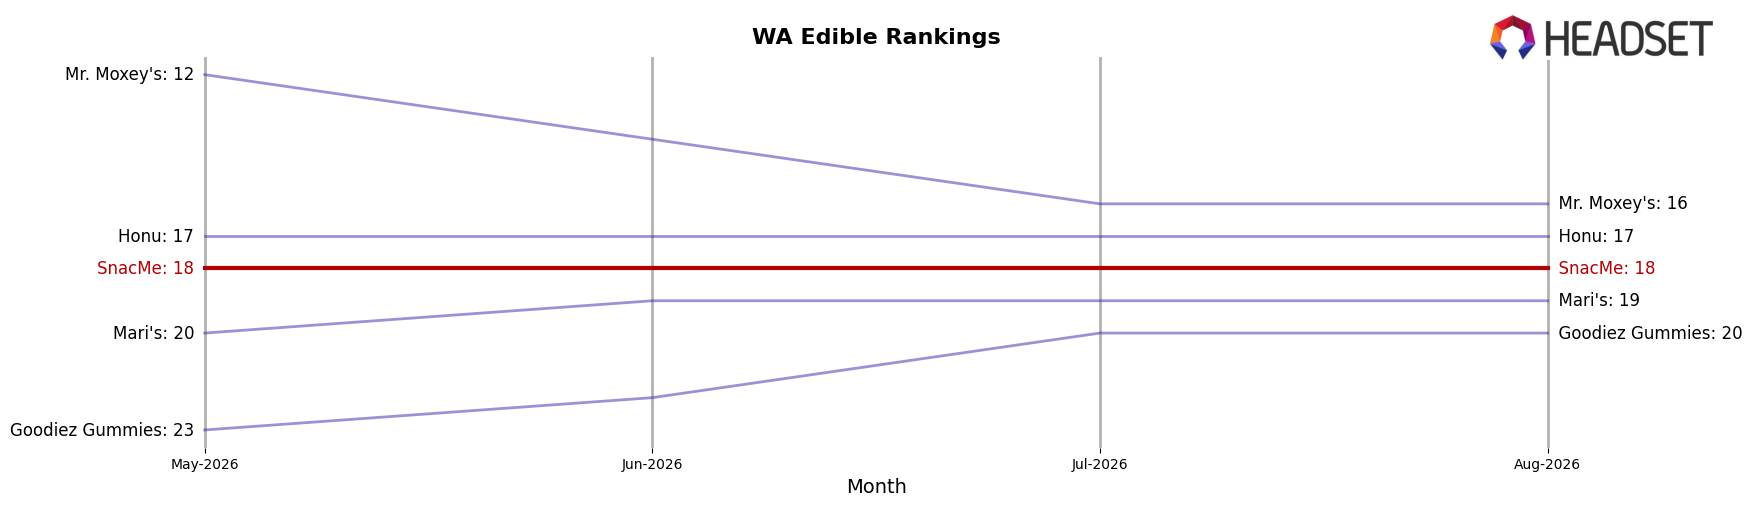
SnacMe sits at rank #18 in WA Edible in August 2026, improving 11 positions from #29 year over year, while holding flat versus three months ago at #18; this marks a peak rank of #18 in August 2026 and indicates a climb rather than volatility. In contrast, Wyld held #1 both this year and last with sales up 5.1% year over year, whereas Green Revolution stayed at #2 with sales down 7.0% year over year, signaling that SnacMe’s double-digit rank gain is occurring amid mixed leader momentum. The pattern implies SnacMe’s trajectory is moving from fringe to mid-pack, with stability over the last quarter at #18 and a year-over-year ascent of 11 ranks pointing to sustained shelf consolidation rather than a transient spike.
Notable Products
Pineapple Starfruit Gummy Bombs 10-Pack (100mg) posted the steepest decline in August 2026 at -11.7% MoM while slipping to rank 5, whereas Gummy Bombs - Candy Apple Gummies 10-Pack (100mg) rose 17.4% MoM to hold rank 1. Gummy Bombs - Pink Razz Gummies 10-Pack (100mg) accelerated 24.9% MoM to rank 6 as Gummy Bombs - Dragon Berry Gummies 10-Pack (100mg) fell -8.7% MoM to rank 4, indicating flavor polarization within the lineup. Eight of the top ten are Edible SKUs, and the top three ranks are all gummies, concentrating demand in a single format even as Blue Watermelon Gummy Bombs 10-Pack (100mg) was nearly flat at -0.7% MoM and Gummy Bomb - Huckleberry Gummies 10-Pack (100mg) gained 10.0% at rank 2. This mix points to a strategy favoring a tight set of fast-cycling gummy flavors, with selective pruning of underperforming variants to protect the rank 1–3 core and sustain average price around $19,000 for the leader.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

