


Where to Buy
Snobby Dankins is stocked at 22 licensed dispensaries across New York, with the deepest coverage in New York, Niagara Falls, Syracuse, Albany, and Ballston Spa. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
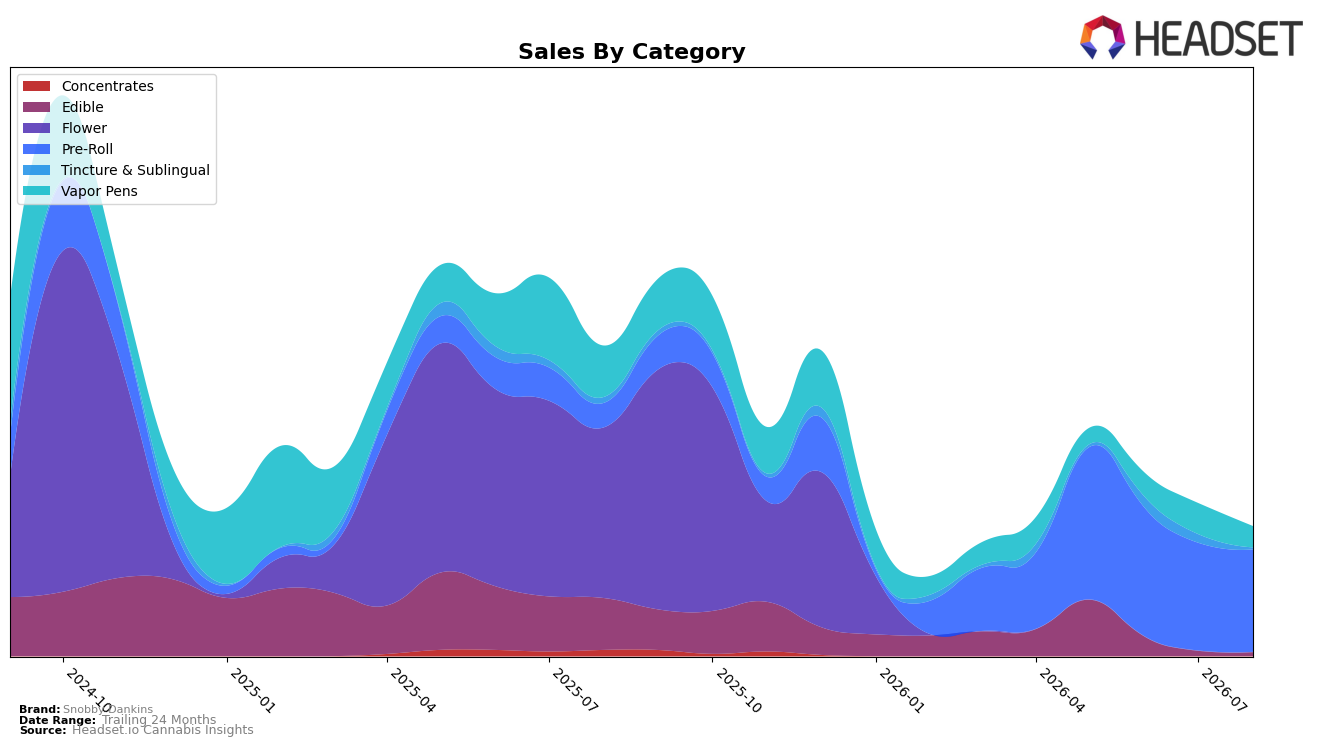
In August 2026, Snobby Dankins concentrated 79.5% share in Pre-Roll with 322.5% year-over-year growth but a 5.0% month-over-month decline, while Vapor Pens fell to 16.3% share with a 58.9% YoY contraction and a 31.9% MoM drop. Edible slipped to 2.8% share with 92.9% YoY and 27.3% MoM declines, and Tincture & Sublingual narrowed to 1.3% share with 69.6% YoY and 79.6% MoM decreases; the brand’s average price fell 57.4% YoY to $10.18, and total brand sales declined 58.4% YoY. The pattern implies a deliberate pivot toward lower-priced Pre-Rolls at the expense of Vapor Pens and Edible, concentrating volume in a single category while compressing price to defend share.
The 79.5% Pre-Roll mix alongside a 31.9% MoM retreat in Vapor Pens and a 27.3% MoM pullback in Edible indicates risk of overexposure to one format even as Pre-Roll gains 322.5% YoY; combined with a 77.9% 24-month sales decline, the portfolio is skewing short-term volume over diversification. With New York as the top state and Edible the top category in the brand’s historical context but carrying only 2.8% current share and no rank reported, the 92.9% YoY decline in Edible and 69.6% YoY drop in Tincture & Sublingual suggest weakened premium and wellness positioning; the implication is that sustained relevance will hinge on either rebuilding Vapor Pens and Edible share by reversing the 31.9% and 27.3% MoM declines or accepting a value-led Pre-Roll identity with tighter price architecture.
Competitive Landscape
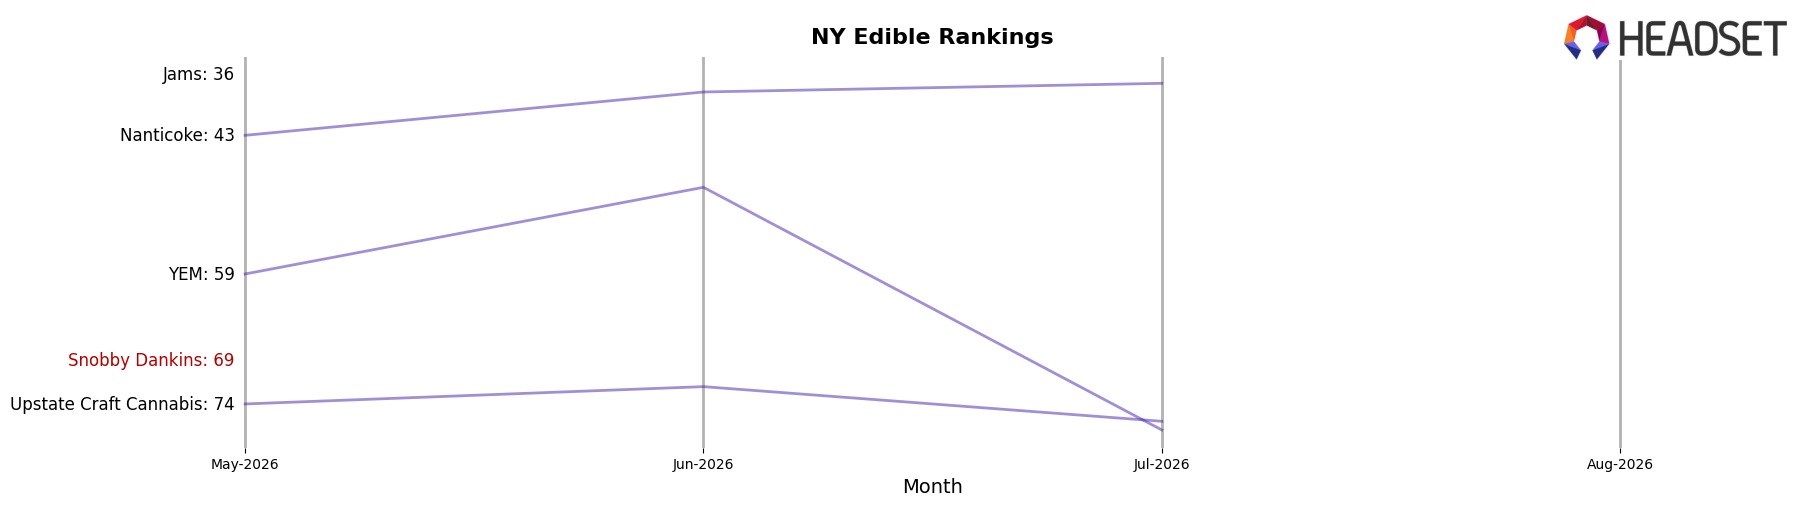
Snobby Dankins sits at rank #122 in NY Edible in August 2026, sliding 59 positions from #63 year over year, and falling 53 spots from #69 in May 2026; both shifts widen the gap from its peak at #48 in September 2024 and indicate declining category visibility as top-tier rivals consolidate. While Off Hours moved down from #1 to #2 year over year amid a -24.8% sales change and Gron / Grön climbed from #4 to #3 with +14.8% sales growth, Snobby Dankins’ drop to #122 places it far outside the top 100 as Wyld edged from #3 to #4 with +7.1% sales growth. The pattern implies that Snobby Dankins is losing rank share faster than mid-pack competitors and will require a discrete demand or distribution shift to reenter the competitive set reflected by ranks #1–#5.
Notable Products
Grape Crush Pre-Roll 2-Pack (1g) posted the steepest decline in August 2026 at -32.8% MoM, sliding to rank 3, while category leader Mixtape Vol 2 Infused Pre-Roll 2-Pack (1g) dipped -9.4% MoM but held rank 1. The Durbanator Pre-Roll 2-Pack (1g) rose 39.5% MoM to rank 2, narrowing the gap to the top SKU where Mixtape Vol 2 booked $2,590. With all top-10 entries concentrated in the Pre-Roll category and two of the top three moving in opposite directions (-32.8% vs +39.5%), the mix implies a pivot toward bolder, faster-cycling strains that can trade share rapidly within a single-format lineup.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

