
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Srene is stocked at 36 licensed dispensaries across Nevada, with the deepest coverage in Las Vegas, Reno, Henderson, Sparks, and Fallon. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
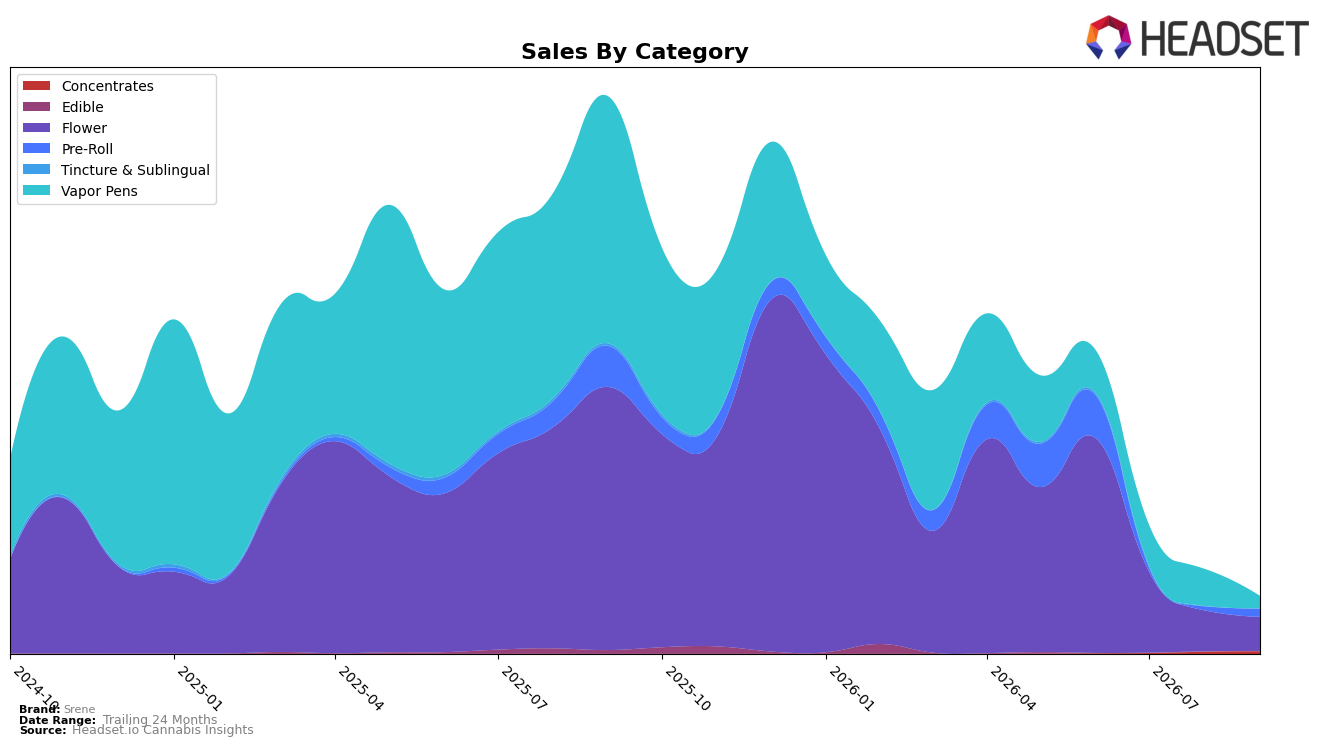
In September 2026, Srene’s mix tilted further toward Flower at 60.00% share, yet Flower contracted by 16.91% MoM and 87.15% YoY, while Vapor Pens fell faster with a 67.18% MoM drop and a 95.11% YoY decline; against that, Pre-Roll surged 110.46% MoM despite an 80.51% YoY decline, and Concentrates gained 19.10% MoM with no YoY baseline. With average price down 11.90% YoY to $20.63 and Vapor Pens shrinking to 21.44% share versus Flower’s 60.00%, the pattern implies Srene is consolidating around lower-priced inhalables and away from higher-elasticity formats, with Nevada Flower ranking at position 55 signaling limited headroom without mix rebalancing.
The shift—Pre-Roll up 110.46% MoM and Concentrates up 19.10% MoM while Flower and Vapor Pens dropped 16.91% and 67.18% MoM—indicates an opportunistic pivot toward formats that convert at lower ticket sizes while defending core Flower at a 60.00% share. Given the 87.15% YoY decline in Flower alongside a 95.11% YoY fall in Vapor Pens, September 2026 positioning points to prioritizing Pre-Roll and Concentrates as entry points to stabilize traffic, then laddering into Flower to recover rank 55 in Nevada, effectively trading margin per unit for share retention as price elasticity rises.
Competitive Landscape
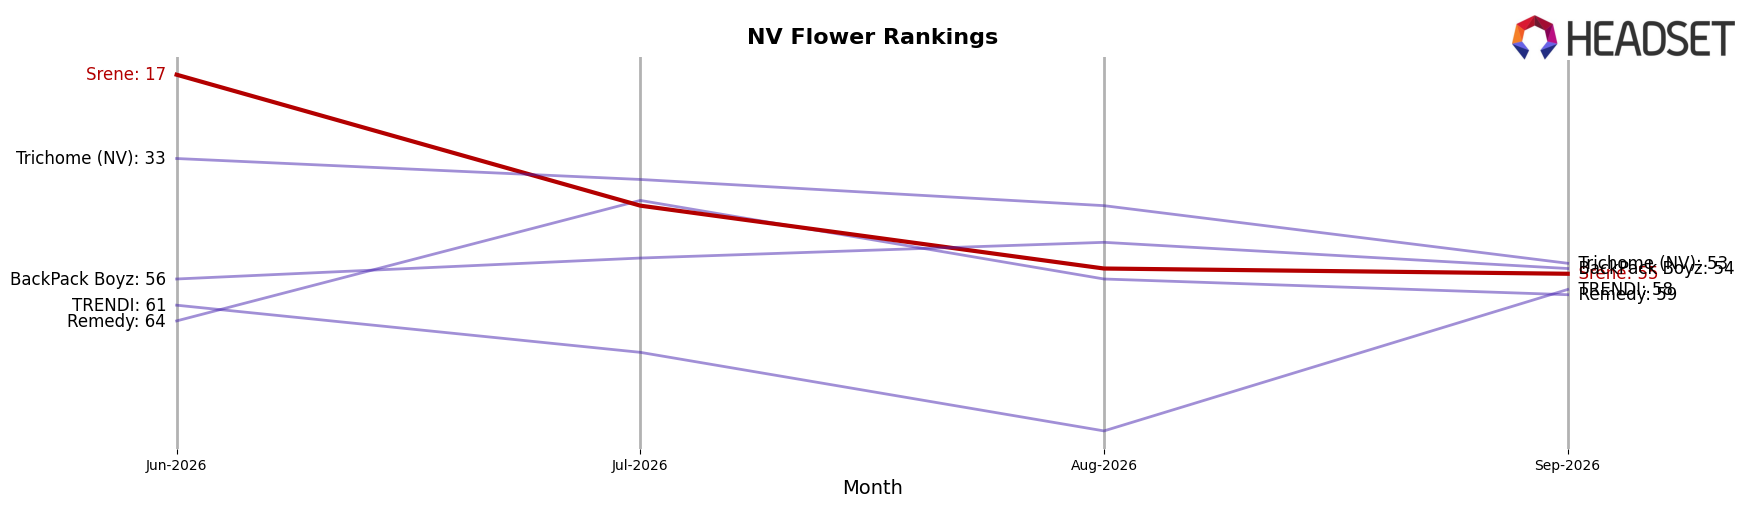
Srene sits at rank #55 in NV Flower in September 2026, falling 38 spots year over year from #17, after having been as high as #11 in December 2025; by contrast, RYTHM held #1 both this year and last (up 19.7% YoY in sales) and Neon Moon advanced from #9 to #4 with an 82.7% YoY sales increase, signaling that Srene’s shift from #17 in June 2026 to #55 in September 2026 corresponds to a relative share loss while faster-rising peers consolidate top ranks. This trajectory from a peak of #11 to #55, alongside competitors like STIIIZY holding #2 with 24.2% YoY sales growth and Alternative Medicine Association / AMA improving rank from #5 to #3 on 32.6% YoY sales growth, implies that Srene’s recent rank compression is driven more by rivals’ acceleration than category contraction, and suggests priority on regaining distribution or velocity where the brand ceded relative position.
Notable Products
Royale Grape (3.5g) posted the steepest move in September 2026 with a -65.1% MoM drop while sinking to rank 7, and Limesicle (14g) also contracted by -39.0% to rank 5 with $7,855 in sales; this tandem decline suggests large-size Flower formats lost momentum even as top-3 positions stayed concentrated in smaller Flower SKUs. Tropicana Acai (3.5g) held rank 1 while Rose Sorbet (3.5g) slipped -3.8% at rank 2, and with four of the top ten being Flower SKUs, the category still anchors the lineup despite volatility inside it. BioFuel Distillate Cartridge (1g) fell -33.3% at rank 9, indicating Vapor Pens are not offsetting Flower softness and leaving Pre-Rolls clustered mid-table at ranks 4, 6, and 8. The pattern points to a recalibration toward 3.5g Flower leadership and away from bulk and non-Flower formats, implying Srene’s near-term mix favors high-velocity eighths over breadth across form factors.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

