

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Stratos is stocked at 100 licensed dispensaries across Colorado and Washington, 98 of them in Colorado, with the deepest coverage in Colorado Springs, Denver, Aurora, Boulder, and Pueblo. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
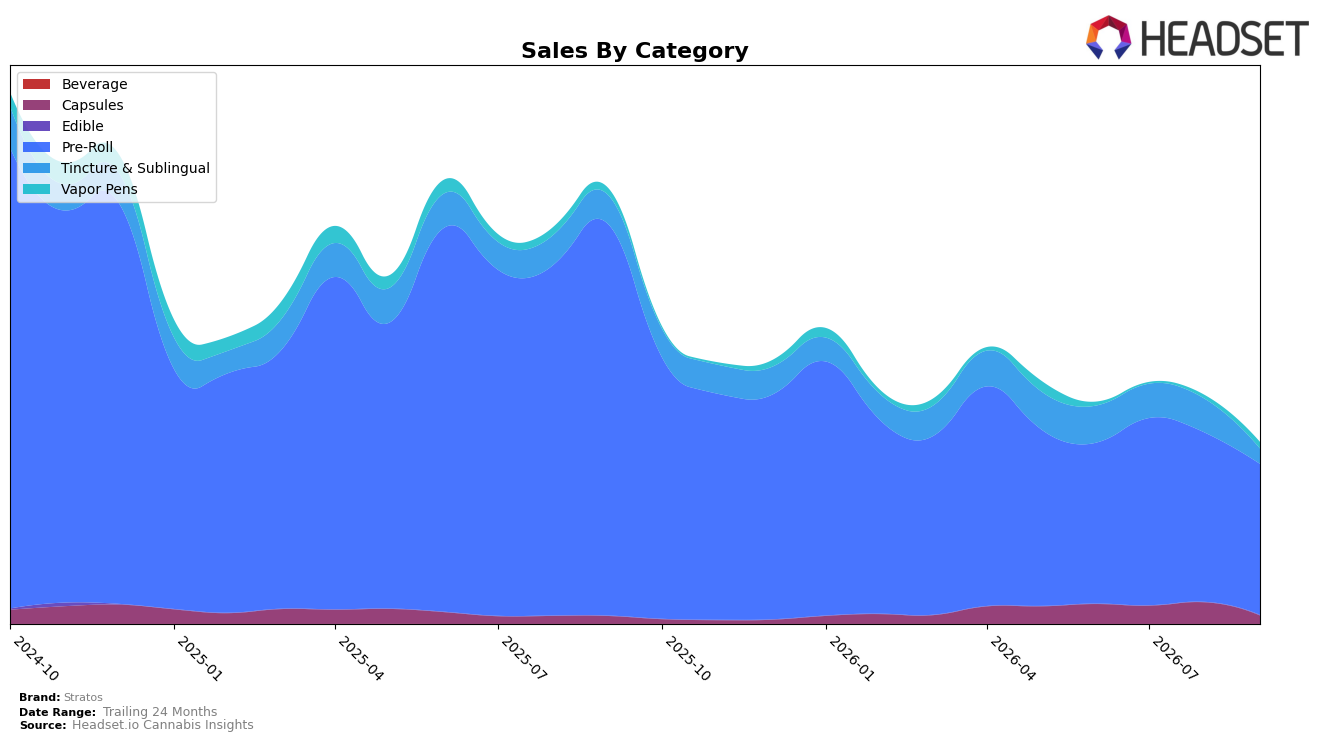
Pre-Roll concentrates 83.72% of Stratos’s September 2026 mix, but its sales fell 61.49% year over year and 10.85% month over month, while Tincture & Sublingual at 8.32% share declined 47.77% YoY and 55.11% MoM. Capsules holds 4.46% share with a 6.91% YoY increase but a 62.23% MoM drop, and Vapor Pens at 3.43% share contracted 8.54% YoY yet expanded 81.42% MoM; Stratos’s average price rose 1.71% YoY to $12.46, and the brand’s overall sales decreased 58.55% YoY. With Pre-Roll ranked 37 in Colorado and the core category down 61.49% YoY, the pattern implies overexposure to a contracting anchor that is not being offset by small but faster-moving pockets like Vapor Pens.
The combination of an 81.42% MoM rebound in Vapor Pens alongside a 10.85% MoM retreat in Pre-Roll and a 55.11% MoM pullback in Tincture & Sublingual indicates that incremental momentum is shifting toward inhalable convenience rather than wellness formats. Given Pre-Roll’s 83.72% share and a 61.49% YoY slide while Capsules posted a 6.91% YoY gain but only 4.46% share, the mix suggests Stratos’s positioning remains tethered to a declining base, implying that near-term stabilization depends on reallocating assortment and promotion toward categories exhibiting month-over-month traction such as Vapor Pens while reducing reliance on Pre-Roll where rank 37 signals limited competitive pull in Colorado.
Competitive Landscape
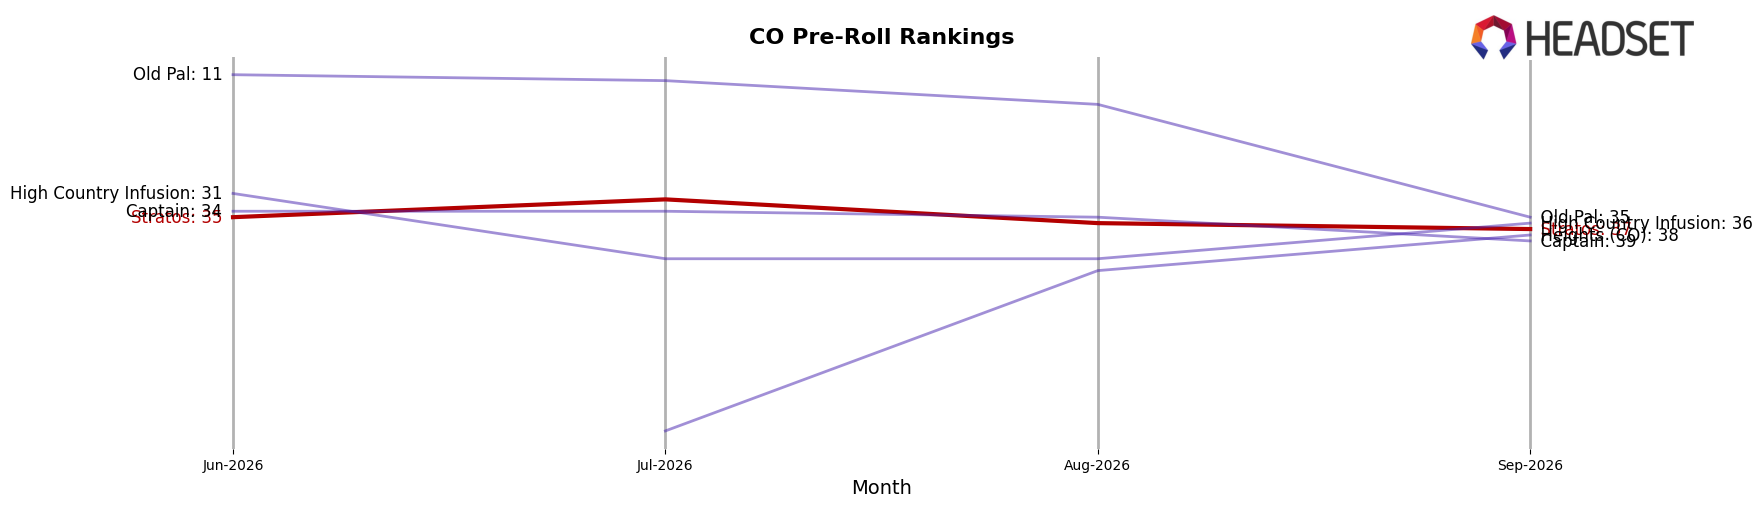
Stratos sits at rank #37 in CO Pre-Roll in September 2026, down 21 positions year over year from #16, and 2 spots below its June 2026 rank of #35, while its category peak of #11 in October 2024 underscores how far the brand has slid; meanwhile, Cali-Blaze moved up from #2 to #1 and Green Label Cannabis slipped from #1 to #2 as Be One Kind surged from #22 to #4 with 463.7% year-over-year sales growth, indicating that Stratos’s decline is occurring alongside aggressive upward mobility among rivals and implying that, without a shift in assortment or pricing, the brand’s trajectory points to ongoing share erosion.
Notable Products
Slow Burn - Why U Gelly Infused Pre-Roll (1g) posted the steepest movement in September 2026 with a -57.9% MoM decline and fell into rank 8, while Jupiter Joint- Moon Melon Infused Pre-Roll (1g) dropped -49.3% MoM and sits at rank 5. In contrast, Jupiter Joint - Pandora's Peach Infused Pre-Roll (1g) rose +6.9% MoM to hold rank 1, and Jupiter Joints - Solar Burst Infused Pre-Roll (1g) gained +7.3% MoM at rank 3. With all top ten SKUs concentrated in Pre-Roll, the mix points to reliance on a narrow format where volatility at the SKU level can swing share unless leadership anchors, like the rank 1 SKU with $13,055 sales, keep velocity stable.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

