

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
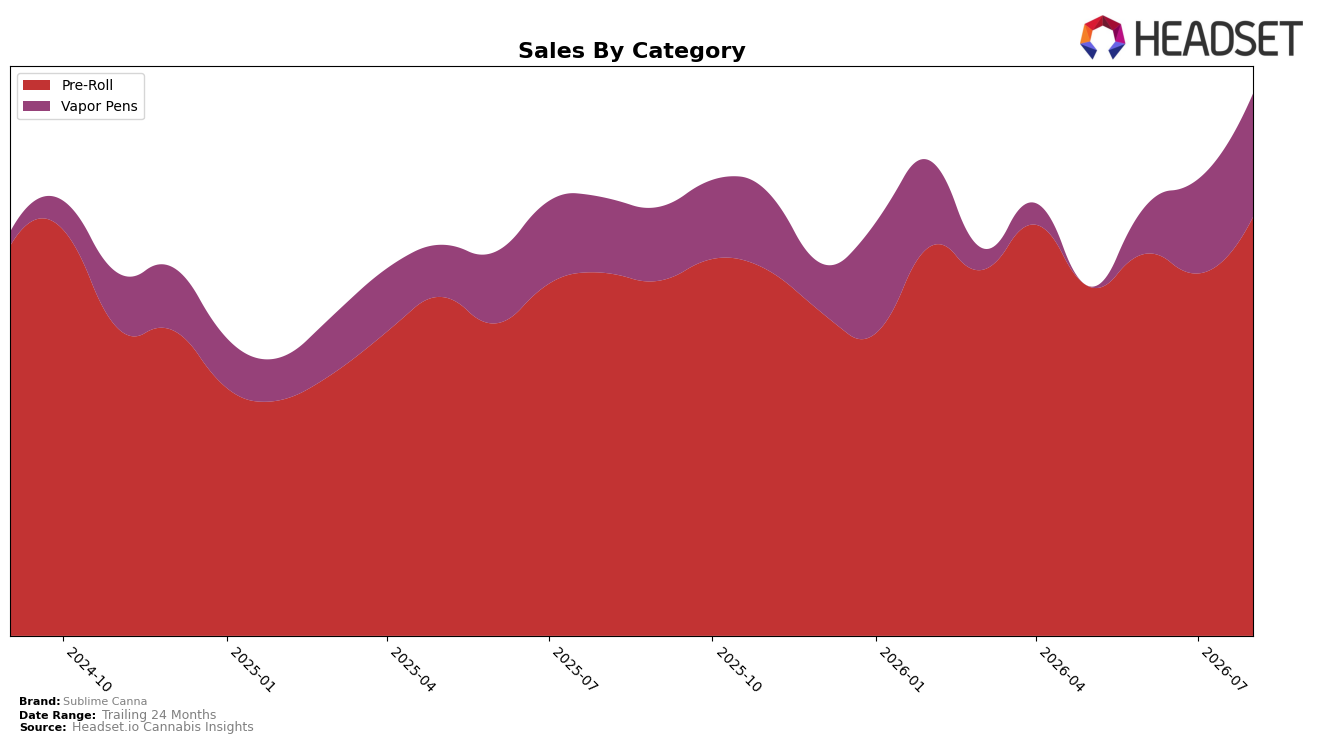
In August 2026, Sublime Canna concentrated 75.28% of sales in Pre-Roll, with the remaining 24.72% in Vapor Pens, and the brand’s overall year-over-year sales rose 21.67% while average price fell 24.91%. Within categories, Pre-Roll grew 14.57% year over year and 14.75% month over month, whereas Vapor Pens expanded 49.98% year over year and 25.36% month over month, indicating the mix is tilting toward the faster-growing segment even though Pre-Roll still leads. Given a Pre-Roll rank of 30 in California and a 13.37 average price in that category versus 16.77 in Vapor Pens, the combination of lower pricing and accelerating Vapor Pens momentum implies the portfolio is using price to defend Pre-Roll share while leveraging premium-adjacent pricing to capture outsized growth in Vapor Pens.
The widening spread between category growth rates — 14.57% year-over-year in Pre-Roll versus 49.98% in Vapor Pens — alongside a 10.61 percentage-point lower average price in Pre-Roll suggests a barbell positioning: value-led volume in Pre-Roll and higher-velocity trade-up in Vapor Pens. Month-over-month acceleration — 14.75% in Pre-Roll and 25.36% in Vapor Pens — coupled with an overall price compression of 24.91% points to elasticity-driven gains where Pre-Roll pricing supports rank stability at 30 in California while Vapor Pens growth expands the addressable base; the thesis is that sustaining a roughly 75/25 mix while nurturing Vapor Pens could lift aggregate growth without eroding Pre-Roll’s role as the traffic driver.
Competitive Landscape
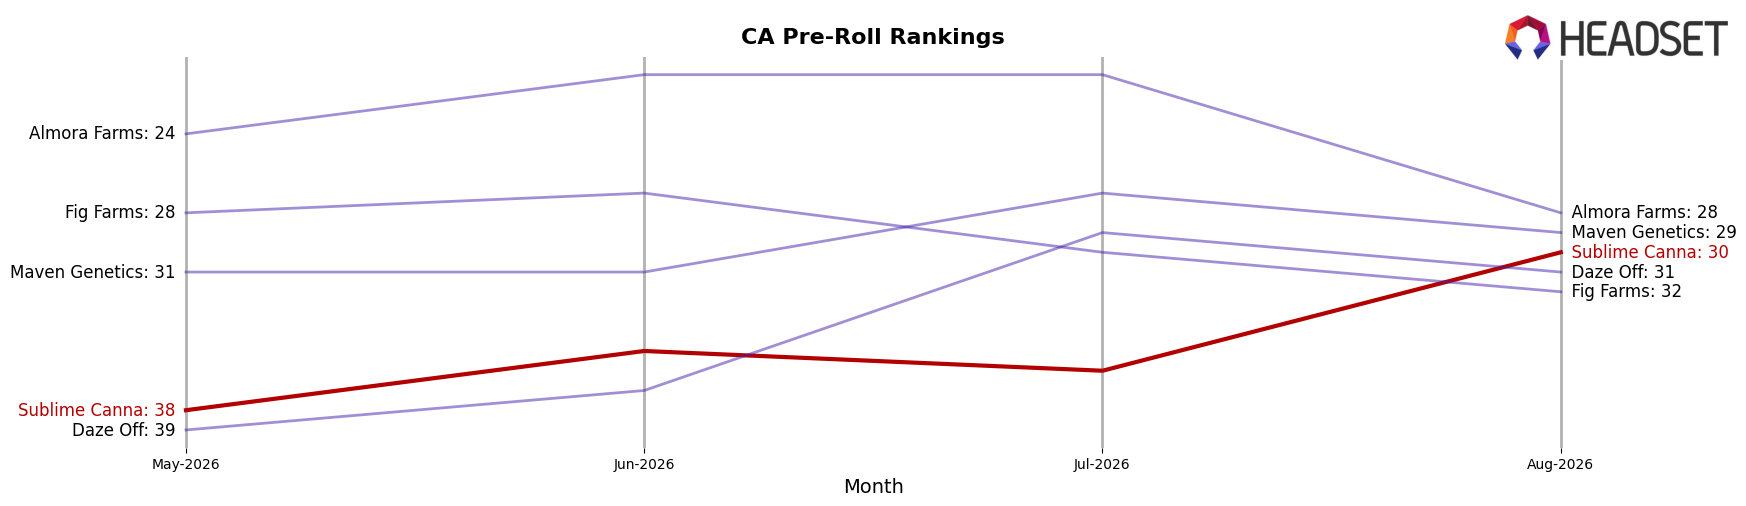
Sublime Canna is ranked #30 in California Pre-Roll in August 2026, unchanged from #30 year over year, after improving from #38 three months ago and sitting two spots below its peak of #28 from February 2026; meanwhile, Jeeter held #1 with a 5.6% YoY sales increase and STIIIZY stayed at #2 with a 10.2% YoY lift, indicating Sublime Canna’s flat YoY rank masks mid-year momentum that narrowed the gap from 10 ranks in May–June to 2 ranks from its February high, implying a stabilization at the lower end of the top 30 with upside tied to sustaining recent rank gains against entrenched leaders.
Notable Products
Fuzzies - Super Silver Haze Infused Pre-Roll (1g) delivered the standout move in August 2026 with a 100.5% month-over-month surge and a rank at 2, outpacing King Fuzzies - OG Kush Infused Pre-Roll (1g) which rose 89.9% to rank 1. In contrast, Fuzzies - Watermelon Z Kief Oil Infused Pre-Roll (1g) slipped 9.9% MoM while holding rank 6, indicating a selective shift within single-gram infused SKUs. With four of the top five items posting gains of 41.2% to 100.5% and pre-rolls occupying ranks 1 through 8, the mix signals a push toward dominance in infused pre-rolls over Vapor Pens.
Fuzzies Delights - Honeydew Diamond Infused Pre-Roll 5-Pack (2.5g) climbed 64.3% MoM to rank 4, while the Vapor Pens entries sat at ranks 9 and 10 with one posting a 25.9% MoM gain and the other flat versus unavailable prior-month data, suggesting lag relative to pre-roll momentum. The $39,611 performance of the Honeydew 5-Pack alongside 25.9% MoM growth for Fuzzies - Lemon Diesel Liquid Diamonds Destination Disposable (1g) at rank 10 frames a category split where pre-rolls are compounding faster than disposables. The pattern implies Sublime Canna is concentrating velocity in infused pre-rolls, using multi-pack and flagship single-gram formats to anchor share while testing measured expansion in disposables.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

