

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
District Cannabis is stocked at 144 licensed dispensaries across Maryland and District of Columbia, 102 of them in Maryland, with the deepest coverage in Baltimore, Silver Spring, Rockville, Annapolis, and Columbia. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
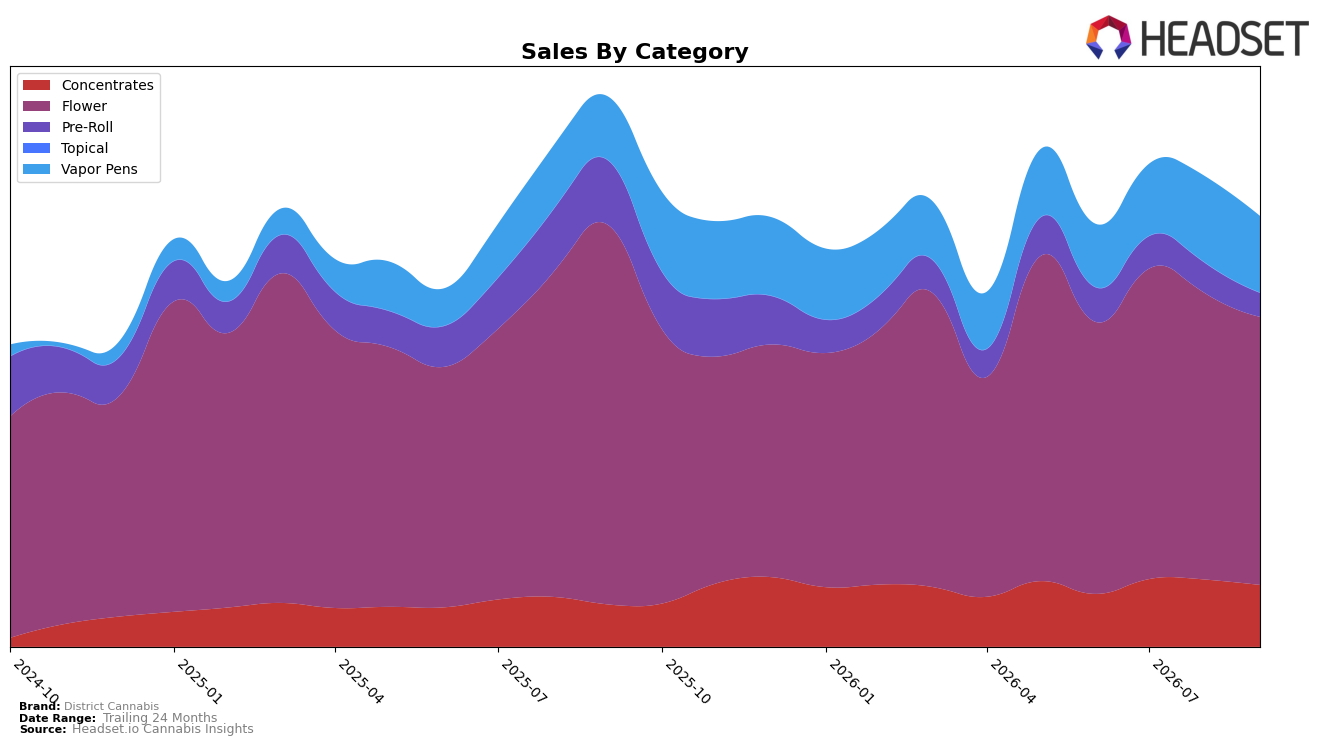
District Cannabis concentrated 62.39% of September 2026 sales in Flower, where year-over-year sales fell 29.36% and month-over-month declined 6.44%, while Vapor Pens held 17.77% share with a 20.52% year-over-year increase but an 11.42% month-over-month drop. Concentrates reached 14.35% share with a 46.42% year-over-year gain despite an 8.13% month-over-month slide, and Pre-Roll shrank to 5.49% share after a 63.24% year-over-year contraction and a 21.09% month-over-month decline. With average price up 4.44% year over year to $32.48 and Flower ranked 4 in Maryland, the pattern implies District Cannabis is overexposed to a contracting Flower base while the faster-growing but smaller Concentrates and Vapor Pens are not yet offsetting the core category’s drag.
The mix shift—Flower down 29.36% year over year at 62.39% share versus Concentrates up 46.42% year over year at 14.35% share—suggests margin and positioning will hinge on accelerating higher-growth subcategories without eroding Flower’s rank 4 foothold in Maryland. With Vapor Pens growing 20.52% year over year yet dropping 11.42% month over month, and Pre-Roll contracting 63.24% year over year to 5.49% share, the implication is to prioritize durable gains in Concentrates and stabilize monthly volatility in Vapor Pens so the brand can shift mix toward categories with improving trajectories while managing price effects after a 4.44% year-over-year average price increase.
Competitive Landscape
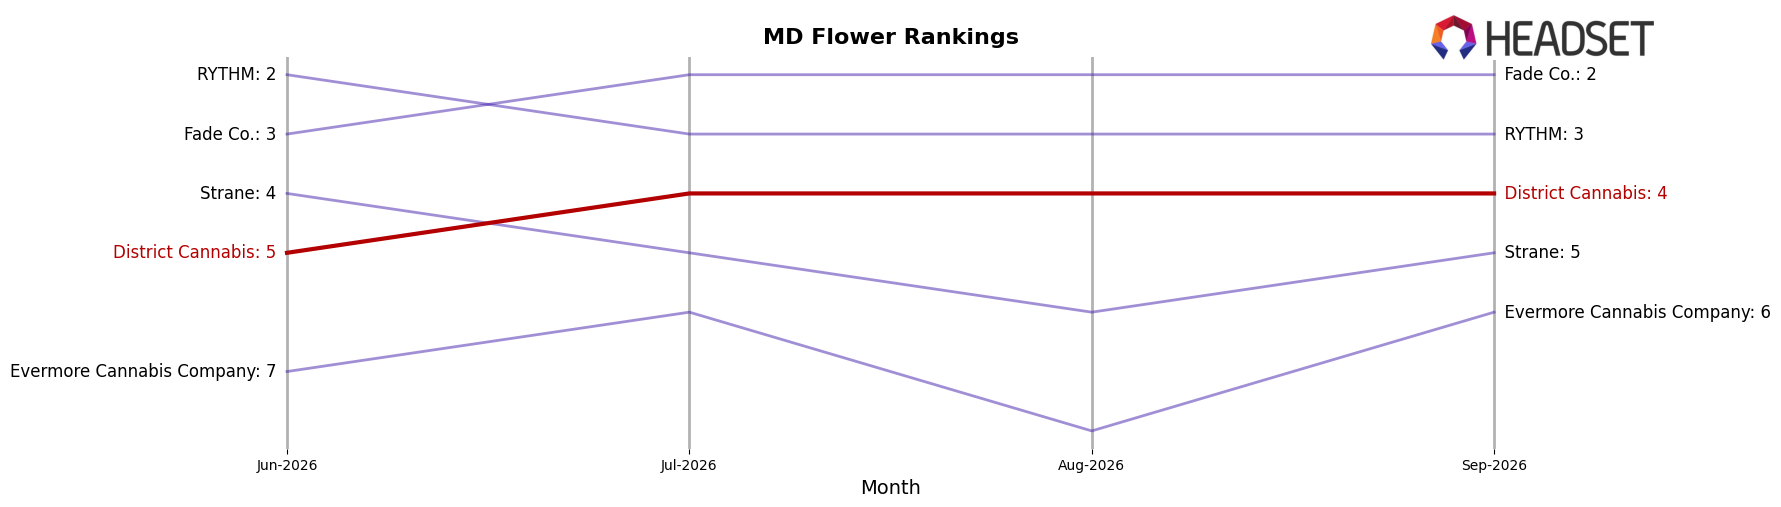
District Cannabis is ranked #4 in MD Flower in September 2026, improving 2 positions year over year and rising 1 spot from #5 in June 2026, while it remains 2 ranks below its peak of #2 from September 2025; meanwhile, SunMed holds #1 with a 1-position YoY improvement and RYTHM sits at #3 after a 1-position YoY lift but with a -3.6% sales YoY change, indicating District Cannabis’s upward rank movement is occurring amid a mixed competitor backdrop where the path back toward the prior peak will likely require displacing at least one stable top-three incumbent.
Notable Products
Layer Cake (3.5g) posted the steepest slide in September 2026 at -46.0% MoM while falling to rank 7, and Spritzer (3.5g) also contracted -38.1% MoM at rank 8, indicating a mid-tier retreat even as Pavé (3.5g) surged +43.9% MoM to rank 1. Gelato Cake (3.5g) advanced +31.5% MoM at rank 2, while Beach Cake (3.5g) declined -32.3% MoM at rank 6, and five of the top ten are Flower SKUs concentrated in cake-named strains, pointing to bifurcation between a few momentum leaders and several weakening variants. Zeroz (3.5g) held rank 3 with no MoM read alongside Florida Wedding (3.5g) at +28.1% MoM in rank 4, and Cherry Limeade Cake (3.5g) climbed +41.8% MoM to rank 5, which implies District Cannabis is consolidating around a narrower set of winning Flower profiles while pruning or repositioning underperforming cake-line extensions.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

