

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
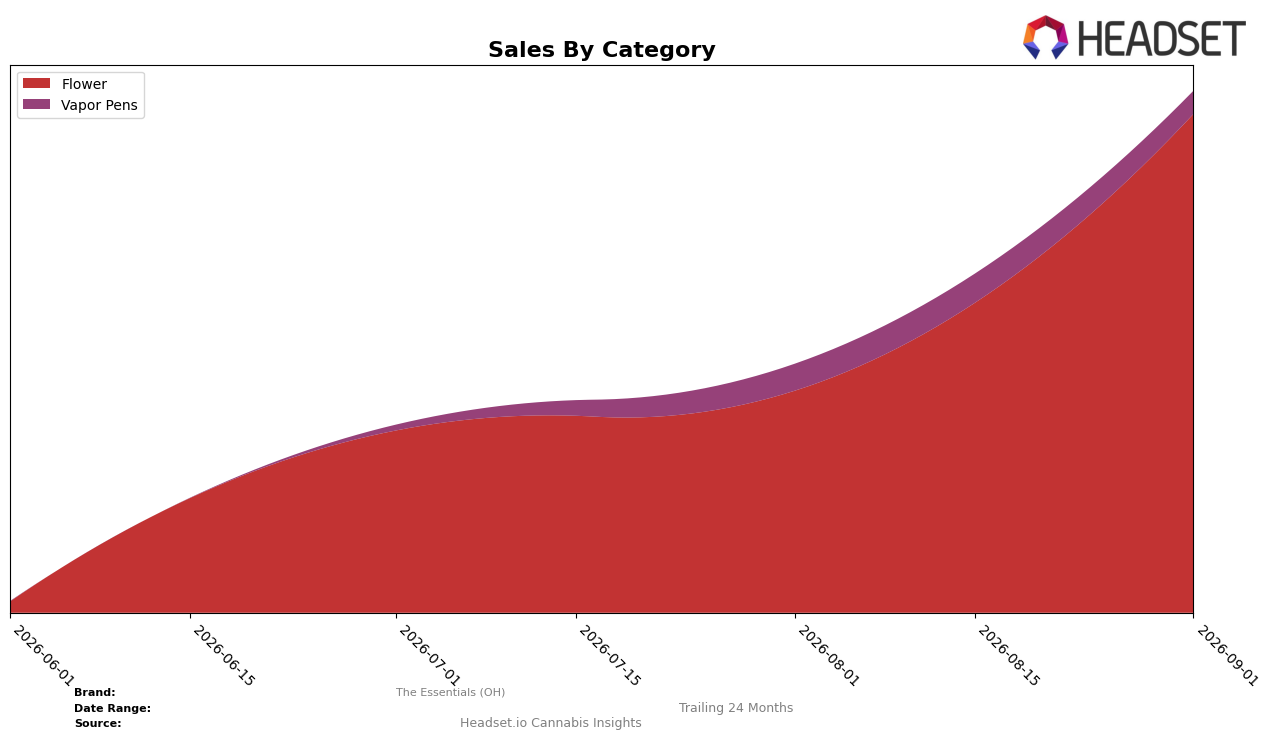
In September 2026, The Essentials (OH) concentrated 95.63% of sales in Flower and 4.37% in Vapor Pens, with Flower rising 124.93% month over month while Vapor Pens declined 14.16% month over month. Within Flower, the brand averaged $48.05 per unit versus $42.07 in Vapor Pens, and held rank 24 in Flower in Ohio, indicating share is anchored in a single category while a smaller adjacent category is contracting. The pattern implies a deliberate tilt toward high-velocity Flower that boosts short-term share but increases category concentration risk if Vapor Pens’ 4.37% share continues to erode.
The 124.93% month-over-month surge in Flower alongside a 14.16% month-over-month contraction in Vapor Pens shifts the portfolio toward a narrower value proposition, even as the Flower rank sits at 24 in Ohio. With 95.63% of sales tied to Flower and only 4.37% to Vapor Pens, the brand’s pricing near $48 in Flower versus $42 in Vapor Pens suggests margin is aligned with the expanding category while the smaller category loses momentum. This implies positioning that prioritizes depth in Flower over breadth across formats, which can support rank gains if Flower growth persists but may limit cross-category defensibility if Vapor Pens’ decline accelerates.
Competitive Landscape
The Essentials (OH) sits at rank #24 in OH Flower in September 2026, up 47 positions from #71 in June 2026, and hitting a new peak rank of #24 in September 2026; however, year-over-year rank change is unavailable while peers moved sharply, as Klutch Cannabis rose to #1 with a +13 YoY rank change and 162.4% YoY sales growth and King City Gardens advanced to #2 with a +10 YoY rank change and 77.4% YoY growth. Against this backdrop, The Essentials (OH)’s 47-rank climb quarter-over-quarter alongside competitors’ double- and triple-digit YoY gains implies momentum built on recent distribution or assortment expansion, but the gap to the top tier suggests share capture will depend on sustaining rank in October 2026 and converting the late-quarter surge into steady monthly velocity.

Notable Products
Momochi (14.15g) posted the largest movement with a 472% month-over-month surge to rank 3, while Triple Beam (14.15g) fell 56% month over month to rank 4, indicating a rapid rotation within the mid-size Flower lineup. Triple Beam (28.3g) jumped 155% month over month to rank 7, whereas Bubble Truffle (2.83g) held rank 1 and Tamalez (14.15g) placed at rank 2, and eight of the top ten are Flower SKUs across 2.83g, 14.15g, and 28.3g sizes, pointing to a pack-size barbell that is concentrating demand in both value ounces and selective premium eighths.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

