
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeWhere to Buy
The Fight is stocked at 24 licensed dispensaries across California, with the deepest coverage in Corona, Los Angeles, Vista, Needles, and El Monte. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
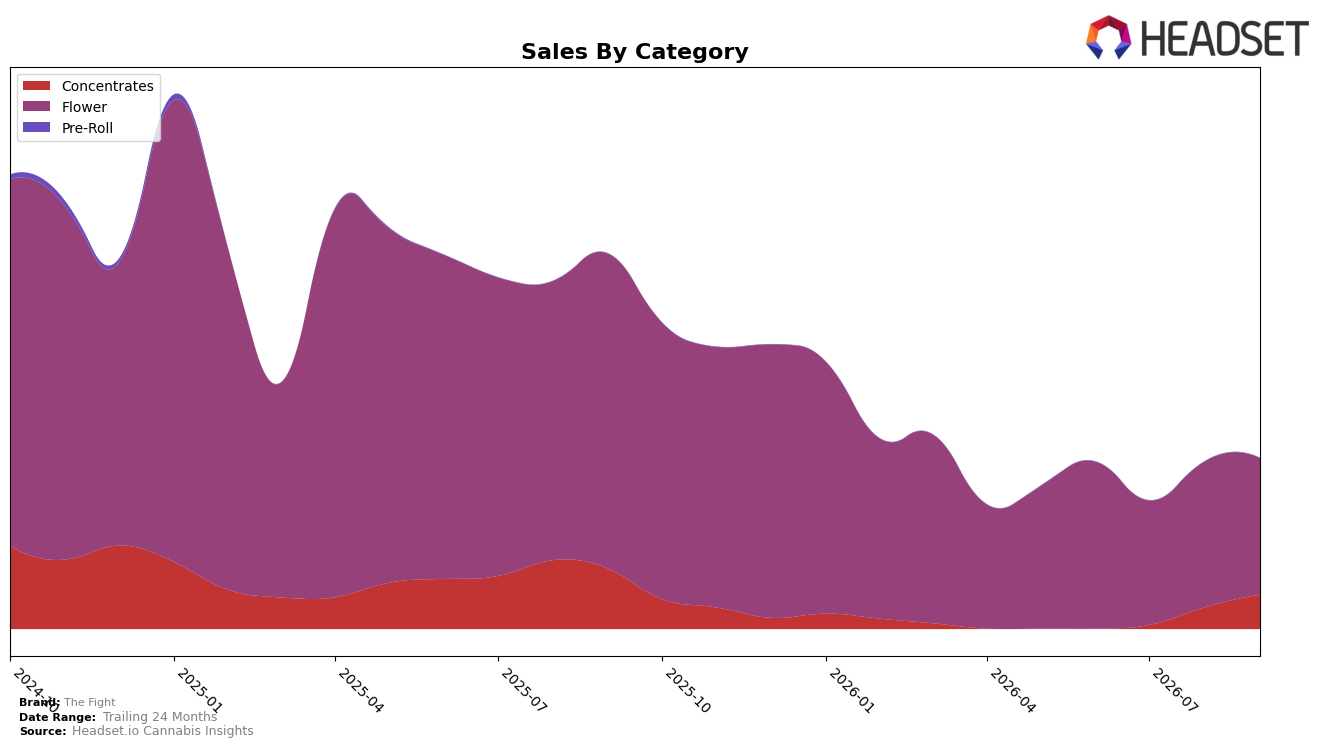
The Fight’s category mix in September 2026 concentrated 80.12% of sales in Flower with a year-over-year decline of 56.67% and a month-over-month dip of 6.35%, while Concentrates contributed 19.88% with a 43.54% year-over-year decline but a 59.31% month-over-month surge; the brand’s average price fell 15.69% year-over-year to $24.40, contrasting with Flower’s higher category-level average price of $42.87. In California Flower, the brand sat at rank 96, indicating lower shelf visibility, and the mix skew combined with a 54.57% brand-level year-over-year sales contraction implies a portfolio anchored to a weakening core while a smaller segment is exhibiting short-cycle demand recovery.
The sharp month-over-month rise in Concentrates share potential against a 6.35% Flower contraction suggests The Fight is pivoting toward a faster-moving subsegment without yet resetting its ranking gravity in California, where a 96 rank limits organic pull; the 59.31% month-over-month upswing could translate into incremental share recapture if sustained across two cycles. With 80.12% of volume still concentrated in a category declining 56.67% year-over-year and brand sales down 54.57% year-over-year, the positioning thesis is to accelerate mix rebalancing toward Concentrates while using the 15.69% average price reduction and category-level price deltas to defend Flower velocity, implying near-term focus on margin-light share stabilization followed by mix-led rank improvement.
Competitive Landscape
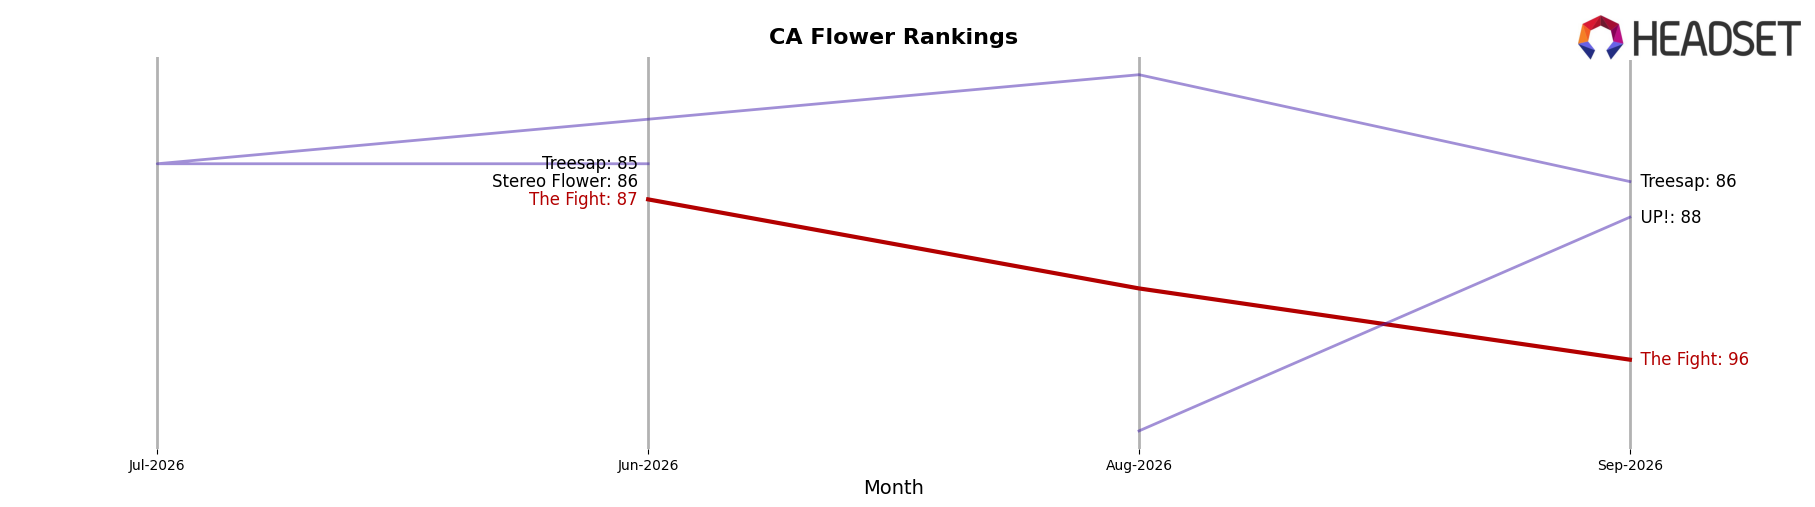
The Fight sits at rank #96 in CA Flower for September 2026, down 38 positions year over year from #58 and slipping 9 spots versus June 2026’s #87, while still well below the peak at #47 in January 2025; in contrast, STIIIZY moved from #2 to #1 and CAM climbed from #3 to #2 as Oakfruitland jumped from #11 to #5 with 73.5% YoY sales growth, indicating that The Fight’s downward rank drift amid competitors gaining share points to erosion in relative velocity rather than a cyclical dip.
Notable Products
Nelly's Dank Crumble (1g) posted the largest movement in September 2026 with +73.6% MoM, vaulting into rank 4 while Jimmy's Glue Sugar (1g) advanced +67.7% MoM to rank 2. Space Cake Crumble (1g) also surged +58.2% MoM at rank 3, and Sundae Driver Badder (1g) rose +43.5% MoM to hold rank 1; four of the top ten are Concentrates SKUs, indicating a cluster of high-velocity gains at the top of the chart. Northern Lights (14g) was the lone Flower mover with +18.9% MoM at rank 10, contrasting with stable but non-MoM-tracked Flower entries at ranks 5–9, where The Fight x Smokers Club - Extreme - Gorilla Glue (14g) led Flower at rank 5 with $28,990 current sales. The pattern implies a tilt toward Concentrates driving incremental share and rank mobility, while Flower maintains volume presence without equivalent MoM acceleration.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

