

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
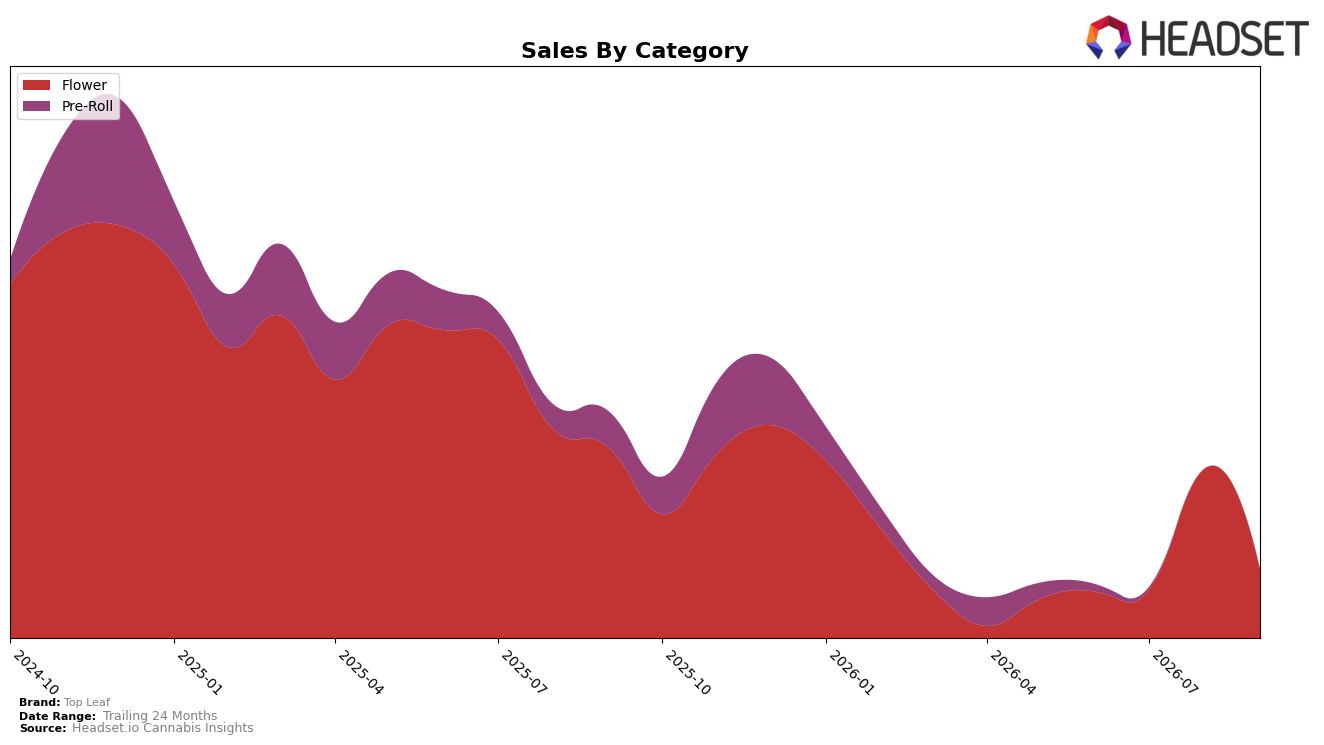
In September 2026, Flower held 83.57% share with a year-over-year decline of 59.10% and a month-over-month drop of 54.41%, while Pre-Roll accounted for 16.43% share with a year-over-year decline of 68.12% but a month-over-month increase of 5.07%. The brand’s average price decreased 20.42% year over year to $34.40, with Flower pricing at $36.97 and Pre-Roll at $25.42, indicating downshifts that coincide with a 60.92% year-over-year sales contraction. The pattern implies Top Leaf is overexposed to a shrinking Flower base and is relying on a modest Pre-Roll rebound to stabilize mix in Saskatchewan.
With Flower at 83.57% share and ranked 41 in Saskatchewan Flower, the 54.41% month-over-month decline versus a 5.07% month-over-month gain in Pre-Roll points to a category pivot opportunity where incremental Pre-Roll share can offset Flower volatility. Given a 68.12% year-over-year decline in Pre-Roll against a 59.10% decline in Flower, the pricing cut of 20.42% year over year suggests discounting is not reversing demand erosion, so positioning should shift toward differentiated formats and pack sizes where the 5.07% month-over-month lift indicates short-cycle elasticity. The thesis is that mix rebalancing toward Pre-Roll and tightening SKU breadth in Flower could improve rank traction from 41 by reducing dependence on the steepest month-over-month drag.
Competitive Landscape
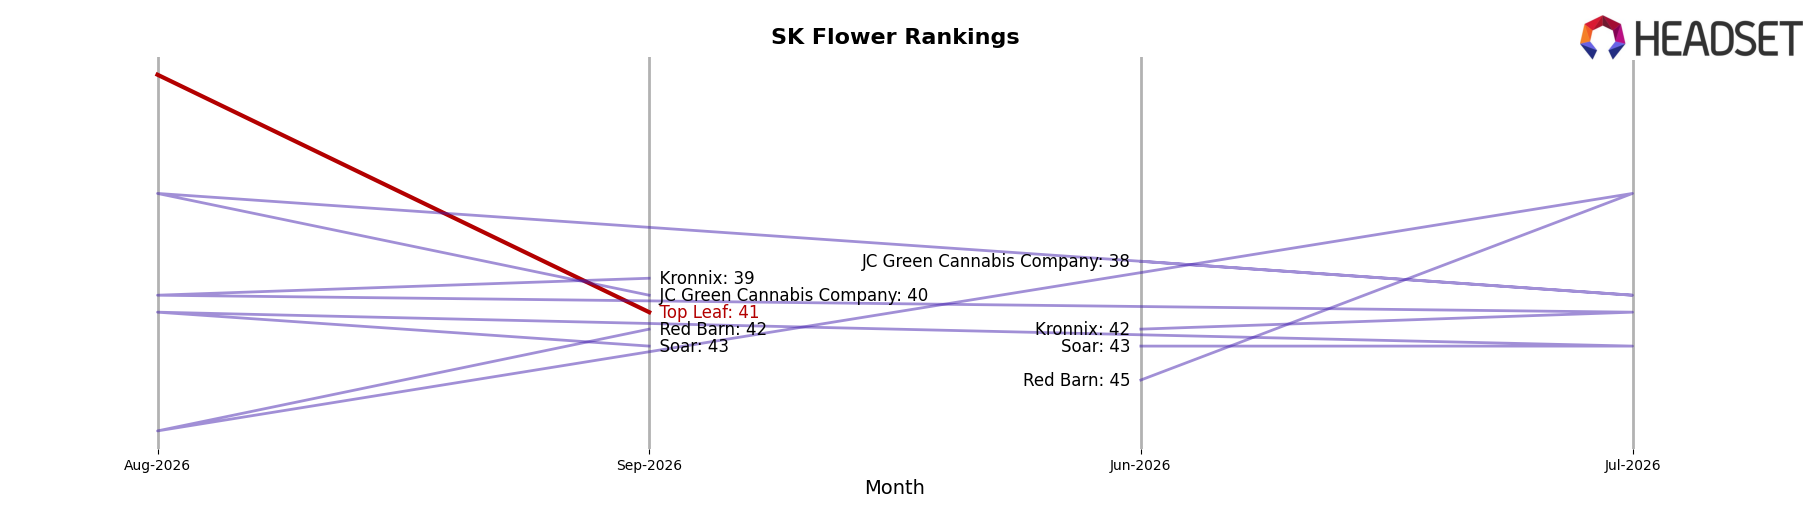
Top Leaf sits at rank #41 in SK Flower for September 2026, with no reported year-over-year rank, after peaking at #27 in August 2026, a 14-position slide month-over-month alongside a one-month retreat from its peak. Against this backdrop, Back Forty / Back 40 Cannabis holds #1 with a 22.8% sales lift year over year while Spinach is #2 with a 60.2% YoY increase, indicating that Top Leaf’s drop from #27 to #41 coincides with competitors either maintaining #1 or improving ranks by up to 5 positions. With Zippy (Canada) up to #5 and expanding 364.7% YoY from a rank gain of 32 positions, and Good Supply anchored at #4 with a 3-position YoY improvement, the pattern implies that Top Leaf’s trajectory—down 14 ranks month-over-month and outside the top 40 in September 2026—suggests share is consolidating with faster-growing leaders, requiring either re-entry toward the #27 peak or risk of drifting further from the top quartile.
Notable Products
Notorious THC Pre-Roll 3-Pack (1.5g) posted the standout move with a 437.7% month-over-month surge to rank 5, while Unicorn Poop (14g) climbed 80.3% to rank 6, indicating a sharp pivot toward formats that can scale quickly. At the same time, Nakatomi Plaza (7g) held rank 1 despite a -49.6% decline and Girl Scout Cookies (3.5g) fell -56.2% at rank 7, pointing to volatility within core Flower even at the top of the chart. Four of the top ten are Flower SKUs and four are Pre-Roll SKUs, and the split combined with Blue Dosi Caviar Infused Pre-Roll 4-Pack (2g) slipping -0.4% at rank 2 suggests an expanding role for value-driven multi-pack Pre-Rolls against softening legacy Flower sizes. The pattern implies Top Leaf is reallocating demand toward accessible Pre-Rolls while legacy Flower faces sharper downtrades, shifting the commercial mix toward higher-velocity, lower-price-per-session formats.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

