

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Nugz (Canada) is stocked at 27 licensed dispensaries across Oklahoma and Oregon, 24 of them in Oklahoma, with the deepest coverage in Tulsa, Oklahoma City, Catoosa, Edmond, and Broken Arrow. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
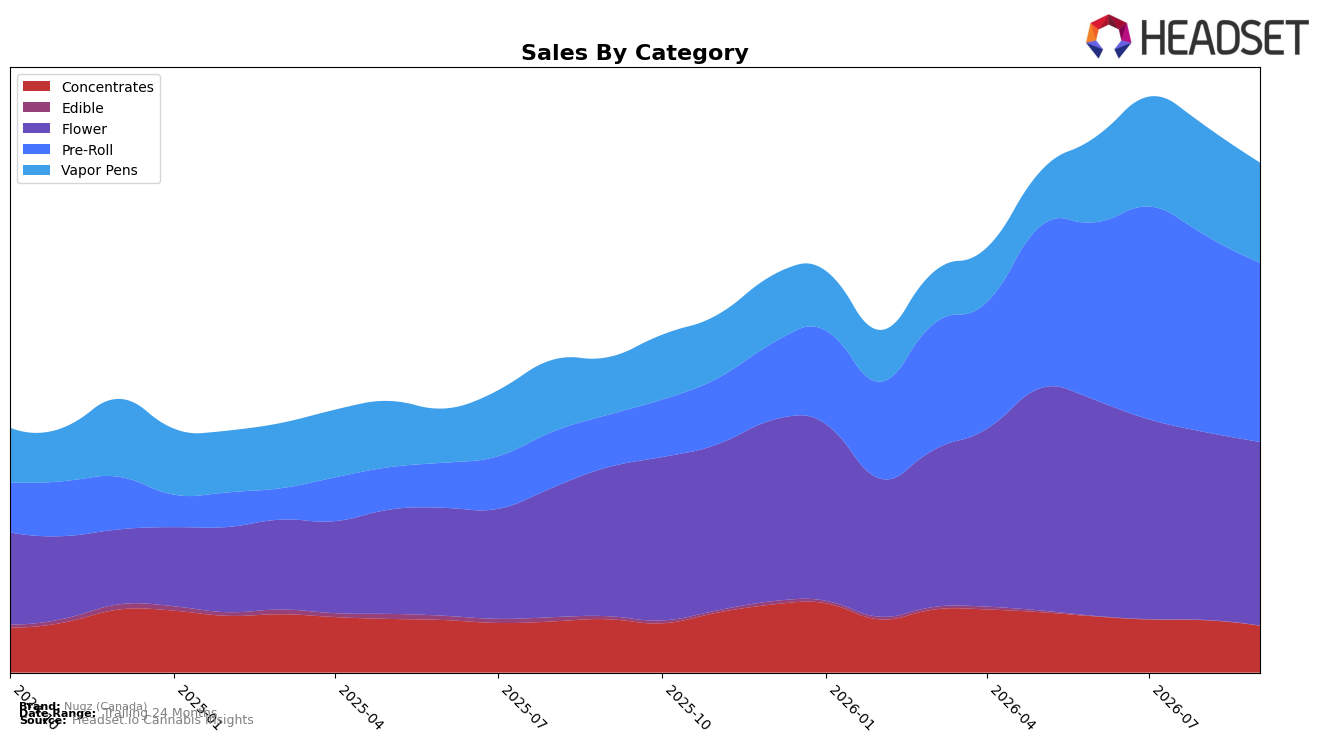
Nugz (Canada) concentrated nearly three-quarters of September 2026 sales in Flower at 36.03% share and Pre-Roll at 35.18%, with Vapor Pens at 19.62% and Concentrates at 9.17%, while Edible rounded down to 0.01%. Year over year, Pre-Roll expanded 242.99% and Vapor Pens rose 73.86%, contrasting with a 12.22% decline in Concentrates and a 98.58% collapse in Edible, and month over month all major lines dipped, with Pre-Roll down 9.09% and Vapor Pens down 8.60% versus Flower’s smaller 2.26% pullback. In Ontario Flower, Nugz (Canada) sat at rank 8, and the combination of outsized Pre-Roll growth alongside modest Flower YoY expansion of 23.18% implies a portfolio skew toward value-forward inhalables, even as September’s broad MoM softness suggests exposure to seasonal or promotional cadence rather than a structural shift.
The acceleration in lower-priced inhalable formats (Pre-Roll up 242.99% YoY at a 29.70 average price and Vapor Pens up 73.86% YoY at 34.39) versus a 12.22% YoY decline in Concentrates at 35.50 and a 98.58% YoY collapse in Edible indicates Nugz (Canada) is consolidating around high-velocity, mid-price baskets, with Flower’s 36.03% share and rank 8 anchoring mainstream presence. With average brand price up 16.39% YoY to $37.75 despite MoM declines across Flower at -2.26% and Pre-Roll at -9.09%, the mix shift toward Pre-Roll and continued Flower scale implies pricing power tied to inhalable convenience rather than breadth across categories, positioning the brand to trade consumers up within inhalables while deprioritizing fringe categories.
Competitive Landscape
Nugz (Canada) sits at rank #8 in Ontario Flower for September 2026, improving 5 positions year over year from #13 and slipping 1 spot from its August 2026 peak at #7; this contrasts with Spinach holding rank #1 versus #3 a year ago while growing sales 15.7%, and Back Forty / Back 40 Cannabis sliding to #3 from #1 amid a 7.4% sales decline. Relative momentum is mixed: Nugz (Canada) gained 5 ranks YoY while FIGR vaulted from #14 to #5 on 51.7% sales growth, and Shred held steady at #2 with 13.4% YoY sales growth; the implication is that Nugz (Canada)’s climb places it just inside the top 10, but the slight month-over-month dip and faster-rising peers indicate a need to convert proximity to its #7 peak into sustained share defense against accelerating mid-pack rivals.

Notable Products
The steepest decline came from Flavour Bomb - Pink Berry Rush Diamond Infused Pre-Roll 5-Pack (2.5g), down 29.7% MoM at rank 9, while Flavour Bomb - Grape Gonzo Liquid Diamonds Disposable (0.95g) fell 24.6% at rank 3. Flavour Bomb 40 - Fruit Blast Taster Pack Infused Pre-Roll 5-Pack (2.5g) retained rank 1 despite a 15.4% MoM drop, and Kingpin Wrap Sativa Infused Pre-Roll (1g) inched up 1.2% at rank 2, indicating pressure at the top rather than a share handoff. Four of the top ten are Pre-Roll SKUs, and three are Vapor Pens and Infused variants clustered between ranks 3 and 9, pointing to concentration in higher-THC formats even as MoM declines stack up. This pattern implies Nugz (Canada) is leaning into infused and value-led inhalables where rank leadership persists, but September 2026 softness signals the product mix is overdue for freshness to stabilize Pre-Roll and Vapor Pen trajectories.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

