

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Uncle X is stocked at 42 licensed dispensaries across Arizona, with the deepest coverage in Tucson, Phoenix, Mesa, Tempe, and Chandler. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
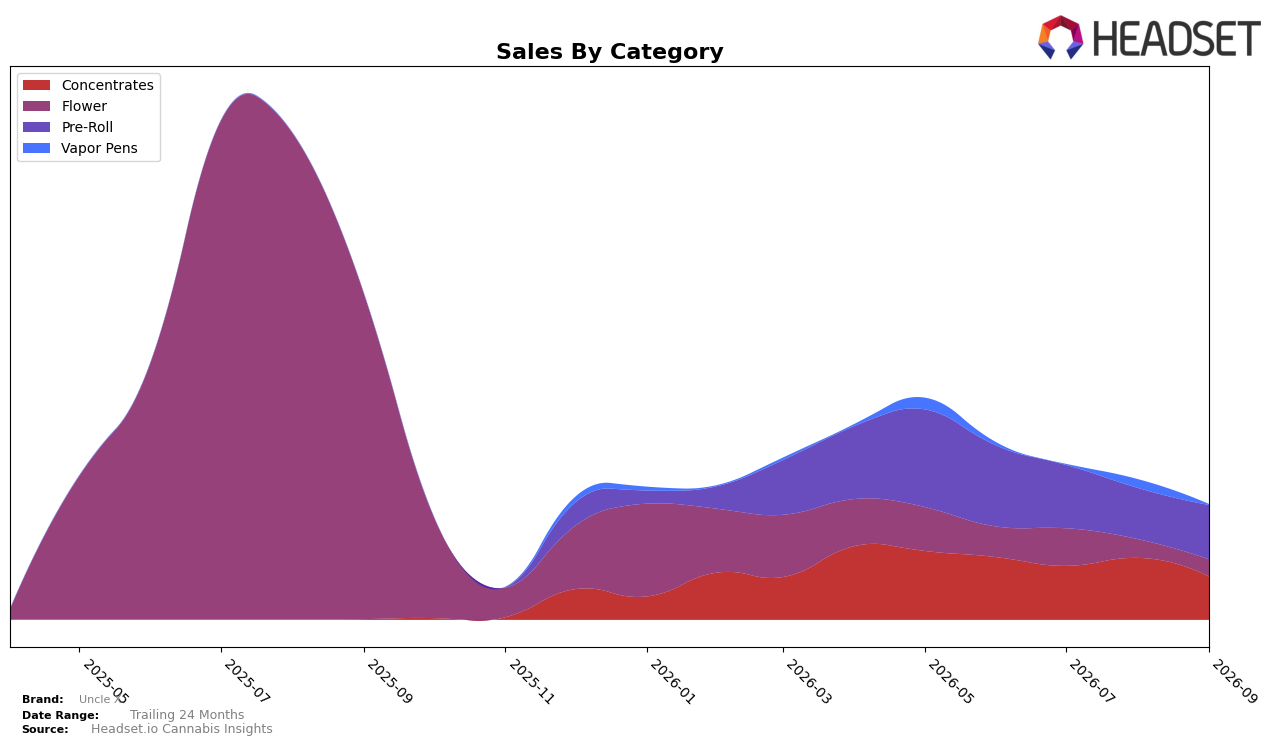
In September 2026, Uncle X’s mix tilted toward Pre-Roll at 47.23% share with a month-over-month gain of 6.04%, while Concentrates held 37.44% share but fell 30.72% MoM; Flower accounted for 14.92% share with a 7.44% MoM decline. Year over year, Concentrates posted 14635.18% growth while Flower dropped 94.76% YoY, against a brand-level sales change of -64.89% YoY and a 41.33% YoY price decline. Within Pre-Roll, the brand held rank 29 in Arizona and averaged $27.53, compared with 16.82 in Vapor Pens where MoM fell 94.44% and share sat at 0.41%. This pattern implies Uncle X is concentrating volume into Pre-Roll and Concentrates to offset steep Flower contraction, but the overall YoY brand decline and price compression signal margin pressure even as category concentration rises.
The mix shift toward Pre-Roll gaining 6.04% MoM and Concentrates losing 30.72% MoM, alongside a 0.41% share residue in Vapor Pens after a 94.44% MoM drop, indicates a narrowing portfolio that trades breadth for depth. With rank 29 in Arizona Pre-Roll and a 94.76% YoY collapse in Flower versus 14635.18% YoY expansion in Concentrates, Uncle X’s positioning is migrating toward value-seeking formats where average prices of $27.53 (Pre-Roll) and $13.44 (Concentrates) can absorb a 41.33% YoY brand-wide price decline. The implication is a defensive tilt: deepen in Pre-Roll to maintain shelf presence while using Concentrates as a volume stabilizer, accepting that a -64.89% YoY brand sales change and a near-exit in Vapor Pens limit cross-category halo and require focused execution where rank and price architecture are most sustainable.
Competitive Landscape
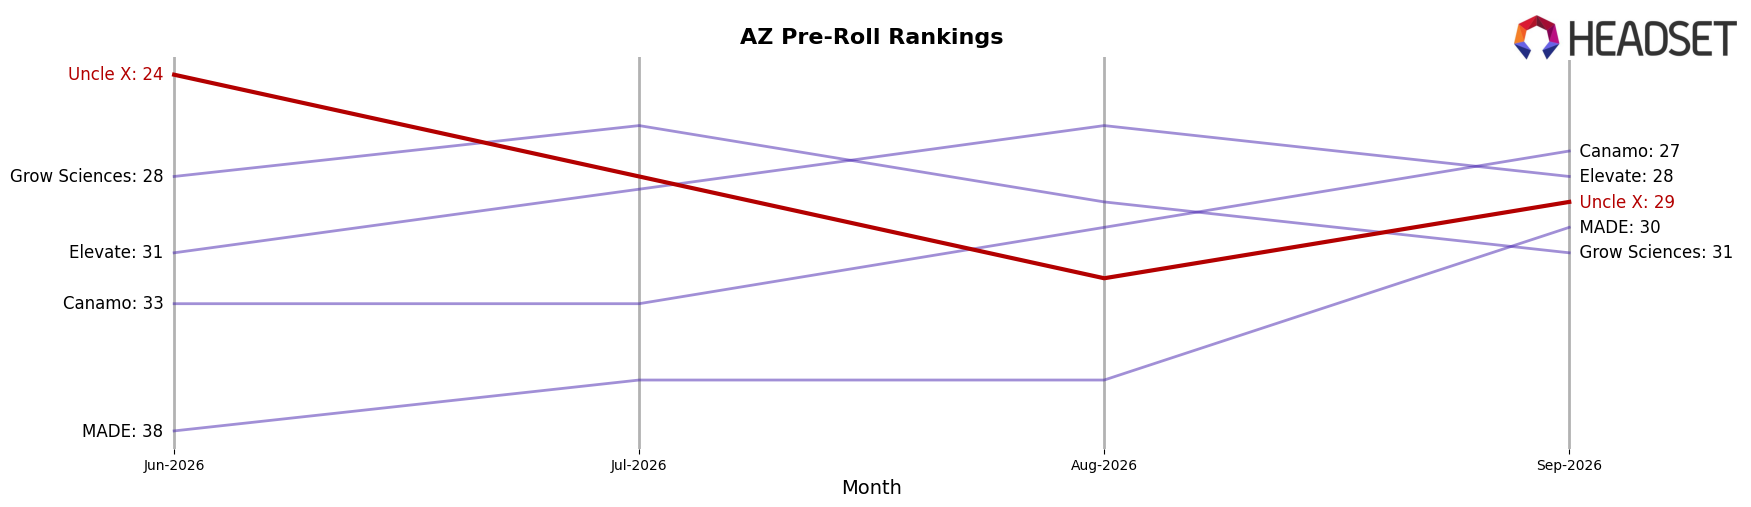
Uncle X sits at rank #29 in AZ Pre-Roll for September 2026, sliding 5 positions from #24 in June 2026 while remaining 7 spots below its peak at #22 in May 2026; in contrast, Jeeter holds #1 with a 16.8% year-over-year sales increase and STIIIZY holds #2 despite a 20.3% year-over-year decline, indicating that category leadership is consolidating even as second place softens. Meanwhile, Dusties stayed at #3 with 187.4% year-over-year growth and Anthem climbed from #39 to #4 on 851.7% year-over-year growth, outpacing Uncle X’s ability to defend share near the mid-20s ranks; this trajectory implies Uncle X is being out-accelerated by rising mid-tier challengers and needs either mix shifts or distribution gains to prevent further drift from the top 25.
Notable Products
Cap Junky Sugar (5g) posted the steepest movement in September 2026 with a -35.5% month-over-month drop and fell to rank 8, implying a sharp pullback in demand for bulk concentrates even as top spots remain dominated by Pre-Rolls. Axilla Pre-Roll 28-Pack (14g) held rank 1 while Chemmy Jones Preroll 14-Pack (7g) sat at rank 3, and four of the top ten are Pre-Roll SKUs, pointing to sustained consumer preference for multi-pack convenience over extract formats. Within concentrates, Black BBGM Badder (2g) slipped -7.3% at rank 5 while Black BBGM Badder (1g) edged down -2.4% at rank 4, indicating relative stability for smaller sizes compared to the heavier decline in larger or premium sugar offerings. The product mix signals Uncle X is skewing toward Pre-Roll multipacks as the commercial backbone, while concentrate strategy may need re-tiering toward smaller grammages and fewer bulk sugar bets.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

