

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Project Packs is stocked at 62 licensed dispensaries across Arizona and New York, 61 of them in Arizona, with the deepest coverage in Tucson, Phoenix, Mesa, Tempe, and Chandler. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
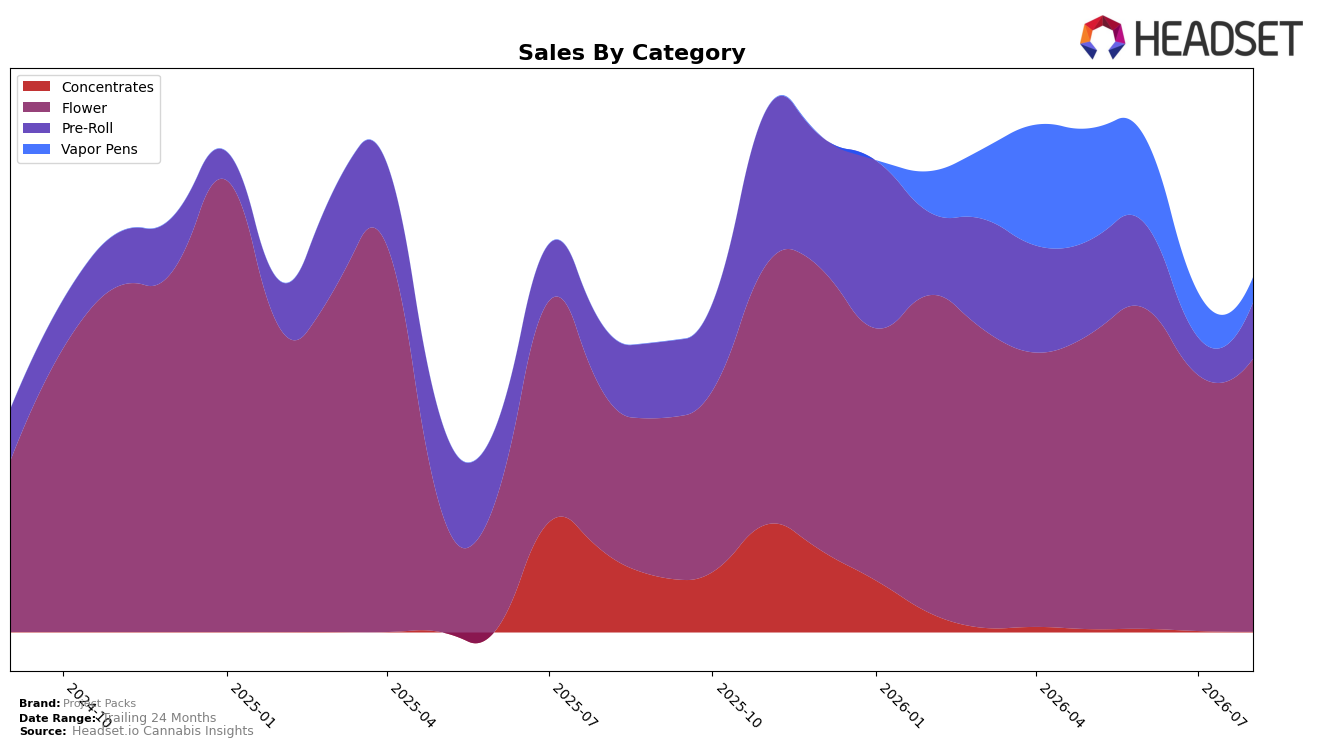
In August 2026, Project Packs concentrated 77.10% of sales in Flower, where year-over-year growth reached 72.63% and month-over-month growth was 6.67%, while Pre-Roll held 15.84% share with a -15.24% year-over-year change but a 49.77% month-over-month jump. Vapor Pens accounted for 7.00% share with a -44.56% month-over-month decline and no year-over-year read, and Concentrates fell to 0.06% share with -99.73% year-over-year and -78.97% month-over-month declines. Average price rose 1.19% year over year to $25.63, with Flower averaging $28.13, implying that mix shift toward higher-priced Flower and a sharp Pre-Roll rebound drove the brand’s 16.34% year-over-year sales increase while de-emphasizing low-volume Concentrates.
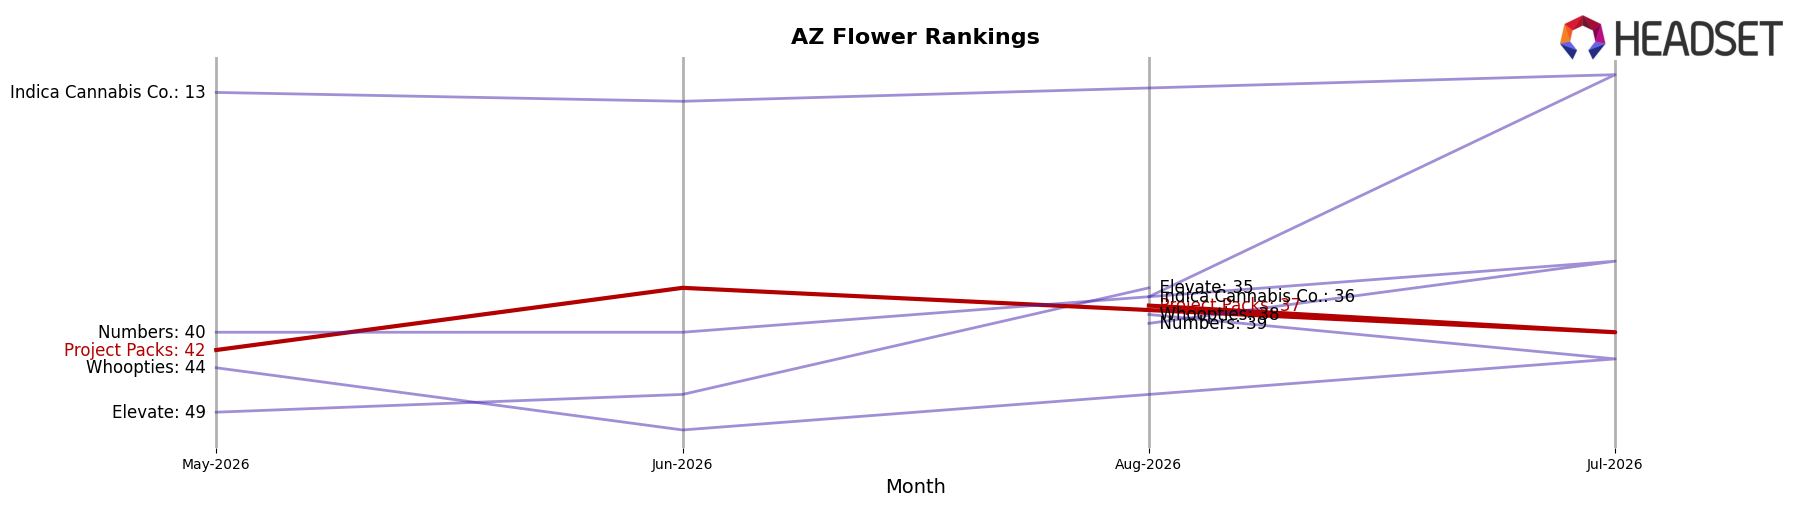
The heavier tilt into Flower coincides with a rank of 37 in Flower in Arizona, and the 49.77% month-over-month surge in Pre-Roll alongside a 6.67% month-over-month gain in Flower suggests a two-tier strategy anchored in a high-growth core and a recovering value entry. With Vapor Pens down 44.56% month over month and Concentrates nearing exit-scale at 0.06% share, the portfolio is consolidating around categories where price acceptance supports the 1.19% average price increase, implying that Project Packs is prioritizing depth in Flower with selective Pre-Roll momentum to stabilize overall share while stepping back from underperforming inhalable niches.
Competitive Landscape
Project Packs sits at rank #37 in August 2026, improving 10 positions year over year from #47, but only 5 positions versus three months ago from #42, indicating a slower recent climb compared to the annual gain. The brand remains below its peak of #34 from January 2025, while Just Flower holds #1 year over year and in August 2026 and Find. moved up from #3 to #2 with 40.0% YoY sales growth, signaling that Project Packs’ rank recovery is occurring amid competitors consolidating higher tiers. With The Pharm jumping from #21 to #5 alongside a 289.6% YoY sales lift and Mohave Cannabis Co. slipping from #2 to #3 despite 12.7% YoY growth, the middle ranks are compressing, implying Project Packs must accelerate beyond a 10-position YoY gain to convert its #37 standing into durable mid-tier placement.
Notable Products
Obsidian (3.5g) posted the standout move in August 2026 with a 90% month-over-month surge to rank 1, while Hidden Pastries (3.5g) fell 35% and dropped to rank 5, and Skidozi (3.5g) declined 28% at rank 10. Pink RTZ (3.5g) rose 35% to secure rank 3, and five of the top ten are Flower SKUs concentrated across ranks 1, 2, 3, 5, and 7, indicating category weight at both the top and middle of the leaderboard. With Obsidian’s gain reshuffling the podium and two Flower SKUs declining by double digits, the product mix signals a pivot toward a single flagship Flower driver with selective support from a few improving mid-tier SKUs, rather than broad-based momentum across the Flower lineup.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

