

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
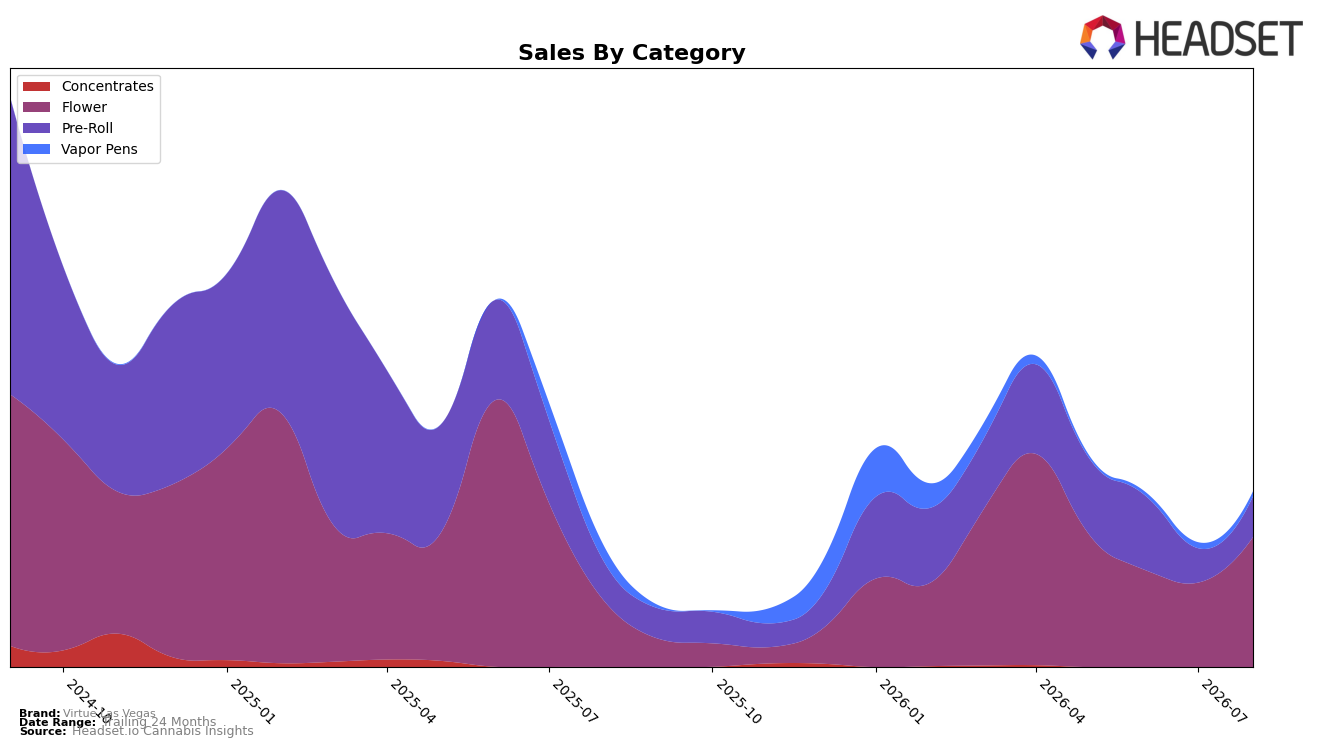
In August 2026, Virtue Las Vegas concentrated 74.11% of sales in Flower, with category sales up 96.96% year over year and 54.13% month over month, while Pre-Roll held 23.12% share with 4.45% YoY growth and 18.54% MoM growth. Vapor Pens contracted to 2.76% share with a -68.71% YoY decline and -15.60% MoM change, even as average price across the brand rose 12.04% YoY and Flower’s ticket averaged $37.35. With overall brand sales up 45.54% YoY yet down 70.78% versus 24 months, the near-term rebound is anchored in Flower momentum and incremental Pre-Roll gains, implying the portfolio is cycling back toward high-weight inhalables while exiting Vapor Pens exposure.
The tilt toward Flower at 74.11% share alongside a 96.96% YoY and 54.13% MoM surge, coupled with Pre-Roll’s 23.12% share and 18.54% MoM growth, indicates a pricing-and-mix strategy prioritizing higher-priced Flower (average $37.35) over lower-priced extensions. Given a rank of 47 in Flower within Nevada and a brand-level 12.04% YoY average price lift, the mix shift suggests an intentional push to regain relevance through core Flower velocity rather than breadth, which may improve rank efficiency if sustained but leaves exposure to category volatility as Vapor Pens continue a -68.71% YoY slide.
Competitive Landscape
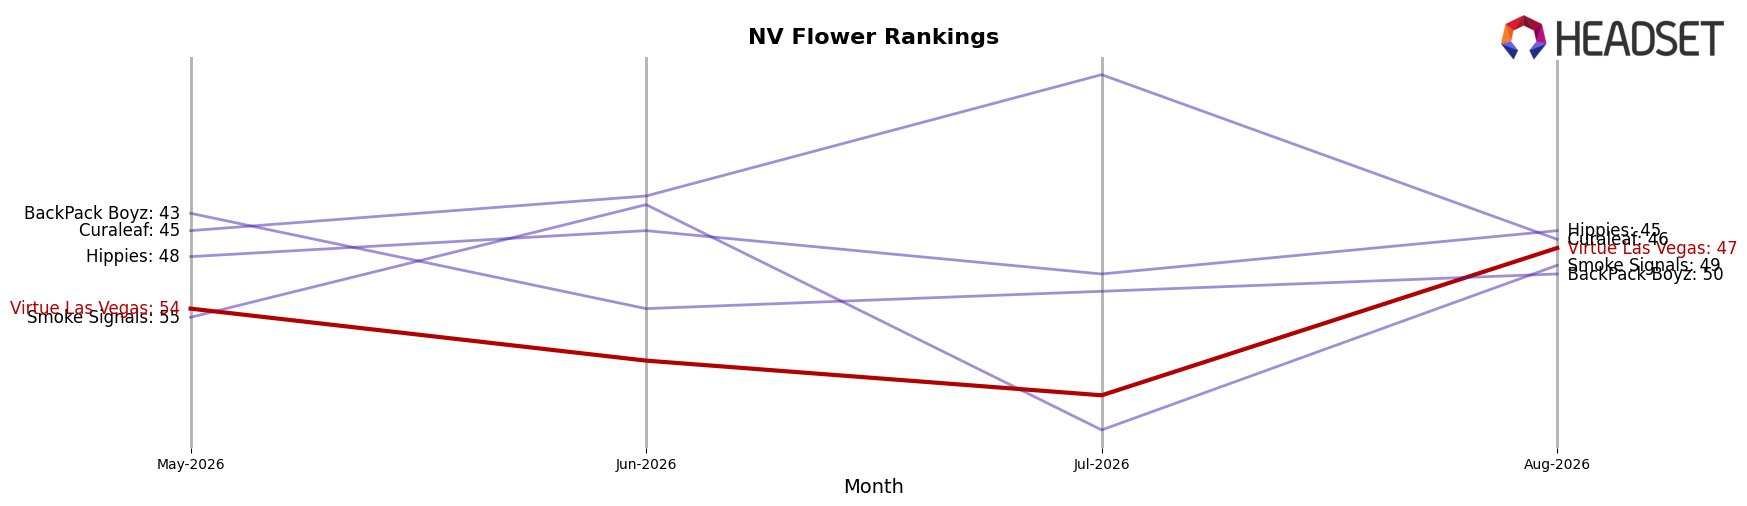
Virtue Las Vegas sits at rank #47 in NV Flower for August 2026, improving 28 positions from #75 year over year, yet slipping 13 spots from #34 since the three-month checkpoint at #54, which indicates volatility around a longer-term climb from its August 2024 peak of #32. In contrast, STIIIZY rose from #2 to #1 with 50.5% YoY sales growth, while RYTHM fell from #1 to #2 despite 4.3% YoY growth, and Redwood jumped from #23 to #5 on 218.1% YoY growth; these shifts suggest Virtue Las Vegas is gaining ground on a yearly basis but losing share against surging leaders in recent months, implying the brand’s trajectory points to mid-tier stabilization rather than a near-term return to its #32 peak.
Notable Products
Diamond Bar Pre-Roll (1g) posted the largest month-over-month gain at +133.3% to rank 4, while Fig Bar Pre-Roll (1g) rose +49.0% to rank 2, indicating momentum concentrated in pre-rolls at ranks 1, 2, 3, 4, 7, 8, and 10. In contrast, Orange Push Pop (3.5g) fell -51.5% to rank 5 and Orange Push Pop Pre-Roll (1g) declined -57.6% to rank 7, even as J1 (3.5g) jumped +96.0% to rank 6 and Lemon Cherry Gelato Pre-Roll (1g) advanced +39.9% to rank 10. The mix shows pre-rolls outpacing flower in rank density and growth rate, implying Virtue Las Vegas is tilting assortment and demand capture toward impulse-friendly pre-roll formats over bulk flower despite isolated flower rebounds.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

