

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Packs (fka Packwoods) is stocked at 370 licensed dispensaries across Colorado, Missouri, and 11 other states, 114 of them in Colorado, with the deepest coverage in Denver, Colorado Springs, Aurora, Commerce City, and Northglenn. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
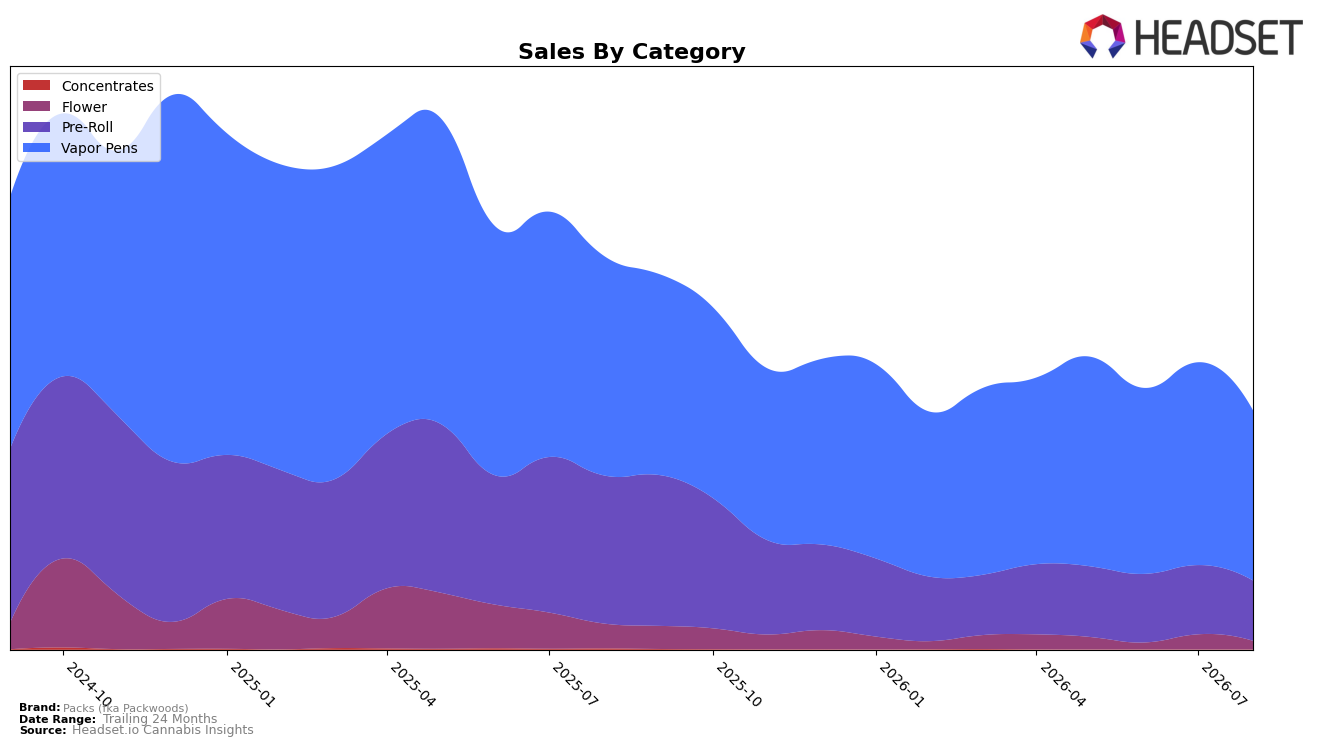
In August 2026, Packs (fka Packwoods) concentrated 71.36% of sales in Vapor Pens with a year-over-year decline of 22.71% and a month-over-month drop of 16.36%, while Pre-Roll held 25.20% share with a steeper 59.52% YoY and 13.13% MoM contraction. Flower is now a marginal 3.44% of mix after a 66.72% YoY and 44.95% MoM slide, coinciding with a brand-wide average price down 31.49% YoY and total sales down 39.52% YoY. The overall pattern points to a consolidation around Vapor Pens despite cross-category contraction, implying fewer growth levers as secondary categories retreat faster than the core.
These shifts imply a positioning anchored in Vapor Pens, where a rank of 13 in Colorado indicates mid-pack visibility but with vulnerability if the 16.36% MoM decline persists alongside a 25.20% reliance on Pre-Roll that is falling 59.52% YoY. The sharper 44.95% MoM deterioration in Flower and a 31.49% YoY price reduction suggest a discount-led stance that has not offset the 39.52% YoY sales contraction, so sustaining relevance likely depends on stabilizing Vapor Pens velocity while treating Pre-Roll and Flower as tactical, not foundational, contributors.
Competitive Landscape
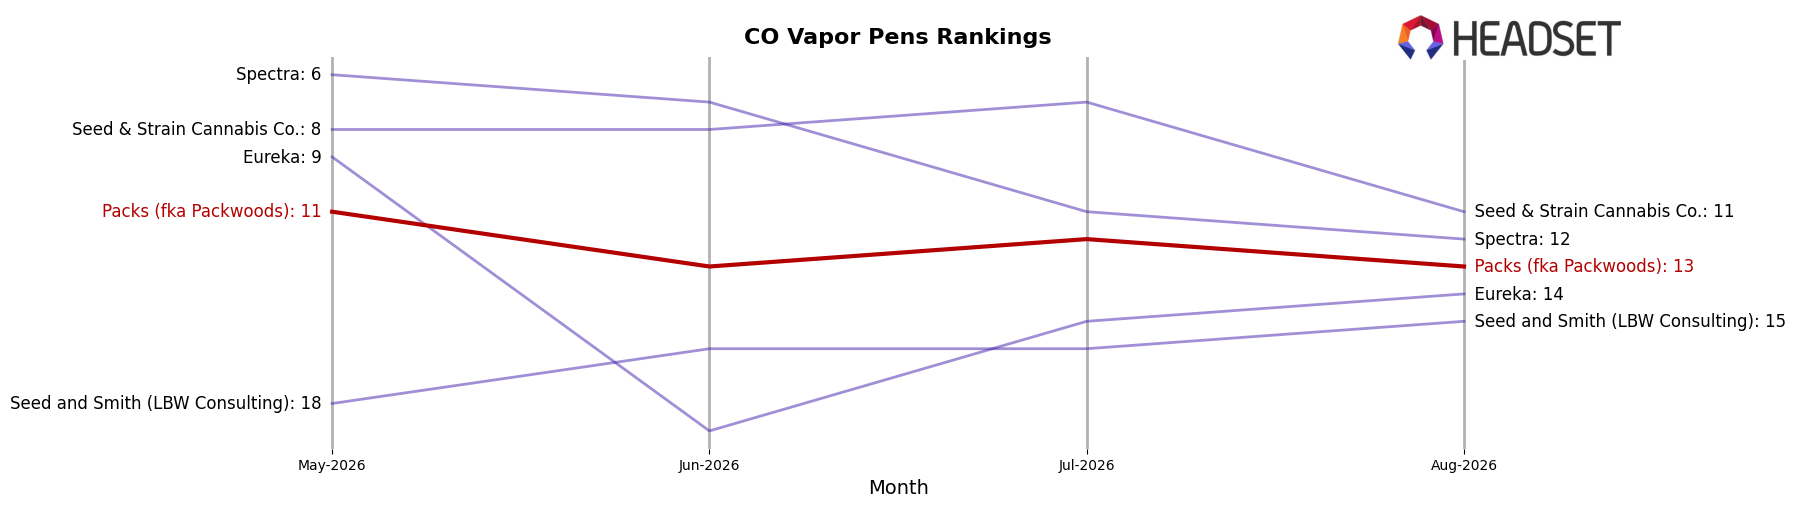
Packs (fka Packwoods) sits at rank #13 in CO Vapor Pens in August 2026, slipping 1 position year over year from #12 while also falling 2 spots from #11 in May–July to #13 in August, against a historical peak of #6 in May 2025. In contrast, Spherex held #1 both this year and last year while growing sales 10.3% year over year, and Batch Extracts moved up from #4 to #2 with a 72.9% YoY sales increase, indicating competitive momentum is concentrating at the top. With Jetty Extracts rising from #6 to #4 alongside 56.2% YoY sales growth and Green Dot Labs advancing from #8 to #5 with 58.5% YoY growth, the mid-to-upper tier is compressing upward while Packs (fka Packwoods) drifts downward by 1 rank YoY and 2 ranks versus three months prior; this trajectory implies share is being ceded to faster-advancing incumbents, and recovery would require reversing multi-period rank declines rather than a single-month rebound.
Notable Products
Black Cherry Gelato Live Resin Distillate Packspod Mini Disposable (1g) posted the largest movement in August 2026 with a +51.0% month-over-month surge that carried it to rank 1, while Unicorn Sherbet Live Resin Packspod Disposable (2g) fell -17.8% to rank 3. Jelly Dulce Live Resin Distillate Packspod Disposable (1g) dropped -30.9% at rank 4 as Blue Slurpee Live Resin Packspod Disposable (2g) slid -16.5% at rank 5, indicating share is rotating from 2g SKUs toward Minis at the very top of the chart. With nine of the top ten products in Vapor Pens and at least four 2g Packspod entries sitting at ranks 3, 5, 9, and 10 amid double-digit declines of -17.8% and -26.8%, the mix signals a pivot toward 1g Minis that can win rank positions 1 and 2 on smaller volume and tighter price points, with top-line supported by a single high-volume 2g SKU at $105,753.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

