


Where to Buy
Vital is stocked at 45 licensed dispensaries across Arizona and PR, 31 of them in Arizona, with the deepest coverage in Phoenix, Tucson, Flagstaff, Kingman, and Mesa. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
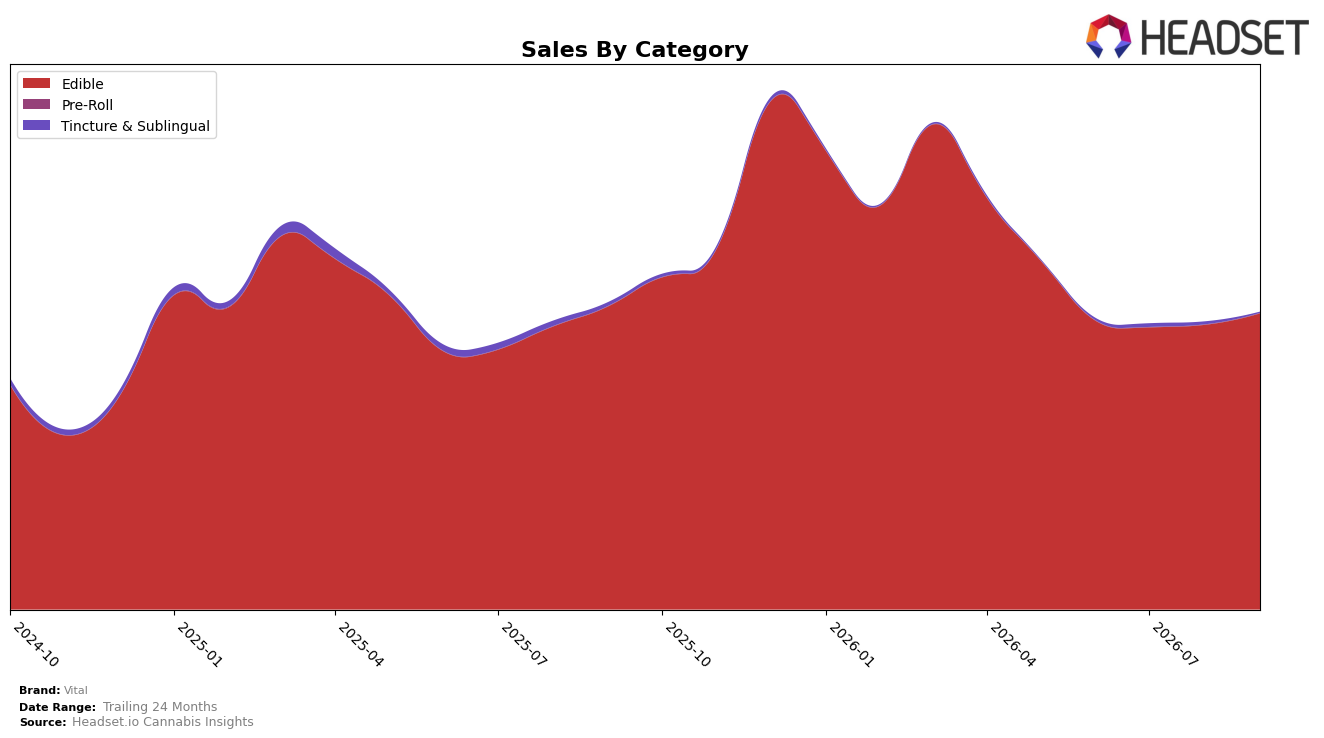
In September 2026, Vital remained concentrated in Edible with a 99.73% sales share, while Tincture & Sublingual held 0.27% and fell 68.10% month over month. Edible sales grew 4.03% MoM but declined 2.33% year over year, aligning with a brand-level YoY drop of 3.15% alongside a 6.03% YoY decrease in average price; this suggests unit growth cushioning revenue pressure. With Tincture & Sublingual down 76.30% YoY and Edible carrying nearly all volume, Vital’s category skew indicates reliance on a single demand pool that benefited from September’s MoM uptick but did not offset the annual price and revenue compression.
These shifts imply that Vital’s positioning hinges on value-priced Edible, where a 4.03% MoM sales lift coincides with lower YoY pricing of 6.03%, pointing to price elasticity that can drive units without expanding category breadth. Holding rank 13 in Edible within Arizona while Edible’s share sits at 99.73% and Tincture & Sublingual contracts 68.10% MoM suggests the path to sustained rank improvement is deeper penetration within Edible rather than diversification; the mix indicates that even modest share gains in a single category can outweigh attempts to revive a sub-1% segment.
Competitive Landscape
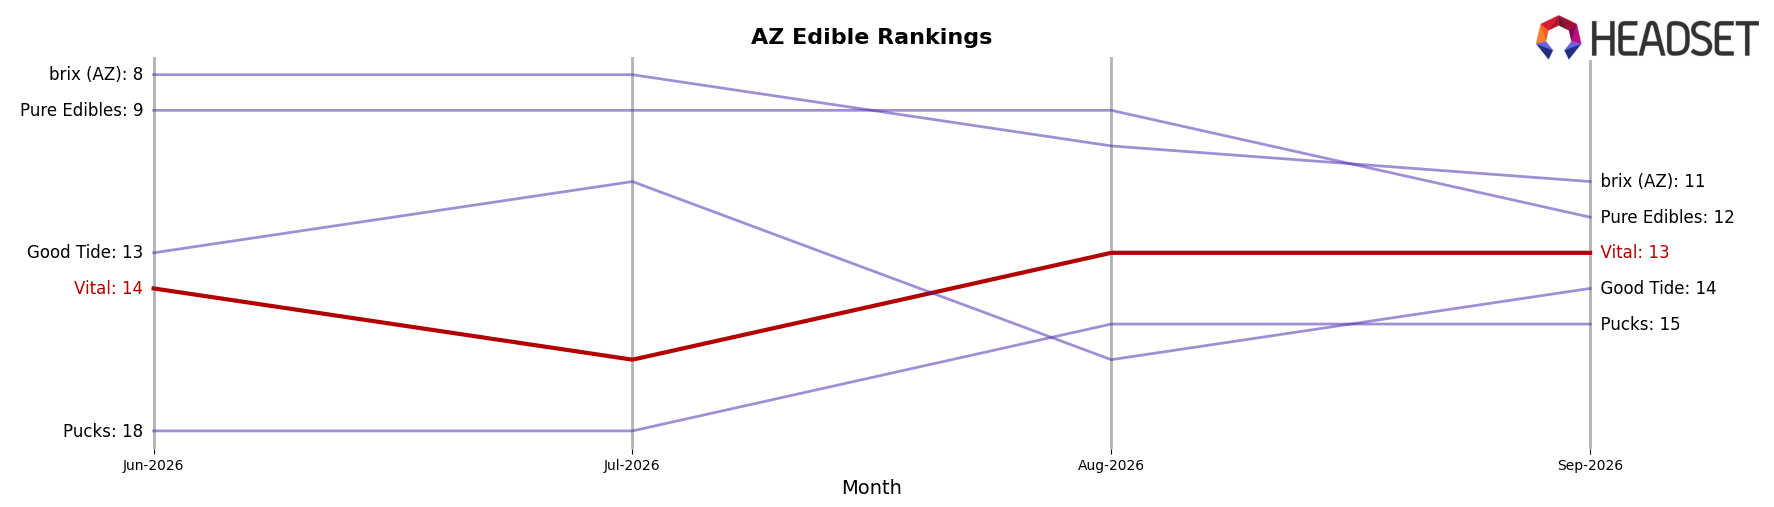
Vital sits at rank 13 in AZ Edible for September 2026, down 1 position year over year from rank 12 and up 1 spot versus June 2026 when it was 14, while still trailing its peak rank of 8 from December 2025 by 5 places; in contrast, Wyld held at rank 1 year over year despite a -16.2% sales change and Baked Bros climbed from rank 4 to rank 2 alongside a +22.5% sales change. With OGEEZ sliding from rank 2 to rank 3 amid a -8.0% sales change and Gron / Grön easing from rank 3 to rank 4 with a -4.8% sales change, the category’s top tier is rotating even as Wana holds rank 5 year over year with +14.4% sales growth; this mix of upward and downward moves implies Vital’s slight rank erosion is less about broad market contraction and more about intensified share capture by mid‑top competitors, signaling a need to re-engage toward the 8–10 band reclaimed from December 2025.
Notable Products
Watermelon Pectin Gummies 10-Pack (100mg) posted the sharpest movement in September 2026 with a +90.9% month-over-month surge and a rank at 8, while Grape Fast Acting Gummies 10-Pack (100mg) fell -83.4% MoM yet remained rank 1. Tropical Mango RSO Gummies 10-Pack (100mg) grew +278.5% MoM to rank 2, compared with Indica Sour Blue Raspberry Pectin Gummies 10-Pack (100mg) down -6.9% at rank 7. With all top ten slots belonging to Edible SKUs and only one product above $30,000 in sales, the mix points to a pivot toward breadth in flavors and formats over dependence on a single fast-acting leader.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

