


Where to Buy
Voon is stocked at 27 licensed dispensaries across Alaska and Nevada, 15 of them in Alaska, with the deepest coverage in Anchorage, Soldotna, Fairbanks, Big Lake, and Sterling. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
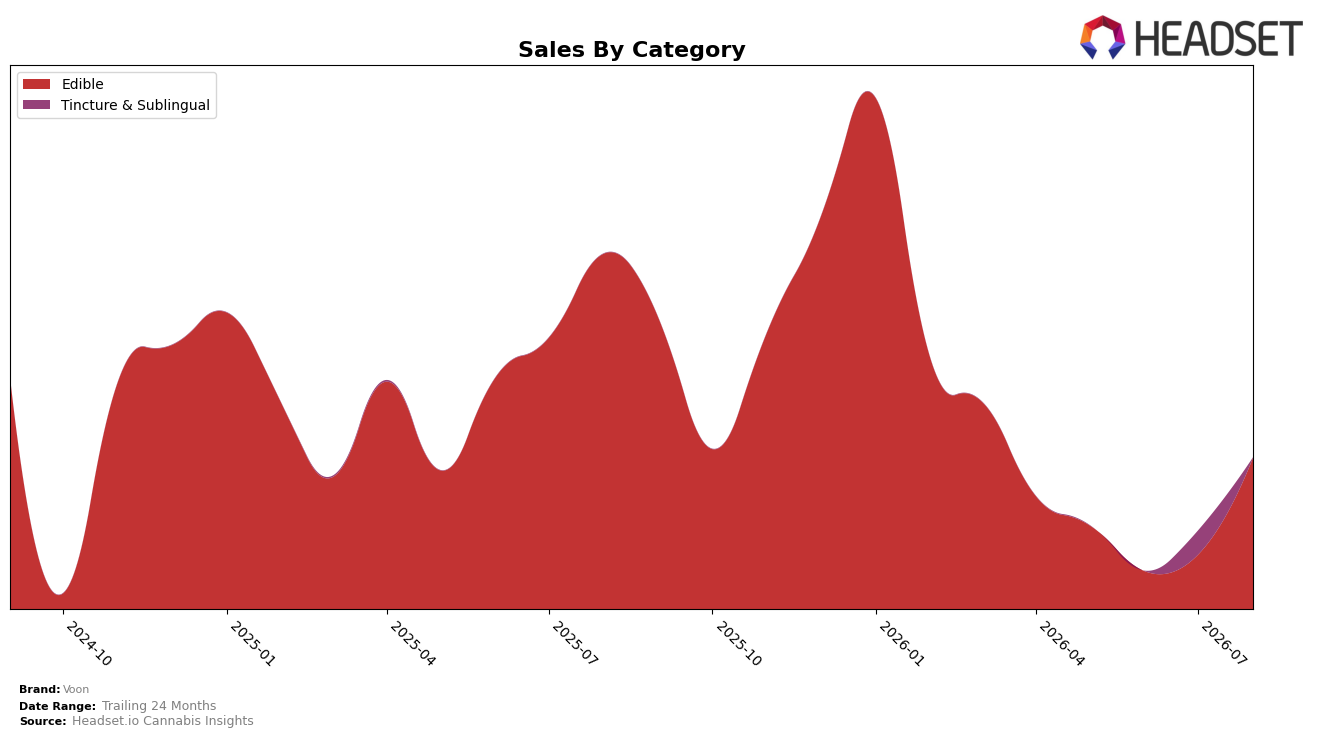
In August 2026, Voon’s mix concentrated entirely in Edible at 100.0% share, with year-over-year sales down 57.5% while month-over-month sales rose 180.5%; the category held a rank position of 30 in Nevada, pairing a 23.99% YoY increase in average price with a full-category allocation that leaves no diversification headroom. The combination of a 100.0% category share and a 30th rank suggests that August 2026 gains were tactical and price-led rather than mix-driven, implying that recovery depends on sustaining the 180.5% MoM momentum without eroding the rank standing in Nevada.
The move toward a single-category footprint amplifies sensitivity to Edible pricing and seasonal volatility: a 23.99% YoY price lift alongside a 57.5% YoY sales decline indicates elasticity pressure, while the 180.5% MoM rebound hints at promotional or distribution timing effects rather than broad demand expansion. With average price at $26.32 and rank at 30, the pattern implies that Voon’s positioning in August 2026 skews toward selective, price-elevated placements that can spike volume month-to-month but risk longer-term share attrition if the 100.0% category reliance persists.
Competitive Landscape
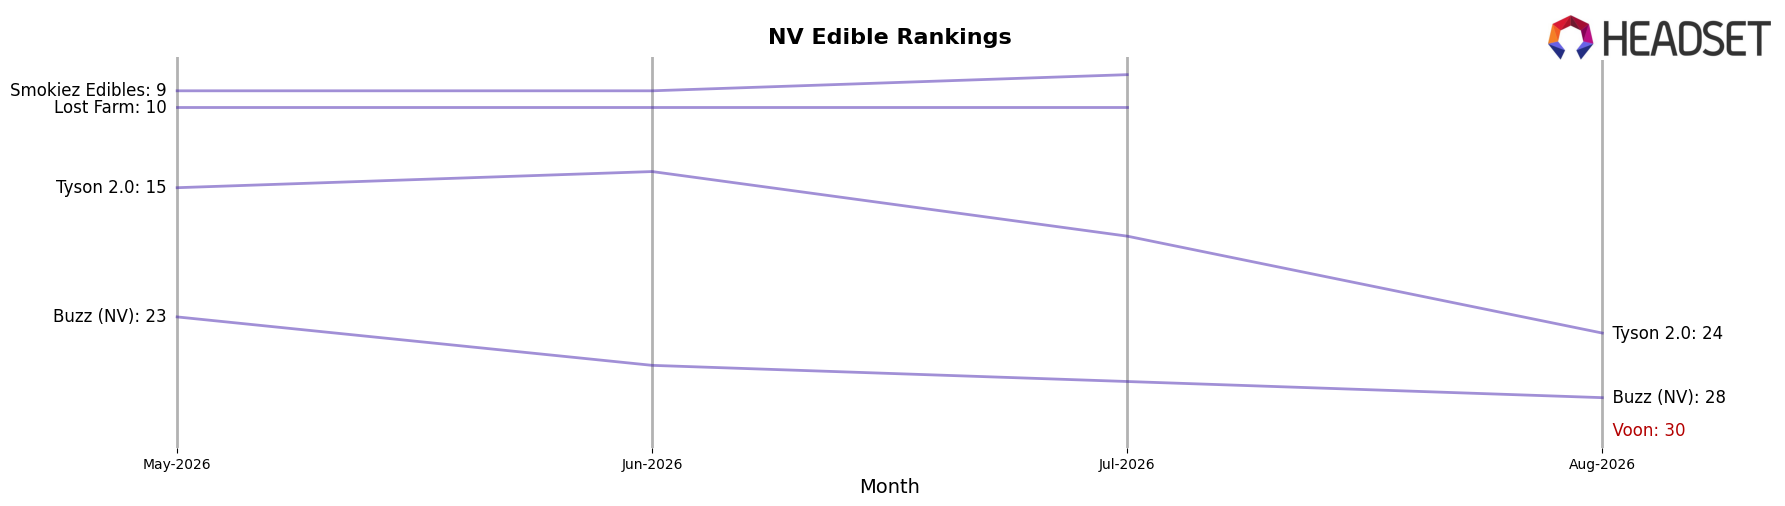
Voon sits at rank #30 in NV Edible in August 2026, down 6 positions from #24 year over year, though it is 4 spots better than its three-month position of #34, while its peak at #24 in January 2026 frames the longer slide; in contrast, Wyld held #1 both year over year and currently despite a 15.5% sales decline, and Kanha / Sunderstorm advanced from #10 to #3 on 201.9% YoY sales growth. These splits imply Voon is losing relative placement as faster movers climb, with stabilization versus three months ago insufficient to counter a six-rank YoY drop.
Notable Products
GDP Sublingual 10-Pack (200mg) delivered the standout movement in August 2026 with a +946.9% MoM surge to rank 1, while Fresh Wintergreen Trainwreck Sublingual 10-Pack (200mg) followed with +757.0% MoM at rank 2, indicating a sharp pivot toward sublingual formats. In contrast, Super Lemon Haze Chocolate 10-Pack (200mg) fell -24.3% MoM at rank 3 and Grand Daddy Purple Chocolate 10-Pack (200mg) dropped -58.4% MoM at rank 4, and with three of the top five being Edible chocolates, the hierarchy is consolidating around just a few winners rather than broad chocolate strength. Trainwreck Chocolate Pouch 10-Pack (200mg) declined -40.6% MoM at rank 5 while the two sublingual SKUs now occupy the top two ranks, implying a migration of demand from chocolate edibles toward faster-acting sublinguals. This mix suggests Voon’s commercial direction is shifting toward efficacy-led sublingual offerings as the growth engine while legacy chocolate lines retrench.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

