

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
WEED. is stocked at 25 licensed dispensaries across Michigan, with the deepest coverage in Grand Rapids, Muskegon, Allegan, Ann Arbor, and Big Rapids. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
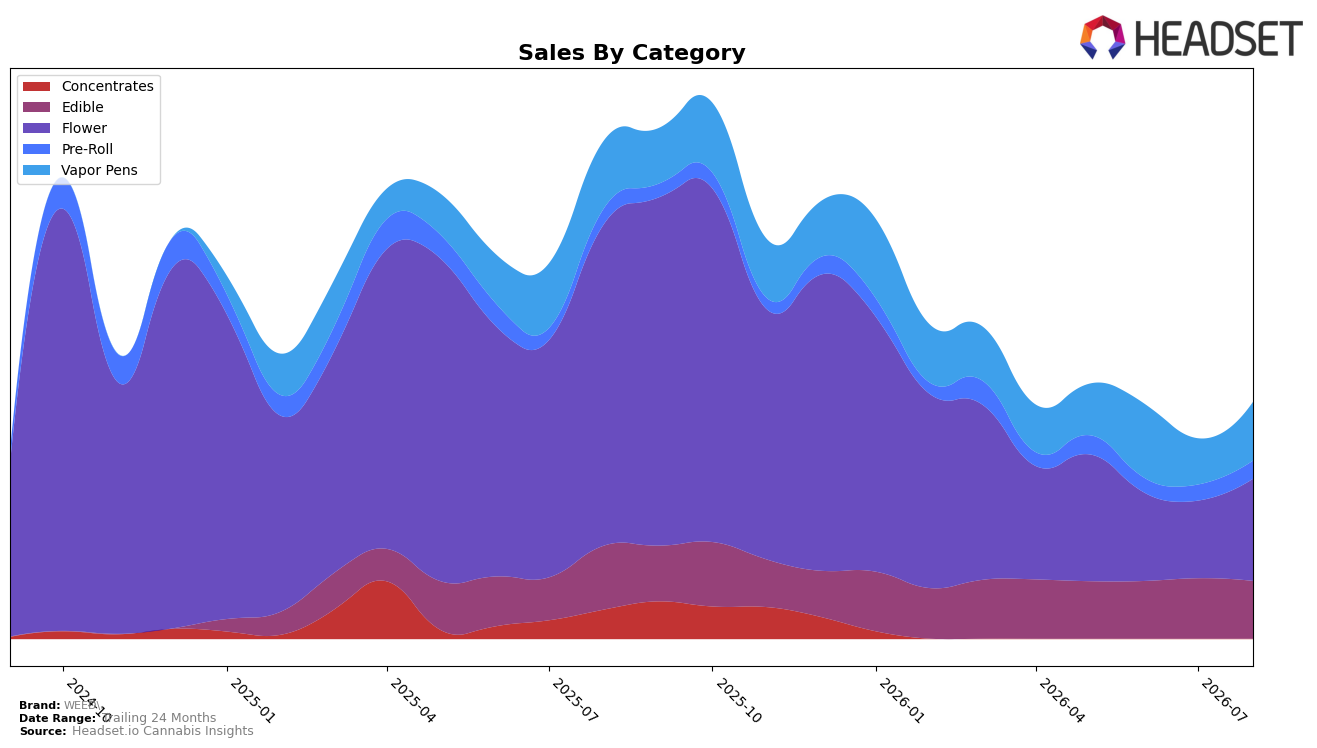
WEED. concentrated 43.22% of August 2026 sales in Flower and 24.83% in Vapor Pens, with Edible close behind at 24.40%, indicating a three-pillar mix that shifted toward inhalables month over month. Flower sales rose 31.80% MoM but fell 68.33% YoY, while Vapor Pens increased 27.44% MoM with a milder 13.36% YoY decline; in contrast, Edible slipped 4.51% MoM against a 9.60% YoY drop. Pre-Roll, at 7.56% share, grew 13.41% MoM and 15.36% YoY off a lower base. With average price down 44.12% YoY and brand sales down 52.62% YoY, the mix tilting toward Flower and Vapor Pens implies the brand is using price-led volume recovery in inhalables to counter Edible softness and stabilize share concentration.
In Vapor Pens, WEED. ranked 74 in Michigan, a position that, combined with a 27.44% MoM sales lift and 24.83% category share within the brand’s own mix, signals mid-pack presence locally but reliance on intra-brand mix shifts rather than rank gains. The concurrent 31.80% MoM Flower increase and 13.41% MoM Pre-Roll growth, paired with a 4.51% MoM Edible decline, points to a pivot toward faster-turn inhalables; the implication is a positioning bet on price-elastic, impulse-friendly formats to regain velocity, while the 15.36% YoY Pre-Roll rise suggests an entry point to trade up from Edible without pressuring Vapor Pen rank.
Competitive Landscape
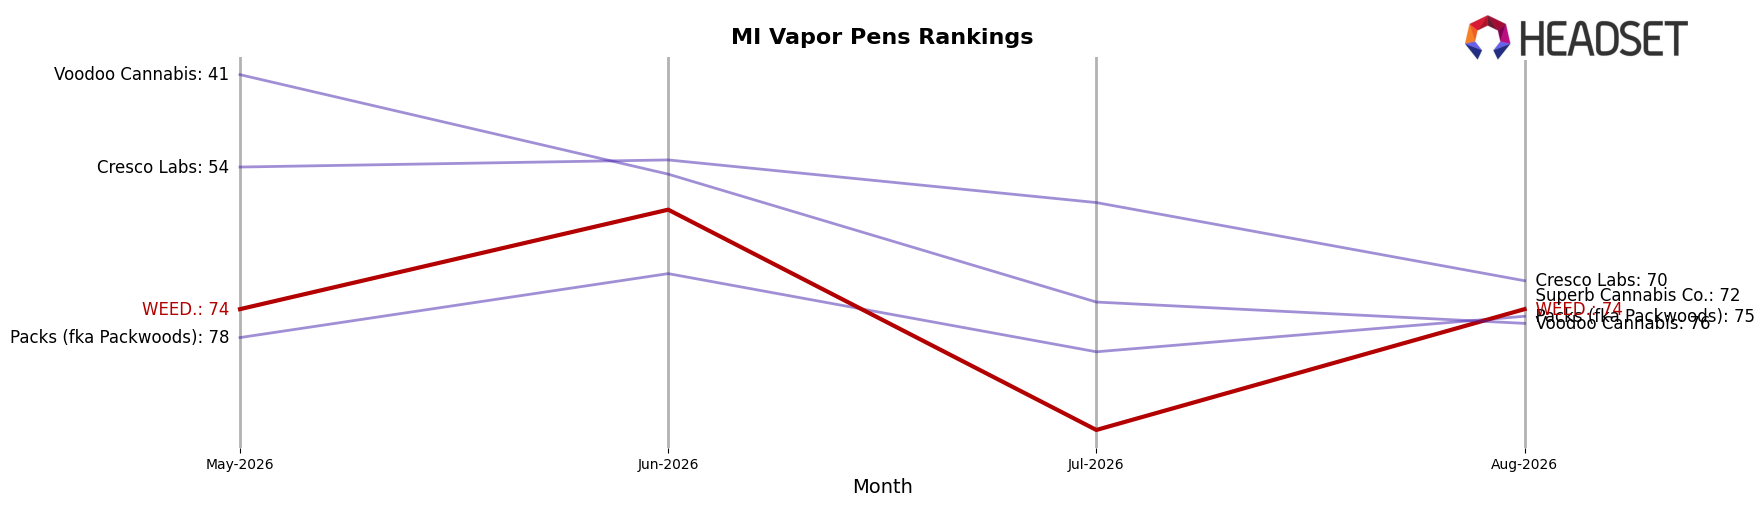
WEED. sits at rank #74 in MI Vapor Pens in August 2026, down 4 spots year over year from #70, with a flat trajectory versus three months ago at #74; by contrast, MKX Oil Company moved up from #2 to #1 while posting a 24.7% YoY sales gain, and Society C vaulted from #16 to #4 alongside a 321.3% YoY sales increase, indicating that WEED.’s slide from a peak of #53 in January 2026 to #74 now coincides with competitors accelerating upward and implies that, without a rank recovery, shelf visibility and velocity are likely to erode further.
Notable Products
WEED.'s steepest movement in August 2026 was the decline of Wild Cherry Gummies 10-Pack (200mg), down 30.16% MoM at rank 6, while Watermelon Punch Gummies 10-Pack (200mg) also fell 25.63% at rank 5; by contrast, Fruit Punch Gummies 10-Pack (200mg) rose 13.79% to hold rank 1. Pineapple Express Pre-Roll (1g) climbed 42.12% to rank 2 as Frozen Dessert Pre-Roll (1g) advanced 25.71% at rank 8, indicating Pre-Rolls are gaining share against Edibles concentrated across seven of the top ten SKUs. The Vapor Pens entry Baja Blast Distillate Cartridge (1g) increased 23.76% at rank 10 while Blue Razz Gummies 10-Pack (200mg) slipped 5.03% at rank 4, suggesting category breadth is cushioning Edible volatility. The pattern implies WEED. is pivoting from an Edibles-heavy mix toward a more balanced portfolio where accelerating Pre-Rolls and an expanding Vapor Pens presence offset softness in legacy gummy flavors, with the top spot anchored by an Edible that can fund experimentation at approximately $22,995 in August 2026.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

