

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
The Limit is stocked at 143 licensed dispensaries across Michigan and Oregon, 140 of them in Michigan, with the deepest coverage in New Buffalo, Lansing, Monroe, Grand Rapids, and Detroit. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
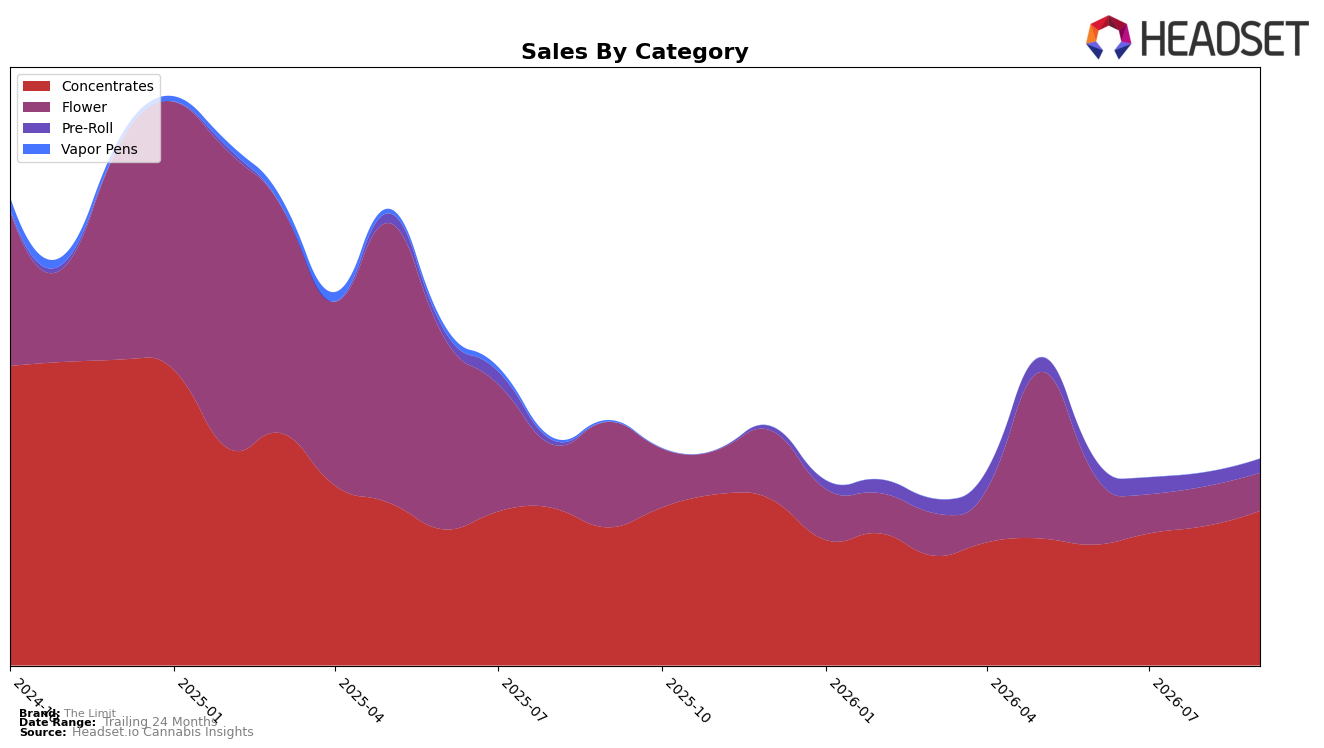
The Limit entered September 2026 with a category mix concentrated in Concentrates at 74.92% share and a category rank of 2 in Michigan Concentrates, while overall brand sales were down 15.69% year over year and average price fell 6.84%. Within categories, Concentrates grew 11.91% YoY and 10.94% MoM, offsetting a 64.08% YoY decline and 4.06% MoM drop in Flower, as Pre-Roll expanded its tiny base with a 264,917.61% YoY spike and a 0.09% MoM uptick to 6.76% share. The pattern implies unit-led gains in Concentrates are stabilizing the portfolio despite price compression and Flower contraction, keeping The Limit anchored near the top of the Concentrates ranking while narrowing reliance on a shrinking Flower line.
Mix shifts indicate a pivot toward higher-velocity Concentrates, where a double-digit MoM lift of 10.94% and an 11.91% YoY rise contrast with Flower’s 64.08% YoY drop and 4.06% MoM erosion, while Pre-Roll’s 6.76% share now provides incremental breadth. With average price down 6.84% alongside a 24‑month sales decline of 57.96%, the brand’s second-place rank in Michigan Concentrates signals that price-sensitive demand is consolidating in its core format and that future positioning rests on defending Concentrates share while converting Pre-Roll’s outsized YoY growth into durable contribution. The implication is that maintaining rank in Concentrates and selectively scaling Pre-Roll can counteract Flower attrition and mitigate brand-level YoY sales pressure.
Competitive Landscape
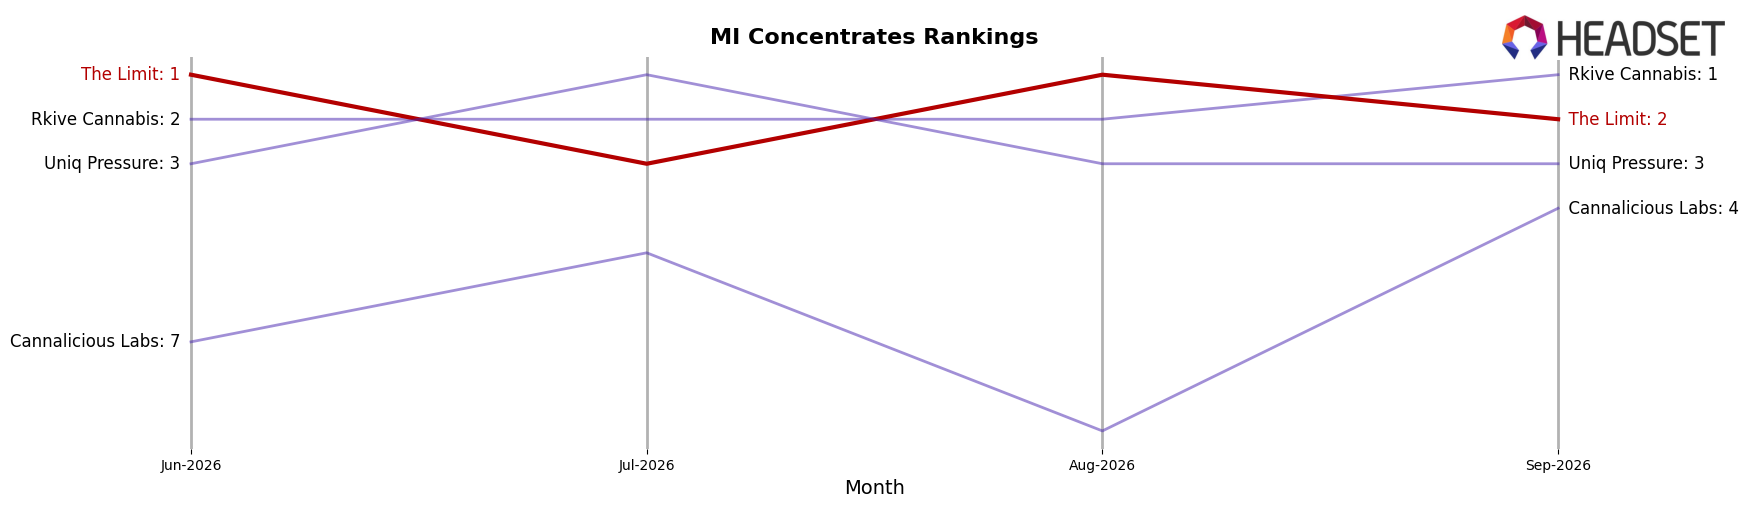
The Limit sits at rank #2 in MI Concentrates in September 2026, down 1 position year over year, after peaking at #1 in August 2026 and slipping from #1 three months ago to #2 now; meanwhile, Rkive Cannabis holds #1 after improving from #3 year over year with a 130.9% sales increase, and Uniq Pressure advanced to #3 from #96 year over year with a 2,216.9% sales surge, while Cannalicious Labs sits at #4 with a 38.5% decline; this mix of rapid ascents and contractions indicates that The Limit’s slight YoY rank slippage in September 2026 points to rising competitive pressure at the very top, implying that holding share will require countering faster-growing rivals rather than broad market headwinds.
Notable Products
Apple Fritter (28g) posted the largest month-over-month surge at 59.9% to rank 5, while Blue Raspberry Slushie Live Resin (5g) rose 55.4% to rank 2, signaling a pivot where outsized gains are split between bulk Flower and high-gram Concentrates. Super Boof (14g) held rank 1 with a modest 4.8% gain as Durban Poison Live Resin (1g) slipped 6.9% at rank 10, and six of the top ten are Concentrates, indicating assortment gravity tilting toward extracts despite a Flower leader. The mix suggests The Limit is leaning into higher-volume formats and live resin depth to capture momentum beyond a single flagship, aligning pricing power in bulk Flower with rising demand for 5g Concentrates.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

