

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
White Label Extracts (OR) is stocked at 235 licensed dispensaries across Oregon and Michigan, 234 of them in Oregon, with the deepest coverage in Portland, Eugene, Salem, Bend, and Medford. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
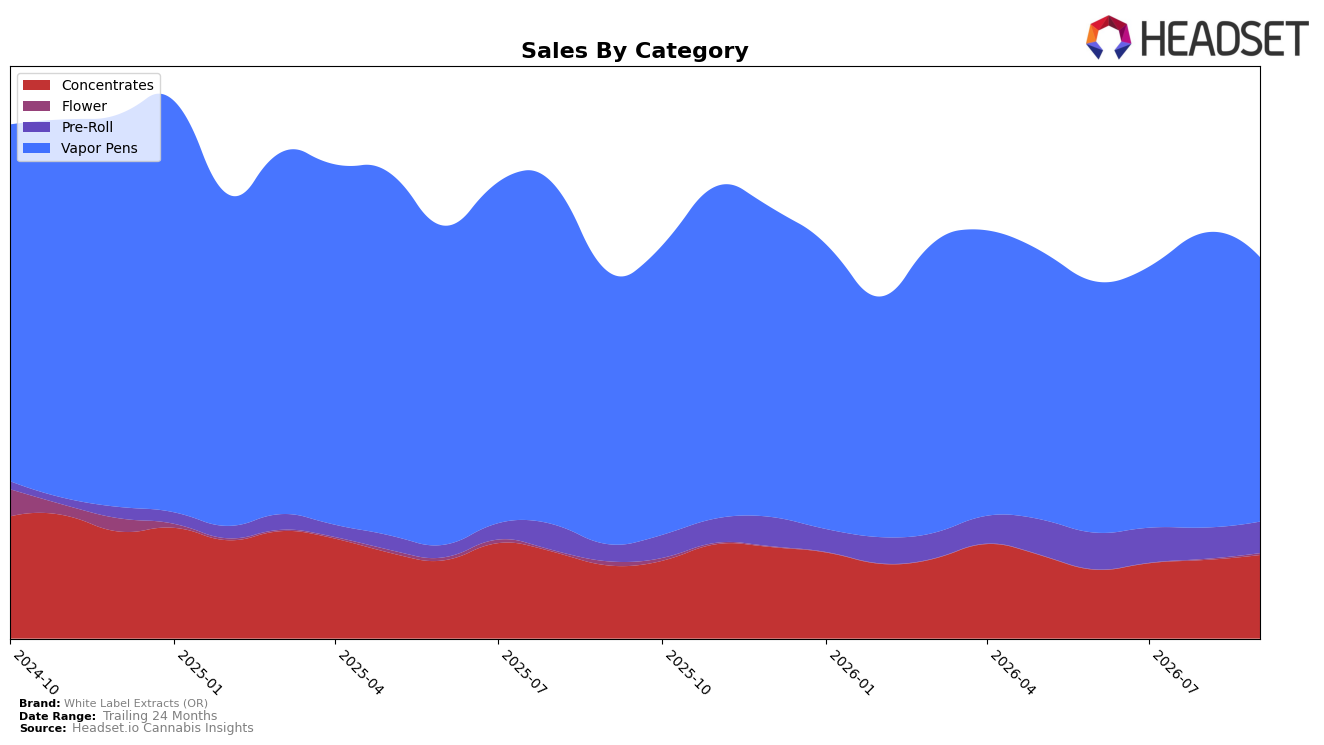
In September 2026, White Label Extracts (OR) concentrated 69.51% of sales in Vapor Pens while holding rank 10 in Oregon Vapor Pens; within that anchor, Vapor Pens declined 2.93% year over year and 10.32% month over month, contrasting with Concentrates at 21.90% share growing 14.31% YoY and 6.32% MoM. The remaining mix shifted at the edges: Pre-Roll rose 85.84% YoY on an 8.19% share with a modest 0.59% MoM uptick, and Flower, though only 0.39% share, jumped 126.69% MoM after a 59.58% YoY drop; combined with a 16.32% YoY decrease in average price to $17.90 and brand-level sales up 4.01% YoY but down 27.68% versus 24 months, the pattern implies the brand is offsetting Vapor Pen softness by leaning into faster-growing, lower-price segments.
The mix and timing suggest a deliberate hedge: exposure is still concentrated in Vapor Pens at 69.51% while the category rank sits at 10, yet the 6.32% MoM gain in Concentrates and 0.59% MoM gain in Pre-Roll indicate near-term volume capture where price points are lower (category average prices at $17.37 for Concentrates and $8.92 for Pre-Roll) as the flagship Vapor Pen average price sits higher at $20.69. With Pre-Roll up 85.84% YoY and Concentrates up 14.31% YoY versus a 2.93% YoY decline in Vapor Pens, the implication is a pivot toward value-led formats to stabilize share and defend positioning in Oregon while preserving relevance in Vapor Pens rather than chasing rank gains in a contracting month.
Competitive Landscape
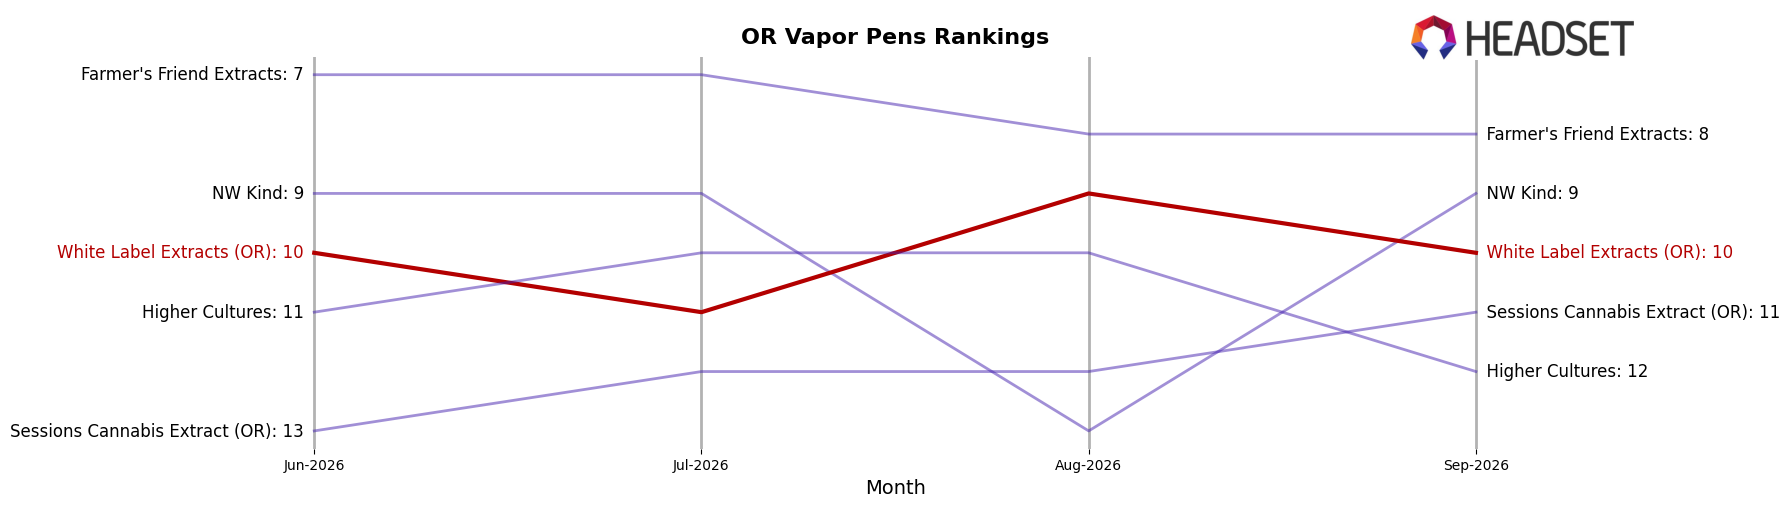
White Label Extracts (OR) ranks #10 in Oregon Vapor Pens in September 2026, unchanged from #10 in September 2025, and flat versus #10 in June 2026, while its historical peak was #3 in December 2024. Among competitors, Entourage Cannabis / CBDiscovery held #1 year over year but with a -15.2% sales change, whereas FRESHY climbed from #5 to #3 alongside a +5.1% sales change; in contrast, Hellavated slid from #3 to #5 with a -6.1% sales change. The combination of a stable #10 rank year over year and quarter over quarter, plus competitors shifting up and down within the top 5, implies White Label Extracts (OR) is holding share at a mid-table position but not converting category volatility into upward rank mobility.
Notable Products
Permafrost x Where's My Bike Live Resin Infused Pre-Roll (1g) delivered the headline move in September 2026 with an 82.3% month-over-month jump and a climb to rank 1, while Vapor Pens concentrated in the top 10 at ranks 2, 5, and 7, indicating a two-category pull at the top. Bubblegum Bonkers Live Resin Cartridge (1g) held rank 2 as Strawberry Candy Cured Resin Cartridge (1g) sat at rank 5, positioning Vapor Pens as a volume counterweight to the pre-roll surge even as the top pre-roll posted the largest gain; together, these placements suggest portfolio momentum is split between an upswing in infused pre-rolls and steady pen demand. With Pre-Rolls also occupying ranks 3, 4, 6, 8, and 9, the clustering across five additional top-10 slots points to assortment depth that can absorb volatility, and the presence of Burger Drip THCa Sugar (2g) at rank 10 with $11,616 implies a secondary bet in Concentrates. The pattern implies White Label Extracts (OR) is leaning into infused pre-rolls for share capture while maintaining Vapor Pens as a stabilizing second pillar, setting up a two-lane strategy rather than a single-category bet.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

