

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeMarket Insights Snapshot
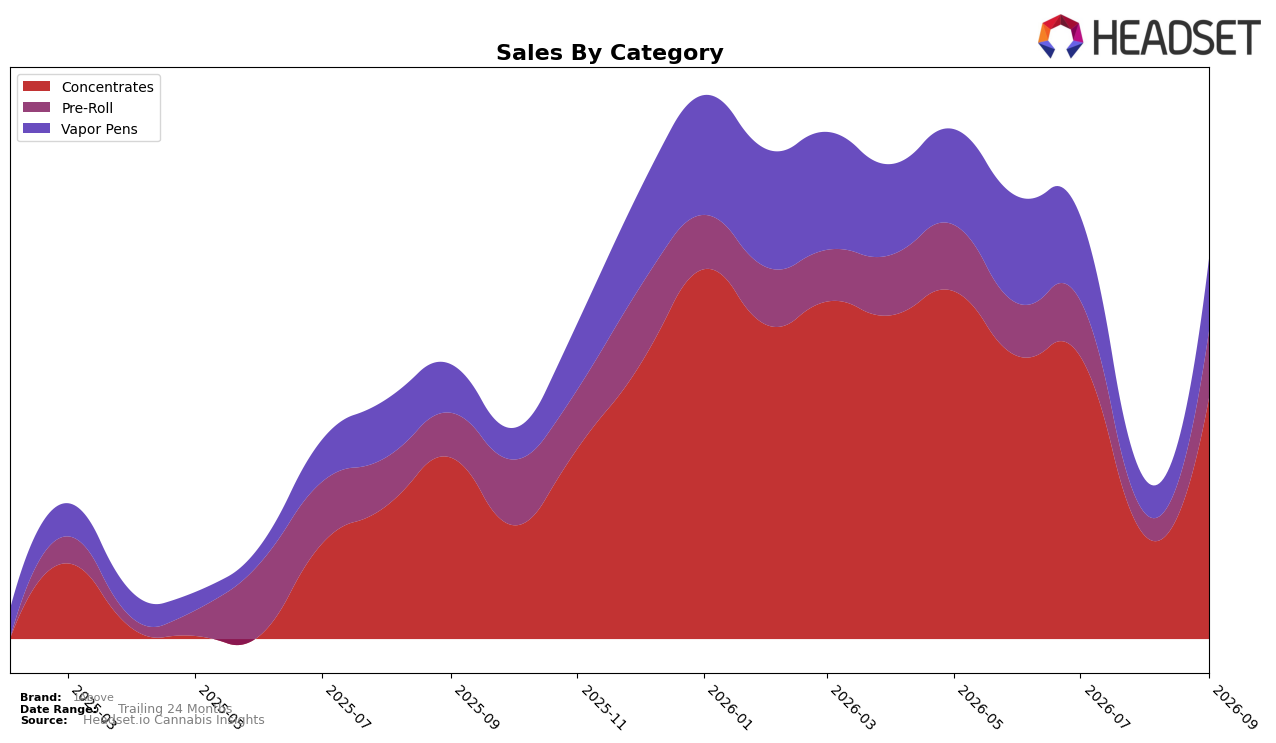
In September 2026, 1Above’s mix skewed toward Concentrates at 63.45% share with year-over-year growth of 33.86% and month-over-month acceleration of 135.75%, while Vapor Pens held 18.97% share with 50.19% YoY and 116.46% MoM, and Pre-Roll accounted for 17.58% share with 51.20% YoY and 201.46% MoM. Average price in the month was $44.99, up 0.40% YoY, and Concentrates priced at $51.81 versus Vapor Pens at $37.22 and Pre-Roll at $35.99, pointing to a higher-priced anchor category even as lower-priced formats expanded share; the pattern implies 1Above is scaling volume across all three formats with a tilt toward premium-priced Concentrates.
The rank at 20 in Concentrates within Ontario sets a benchmark against which the 63.45% category mix weight and 135.75% MoM surge can translate into visibility gains, while Vapor Pens’ 18.97% share and 116.46% MoM suggests a secondary entry point for shoppers migrating from lower price points. With brand sales up 39.55% YoY alongside a restrained 0.40% YoY price increase, and Pre-Roll’s 201.46% MoM spike from a 17.58% base, the implication is a portfolio strategy that uses Concentrates to anchor premium perception while Pre-Roll and Vapor Pens expand reach, positioning 1Above to convert rank momentum in Concentrates into broader basket penetration.
Competitive Landscape
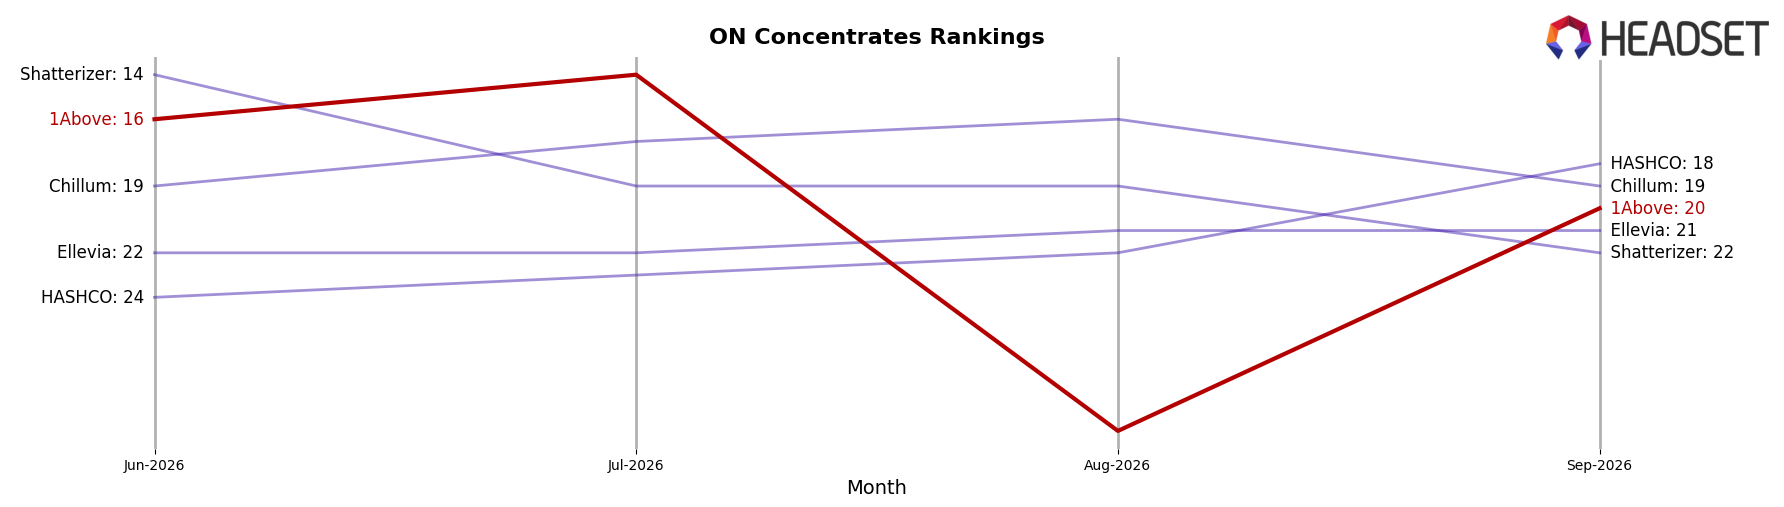
1Above ranks #20 in ON Concentrates in September 2026, improving 6 places year over year from #26 but slipping 4 positions since June 2026 when it was #16; this sits well below its January 2026 peak of #10 while category leaders shifted, as Pura Vida advanced from #4 to #2 with a 37.2% YoY sales increase and BoxHot moved from #9 to #5 on 52.3% YoY growth, whereas Nugz (Canada) slid from #2 to #3 with a 30.8% YoY decline; the mix of upward mobility among mid-tier rivals and 1Above’s mid-year drop implies a recovery from 2025 but eroding momentum through summer 2026, pointing to share pressure unless rank stabilization reverses into sustained quarterly gains.
Notable Products
Zoap 73u Live Rosin (1g) posted the standout move with a 1,740.7% month-over-month jump to rank 5, while Juice Bar Rosin Disposable (2g) slipped 26.4% to rank 6, indicating volatility at the value end of Vapor Pens. 73u Live Rosin (1g) grew 104.9% to hold rank 1 and Hybrid Juice Bar Rosin Disposable (0.5g) surged 163.9% into rank 2, while Hybrid Hash Hole Infused Pre-Roll (2g) accelerated 300.9% to rank 4, signaling that top slots are being won on rapid velocity gains rather than gradual share capture. With two Concentrates in the top five and three Pre-Rolls in the top seven, the mix concentrates demand in solventless and infused formats, implying 1Above is skewing assortment and activation toward premium extraction-led experiences over larger-format disposables.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

