

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
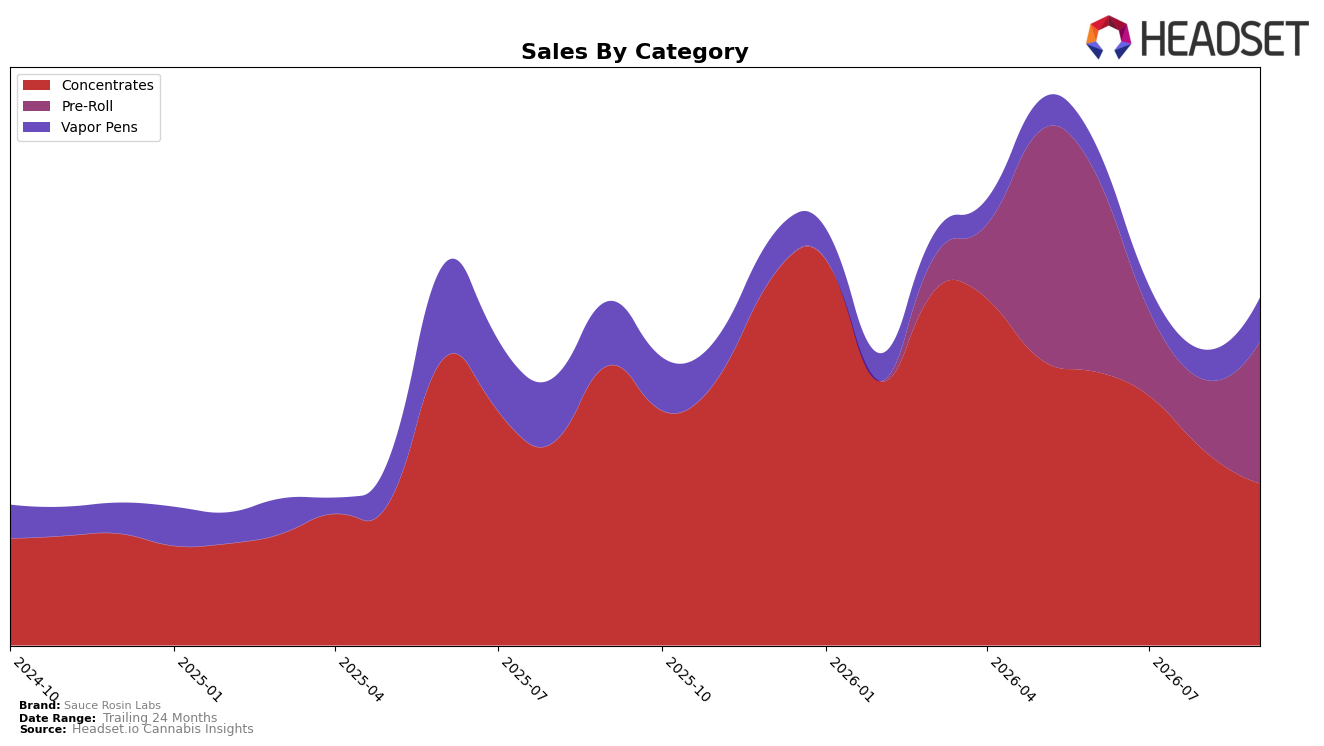
In September 2026, Sauce Rosin Labs shifted from a Concentrates-centric profile toward a more balanced mix: Concentrates fell to 46.6% share with a year-over-year decline of 42.1% and a month-over-month drop of 16.7%, while Pre-Roll surged to 40.8% share on a 99.1% month-over-month increase; Vapor Pens reached 12.6% share with a 47.5% month-over-month rise despite a 31.6% year-over-year decline. Average price fell 24.4% year over year to $44.29, indicating a pivot toward lower-priced formats as the brand’s Concentrates rank in Ontario sat at 23, implying category headwinds; the pattern suggests Sauce Rosin Labs is reallocating volume into faster-moving, lower-price segments to stabilize overall sales mix amid weakening legacy strength.
The mix shift implies a repositioning from a premium, Concentrates-led identity toward broader accessibility and trial via Pre-Rolls and Vapor Pens: Pre-Roll’s 99.1% month-over-month growth paired with Vapor Pens’ 47.5% month-over-month lift contrasts with Concentrates’ 16.7% month-over-month decline and 42.1% year-over-year contraction, pointing to a strategy that trades depth in one category for reach across two. With overall sales up 108.2% year over year against a 24.4% price reduction and a 23rd rank in Ontario Concentrates, the brand is likely prioritizing penetration and basket entry over category leadership, implying near-term gains in volume and discoverability at the expense of high-margin specialization.
Competitive Landscape
Sauce Rosin Labs sits at rank #23 in ON Concentrates for September 2026, down 5 positions year over year from #18, and 8 spots below its June 2026 rank of #15; this follows a decline from its peak position of #9 reached in April 2026 and a 14-place gap to the current top tier. In contrast, Vortex Cannabis Inc. held #1 both this year and last despite a -13.0% YoY sales change, while BoxHot advanced from #9 to #5 alongside a 52.3% YoY sales increase, indicating share is concentrating among climbers even as category leaders contract. The pattern implies Sauce Rosin Labs’ rank trajectory is drifting from peak exposure toward the mid-pack, as competitors with upward momentum compress the ladder above #20 and extend the recovery distance from April 2026’s top-10 position.

Notable Products
Slim-Bitz Rosin Infused Pre-Roll 3-Pack (1.5g) posted the standout move in September 2026 with +120.8% MoM to rank 1, while Sauce 73-159 Hash Hole Infused Pre-Roll (2g) surged even faster at +136.5% MoM to rank 5; together these shifts pushed Pre-Rolls to two of the top five ranks and signaled a pivot toward infused format velocity. In contrast, Holy Grail Live Rosin (1g) fell -39.3% MoM at rank 6 and Signature - Farmer's Pride Edition Live Rosin (1g) declined -36.1% MoM at rank 7, even as Seasonal Sweet Exotics Pack Live Rosin (1g) rose +36.6% to rank 2; with four of the top ten in Concentrates, the category remains broad but is fragmenting between seasonal lifts and core-line pullbacks. Hybrid Solventless Live Rosin Cartridge (0.5g) climbed +41.5% MoM to rank 3 while Peach Pebblez Solventless Live Rosin Cartridge (2g) held rank 9 with limited traction, and the co-branded Hash Hole at rank 8 dropped -30.3% MoM despite a $5,481 take, implying portfolio momentum is concentrating in house-led infused Pre-Rolls while legacy live rosin jars cede share.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

