

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
2727 Marijuana is stocked at 128 licensed dispensaries across Washington, with the deepest coverage in Tacoma, Seattle, Everett, Spokane, and Anacortes. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
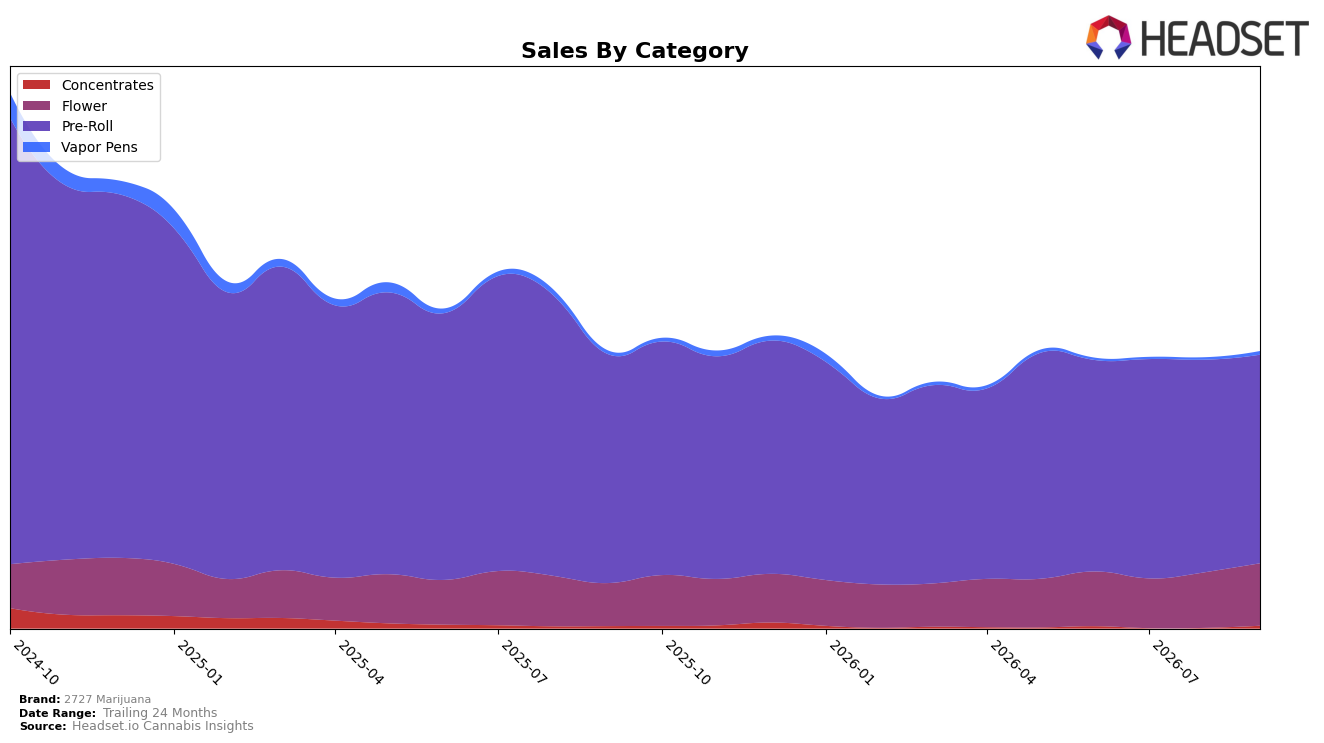
In September 2026, 2727 Marijuana concentrated 73.59% of sales in Pre-Roll, where sales declined 8.75% year over year and 1.88% month over month, while the brand held rank 9 in Washington Pre-Roll. Offsetting that contraction, Flower expanded to 22.57% share with 42.85% year-over-year growth and an 11.89% month-over-month lift, while Vapor Pens, at 2.06% share, inched down 0.92% year over year but jumped 26.35% month over month. Concentrates remained small at 1.78% share yet surged 7.72% year over year and 72.45% month over month, and the brand’s average price rose 7.39% year over year to $11.61. The mix points to a portfolio tilting away from a contracting Pre-Roll core toward faster-moving Flower and nascent rebounds in Vapor Pens and Concentrates, implying reliance on rank 9 in Pre-Roll is giving way to a more diversified volume base.
The pattern implies the brand’s positioning is shifting from single-category scale to multi-category relevance: a 73.59% Pre-Roll dependency alongside a 1.88% month-over-month decline contrasts with Flower’s 11.89% month-over-month gain and 42.85% year-over-year expansion, indicating incremental growth is more likely to come from Flower. With Vapor Pens up 26.35% month over month and Concentrates up 72.45% month over month off small bases, the brand’s 7.39% year-over-year price increase suggests room to trade consumers across tiers rather than leaning solely on volume in rank 9 Pre-Roll. Net, September 2026 mix shifts imply the path to stabilizing the brand’s 18.00% year-over-year sales decline runs through continued Flower scaling and selective investment in the high-velocity but low-share formats to dilute exposure to Pre-Roll softness.
Competitive Landscape
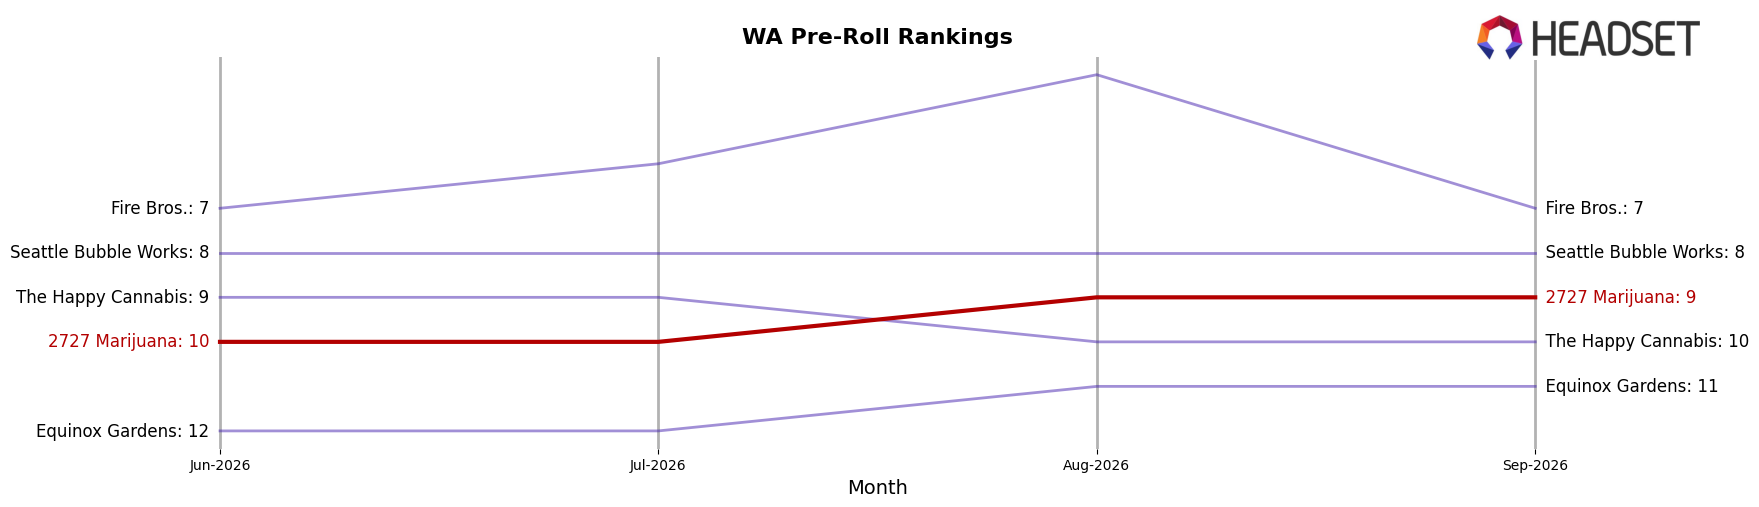
Ranked #9 in September 2026, 2727 Marijuana fell 3 positions year over year from #6 while edging up 1 place from #10 since June 2026, and that slippage contrasts with Ooowee holding #1 with a 57.7% YoY sales lift and Lifted Cannabis Co improving from #5 to #4 as Stingers moved the other direction from #4 to #5; compared with a historical peak of #3 in April 2025, the current #9 position and a 3-rank YoY decline imply share is concentrating among top-tier rivals while 2727 Marijuana’s recent quarter-on-quarter uptick signals stabilization rather than a return to prior highs.
Notable Products
Ghost OG Pre-Roll 5-Pack (5g) posted the standout move in September 2026 with a +105.4% month-over-month surge to $19,915 and jumped into rank 1, while Blue Dream Pre-Roll 5-Pack (5g) advanced modestly at +2.6% yet held rank 3. Georgia Pie Pre-Roll 5-Pack (5g) was effectively flat at +0.05% and maintained rank 2, and Glacier Falls Pre-Roll 5-Pack (5g) ticked up +0.2% while sitting at rank 9. With nine of the top ten SKUs coming from the Pre-Roll category and a single triple-digit gainer reshaping the leaderboard, the pattern implies a portfolio leaning into Pre-Roll scale where breakout winners can rapidly concentrate share.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

