

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
7 SEAZ is stocked at 20 licensed dispensaries across New York, with the deepest coverage in Brooklyn, New York, Queens, Albany, and Arlington. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
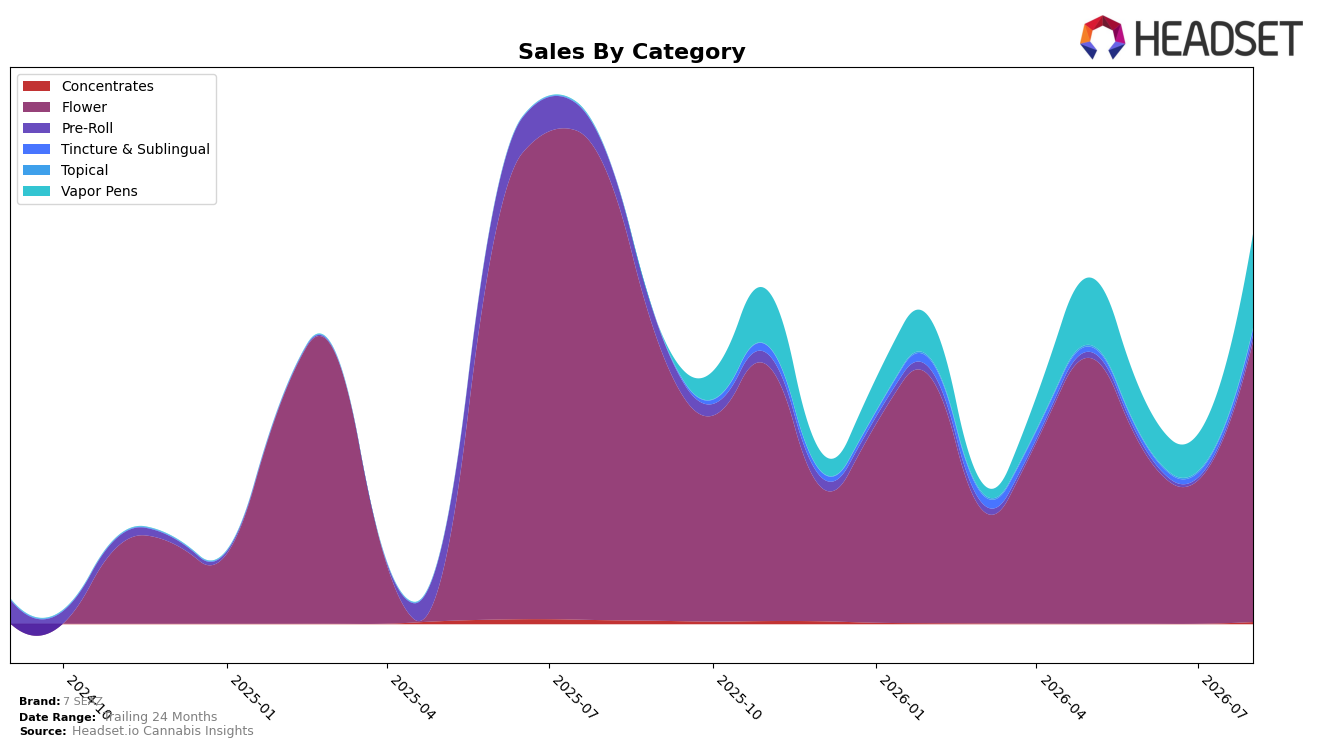
In August 2026, 7 SEAZ concentrated 72.23% of sales in Flower with a month-over-month surge of 96.75% but a year-over-year decline of 37.90%, while Vapor Pens rose to 24.16% share on 155.77% MoM growth despite having no year-over-year comp. Smaller lines were volatile: Pre-Roll held 1.48% share with 154.33% MoM growth yet fell 68.75% YoY, and Tincture & Sublingual reached 1.48% share with 27.06% MoM growth and no YoY baseline. This mix shift occurred alongside an average price drop of 23.53% YoY to $47.37 and a brand-level sales decline of 18.04% YoY, implying unit-driven recovery is offsetting price compression.
With Flower anchoring the portfolio and ranking 27th in Flower in New York, the 96.75% MoM Flower lift and 155.77% MoM Vapor Pens expansion indicate a pivot toward volume-accretive, lower-priced formats as Vapor Pens’ average price sits 55.67% below Flower and Pre-Roll averages 81.08% below Flower. The combination of a 72.23% Flower share and a 24.16% Vapor Pens share, against a brand-wide 18.04% YoY sales decline and 594.96% growth over 24 months, implies near-term reliance on two scale categories to regain rank headroom, while steep YoY contractions in Pre-Roll (−68.75%) and Concentrates (−51.72%) suggest de-emphasis of niche segments to stabilize positioning around Flower and Vapor Pens.
Competitive Landscape
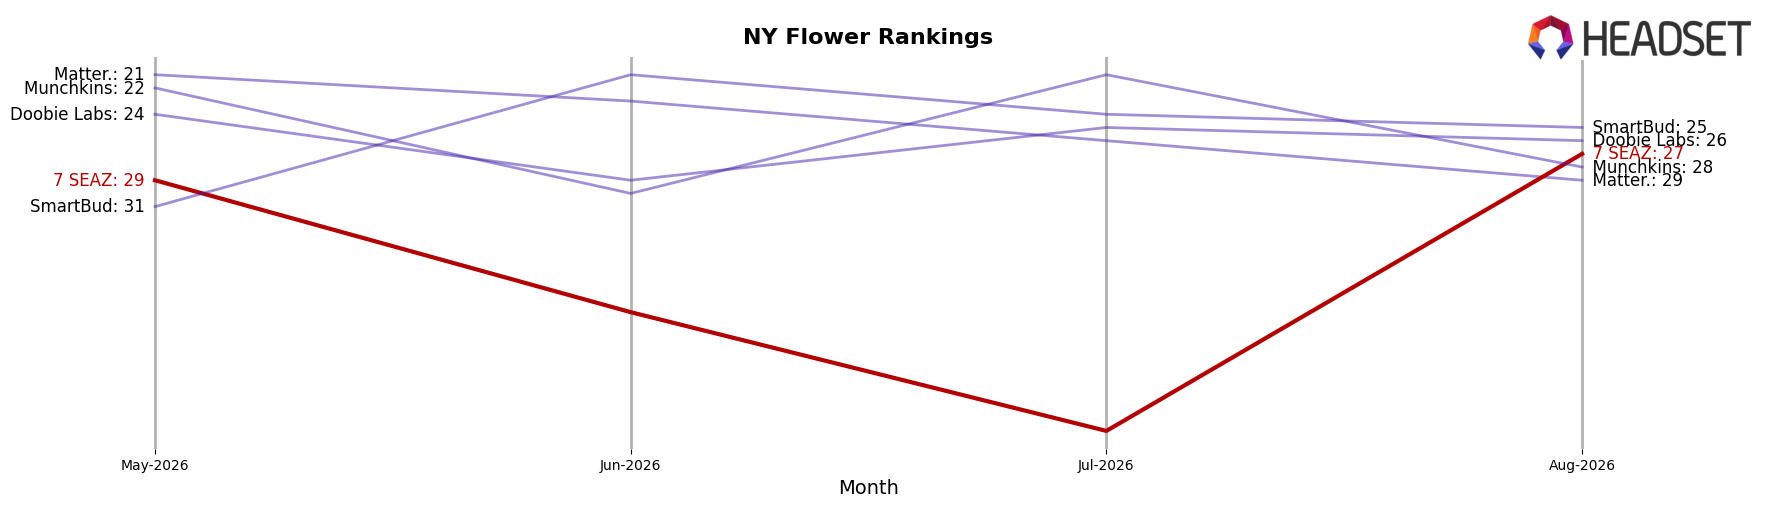
7 SEAZ is currently ranked #27 in New York Flower, down 11 positions year over year from #16, and has slipped 2 spots since May 2026 from #25 to #27; meanwhile its historical peak was #16 in August 2025, positioning today’s #27 as an 11-rank retreat from peak. In contrast, Find. advanced from #6 to #1 while growing sales by 30.3%, and Grassroots improved from #14 to #4 with an 88.4% sales increase, whereas Rolling Green Cannabis slid from #2 to #5 alongside a 36.1% sales decline; 7 SEAZ’s drift from #29 three months ago to #27 today is modest versus these sharper competitor moves, implying its rank trajectory points to a middle-tier position at risk of further erosion unless relative momentum improves.
Notable Products
Wave Rider - Miami Mimosa Distillate Disposable (1g) posted the most notable movement in August 2026 with a 202.3% month-over-month jump, propelling it to rank 4, while Strawberry Cough (7g) also surged 168.7% MoM to rank 2; this tandem lift implies activation-driven trial converting into top-tier velocity rather than a one-off spike. With four Vapor Pens SKUs in the top ten and three Flower SKUs clustered at ranks 1, 2, and 5, the category mix concentrates volume at the extremes of format preference, suggesting cross-format shoppers are trading into convenience without abandoning value Flower. Black Magic (7g) held rank 1 as a stable anchor while Wave Rider - Papaya Spritzer Distillate Disposable (1g) and Wave Rider - Bikini Diesel Distillate Disposable (1g) advanced 90.9% and 79.8% MoM into ranks 6 and 7, respectively, consolidating share inside mid-pack ranks; this pattern implies portfolio-led laddering where flagship Flower fuels discovery into branded disposables at rising price-per-puff. Average ticket is likely drifting upward as Vapor Pens rise within the top ten and total revenue concentrates in fewer SKUs, with Black Magic (7g) alone contributing $64,010, indicating a deliberate tilt toward higher-velocity hero items over long-tail breadth.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

