

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Achieve is stocked at 12 licensed dispensaries across Arizona, with the deepest coverage in Phoenix, Flagstaff, Apache Junction, Cave Creek, and Coolidge. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
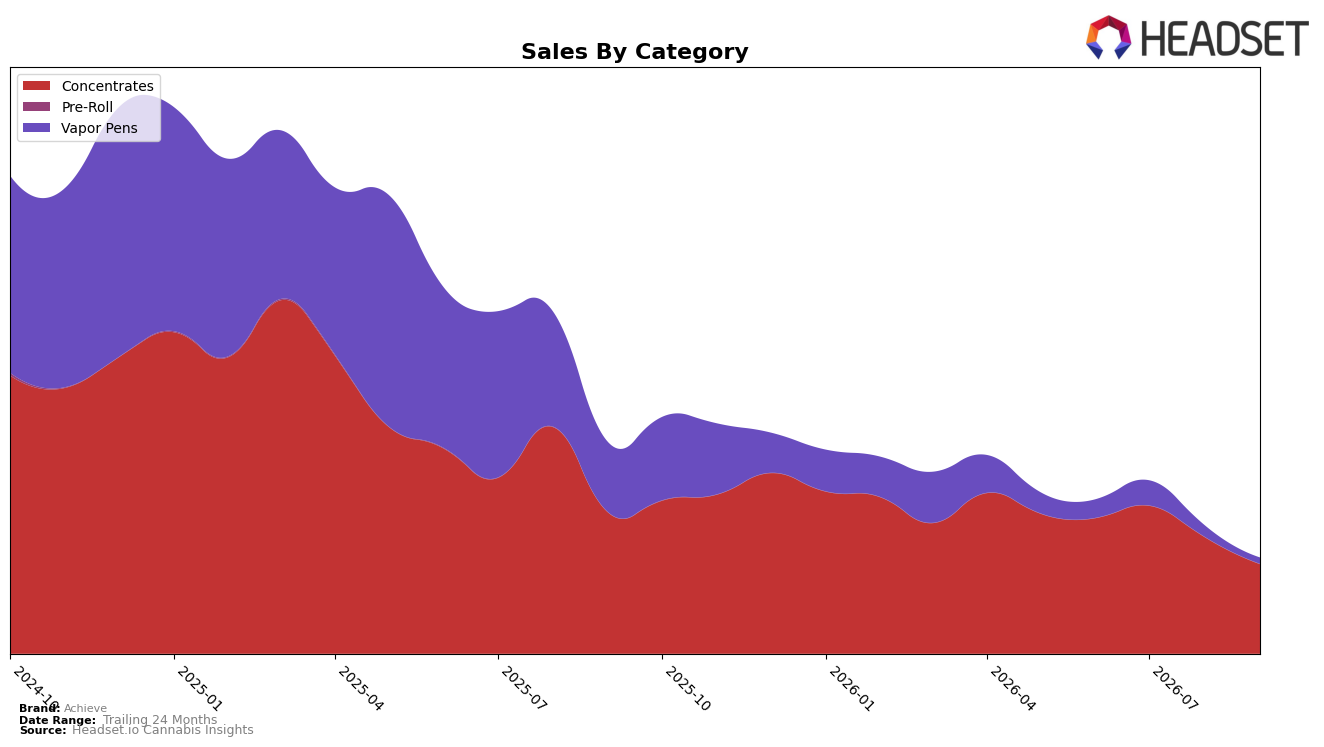
Achieve’s category mix in September 2026 was concentrated in Concentrates at 93.64% share, with Vapor Pens at 6.36% share, while total brand sales were down 54.71% year over year and the average price fell 8.02%. Within categories, Concentrates declined 36.59% year over year and 23.25% month over month, whereas Vapor Pens contracted 91.30% year over year and 46.47% month over month; the average ticket sat at $21.41 against category-level prices of $20.92 in Concentrates and $32.74 in Vapor Pens. With a rank of 24 in Concentrates in Arizona, the mix and double-digit declines indicate a narrow portfolio that is shedding volume faster in peripheral formats, implying intensified reliance on a single category amid broad pricing pressure.
The shift toward a 93.64% Concentrates dependency alongside a 46.47% month-over-month contraction in Vapor Pens implies Achieve is concentrating shelf presence where it competes but with limited insulation from category cyclicality, given the 23.25% month-over-month drop in the lead segment and the 36.59% year-over-year contraction. The price posture—an 8.02% year-over-year decrease overall while holding a slight premium over the $20.92 Concentrates average—suggests a repositioning toward value without a full price reset, and the rank of 24 in Arizona Concentrates combined with a 54.71% brand-level year-over-year decline implies mid-pack visibility that is not converting to stability, pointing to a need to either deepen differentiation in Concentrates or reallocate toward formats less volatile than Vapor Pens’ 91.30% year-over-year drop.
Competitive Landscape
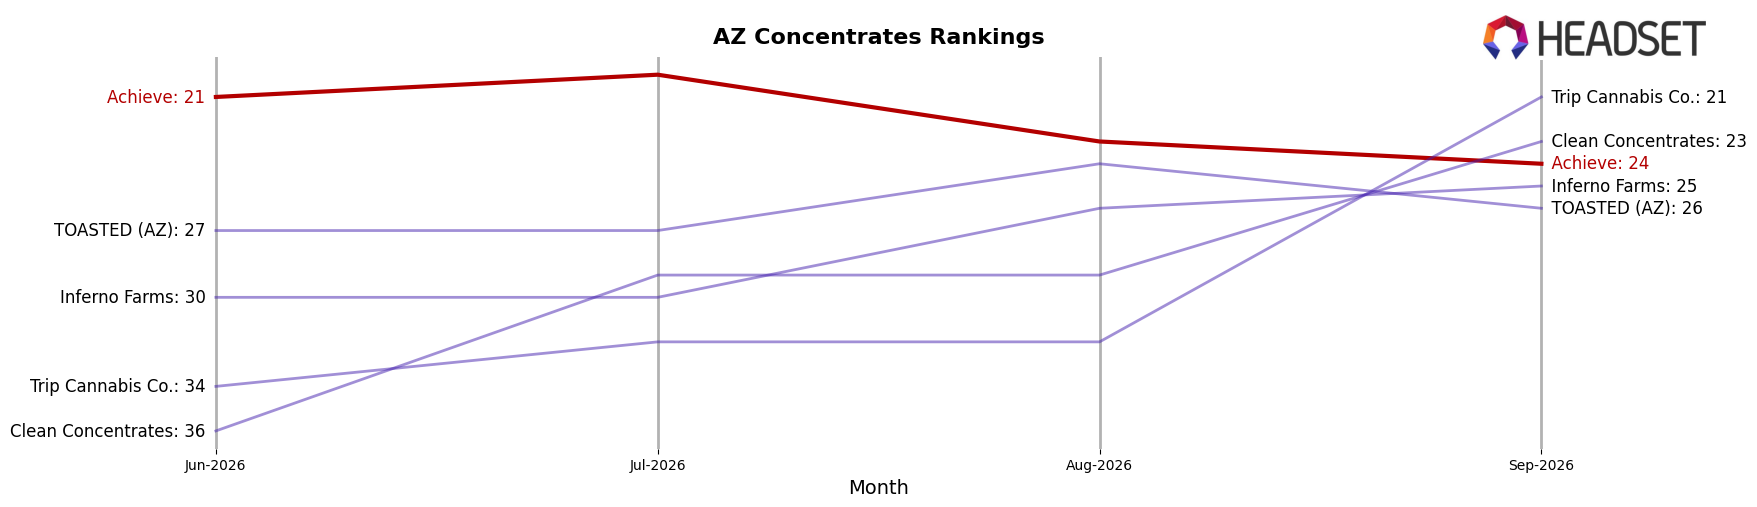
Achieve is ranked #24 in Arizona Concentrates in September 2026, down 6 places year over year from #18, and 3 places lower than June 2026 when it was #21; by contrast, Mohave Cannabis Co. held #1 both year over year and currently while growing sales 16.8%, and Grow Sciences advanced from #7 to #3 alongside a 69.4% YoY sales increase. The gap from Achieve’s peak at #10 in March 2025 to #24 now, alongside Glorious Extracts jumping from #29 to #5 with 495.5% YoY sales growth, indicates Achieve is ceding rank share to faster-advancing rivals and will need mix or distribution shifts to halt further slide.
Notable Products
White Rontz Hash (1g) posted the steepest decline in September 2026 at -76.0% MoM and sat at rank 4, while Blue NDZ RSO Syringe (1g) fell -78.3% MoM to rank 8, together signaling a sharp reset in two different sublines. Against those drops, Super LCG Hash (1g) surged 216.7% MoM into rank 6 and Slappy Gilmore Hash (1g) remained at rank 1 despite a -28.7% MoM contraction and $8,865 in sales, indicating volatility rather than uniform softness. With all ten top SKUs in Concentrates and multiple RSOs sliding while select hash SKUs rebound, the mix implies Achieve is tilting toward hash-led momentum while RSO requires pruning or targeted support.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

