

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
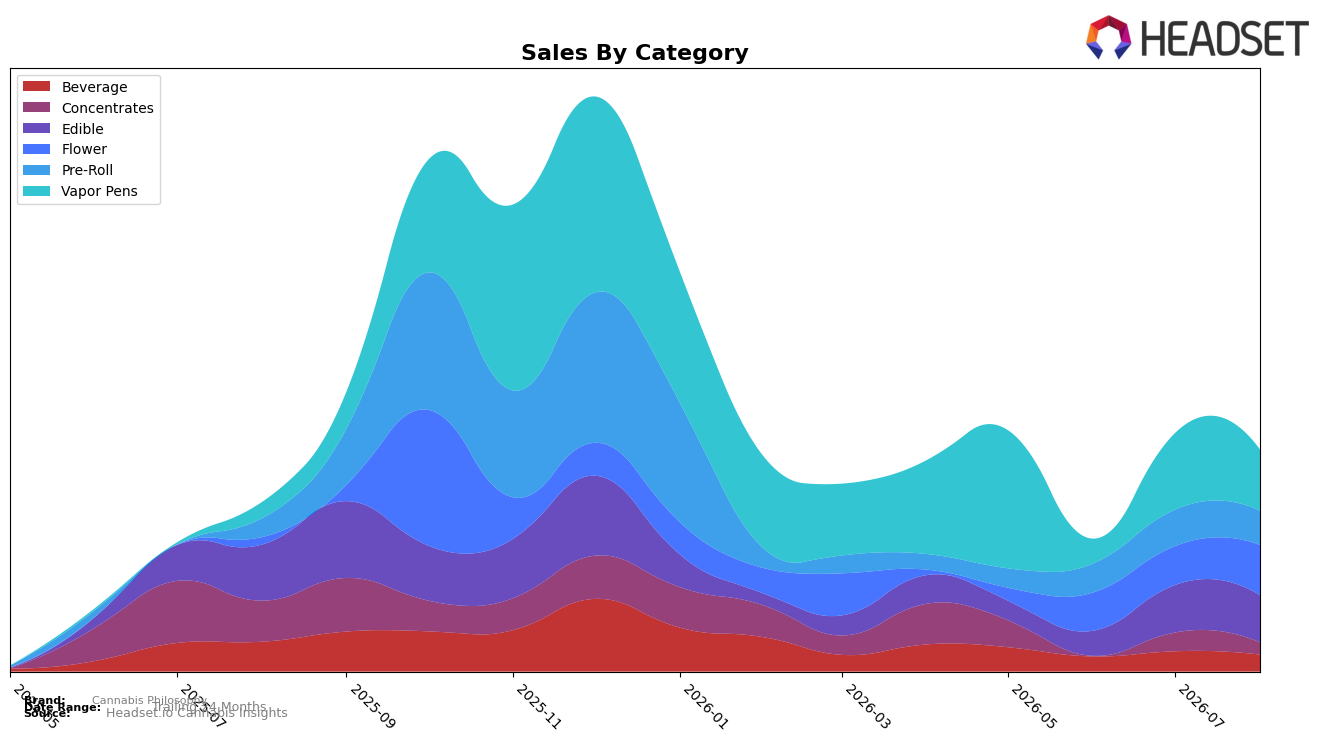
In August 2026, Cannabis Philosophy’s mix tilted toward Vapor Pens at 27.61% share with year-over-year growth of 280.21% but a month-over-month decline of 20.27%, while Flower rose to 22.60% share with year-over-year growth of 585.44% and month-over-month growth of 28.98%. Edible held 21.27% share with year-over-year decline of 15.75% and month-over-month decline of 0.63%, and Pre-Roll accounted for 15.44% share with year-over-year growth of 84.21% but a 5.94% month-over-month drop. Beverage fell to 7.63% share with a 43.25% year-over-year decline and a 16.33% month-over-month decline, while Concentrates slipped to 5.45% share with a 70.52% year-over-year decline and a 35.19% month-over-month decline. The pattern implies a pivot from Concentrates and Beverage toward inhalables and Flower, with short-term volatility in Vapor Pens offset by sustained expansion in Flower and Pre-Roll.
The category shift suggests repositioning toward accessible inhalable formats and mainstream Flower at lower effective price points, supported by a 23.59% year-over-year decrease in average price and overall brand sales growth of 31.36% year-over-year. With Vapor Pens leading internal share at 27.61% but showing month-over-month pressure of 20.27%, the brand’s stability increasingly relies on Flower’s 28.98% month-over-month surge and Pre-Roll’s 84.21% year-over-year lift. Given a Vapor Pens category rank of 83 in New Jersey, the mix implies prioritizing Flower and Pre-Roll to anchor velocity while using selective Vapor Pen offerings to maintain presence, turning August 2026 dynamics into a path to rebalance share toward categories with improving momentum.
Competitive Landscape
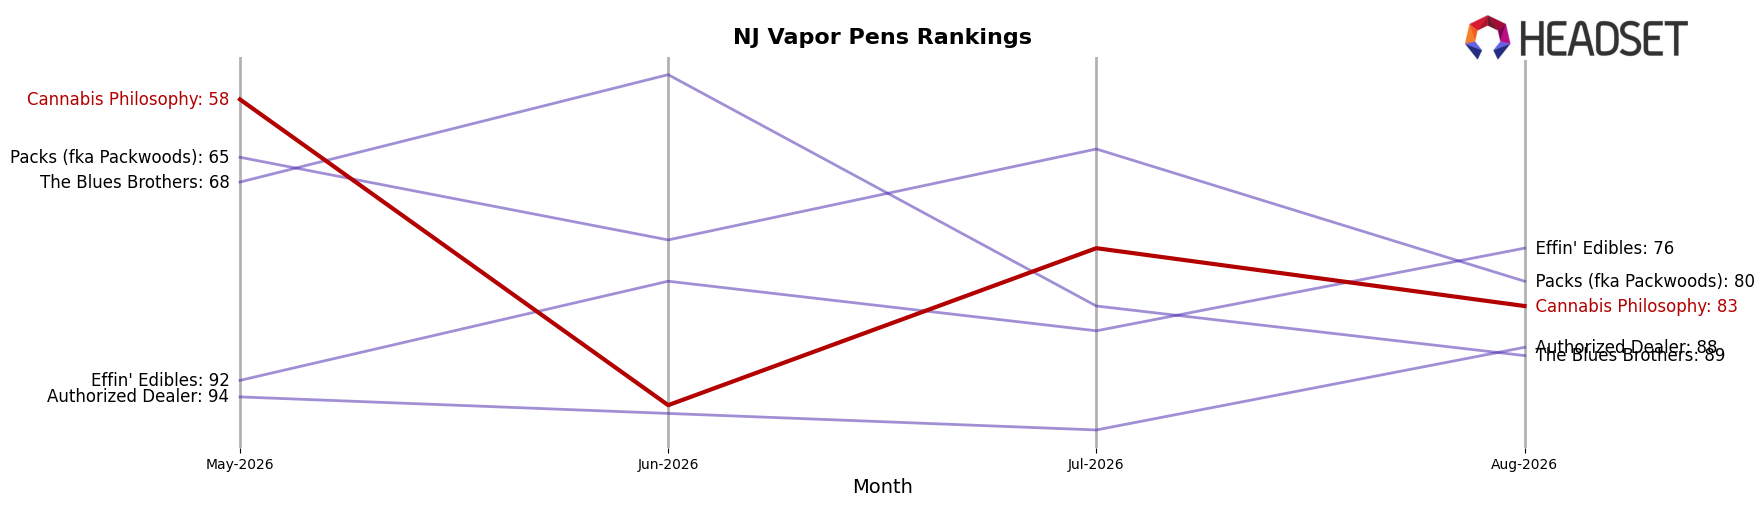
Cannabis Philosophy sits at rank 83 in August 2026, down 4 positions year over year from rank 79, and down 25 positions from rank 58 in May 2026; against the wider field, its peak rank of 41 in November 2025 marks a 42-position slide to the present. While Select holds rank 1 with a -21.2% YoY sales change and RYTHM moved up from rank 7 to rank 5 on 14.0% YoY sales growth, Cannabis Philosophy’s backward shift contrasts with Fernway maintaining rank 2 alongside a 4.9% YoY sales increase. The pattern implies Cannabis Philosophy has transitioned from a mid-tier contender to a lower-tier participant, signaling that without a share recovery strategy its position will likely continue to cede ground to competitors advancing in rank momentum and year-over-year velocity.
Notable Products
Lime OG Infused Whole Flower (3.5g) set the pace in August 2026 with a 62% month-over-month jump to rank 1, while LemonCello Bellagio Gelato Dual Chamber Disposable (2g) slid 40% to rank 9. Edibles were bifurcated: Berry Punch Ice Pops (10mg) dropped 59% to rank 2 and Cherry Ice Pops (10mg) fell 62% to rank 10, yet four of the top ten are Ice Pops SKUs, indicating concentration despite volatility. The Don Infused Pre-Roll 5-Pack (2.5g) declined 17% to rank 8 and Lemonade Drink Mix 10-Pack (100mg) contracted 21% to rank 5, creating a gap where Flower ascends as ingestibles retrench. The mix implies Cannabis Philosophy is gravitating toward inhalable-led volume with Flower leading and Edibles serving as seasonal, high-churn traffic drivers rather than consistent anchors.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

