
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Cascade Valley Cannabis is stocked at 70 licensed dispensaries across Oregon, with the deepest coverage in Portland, Bend, Eugene, Medford, and Corvallis. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
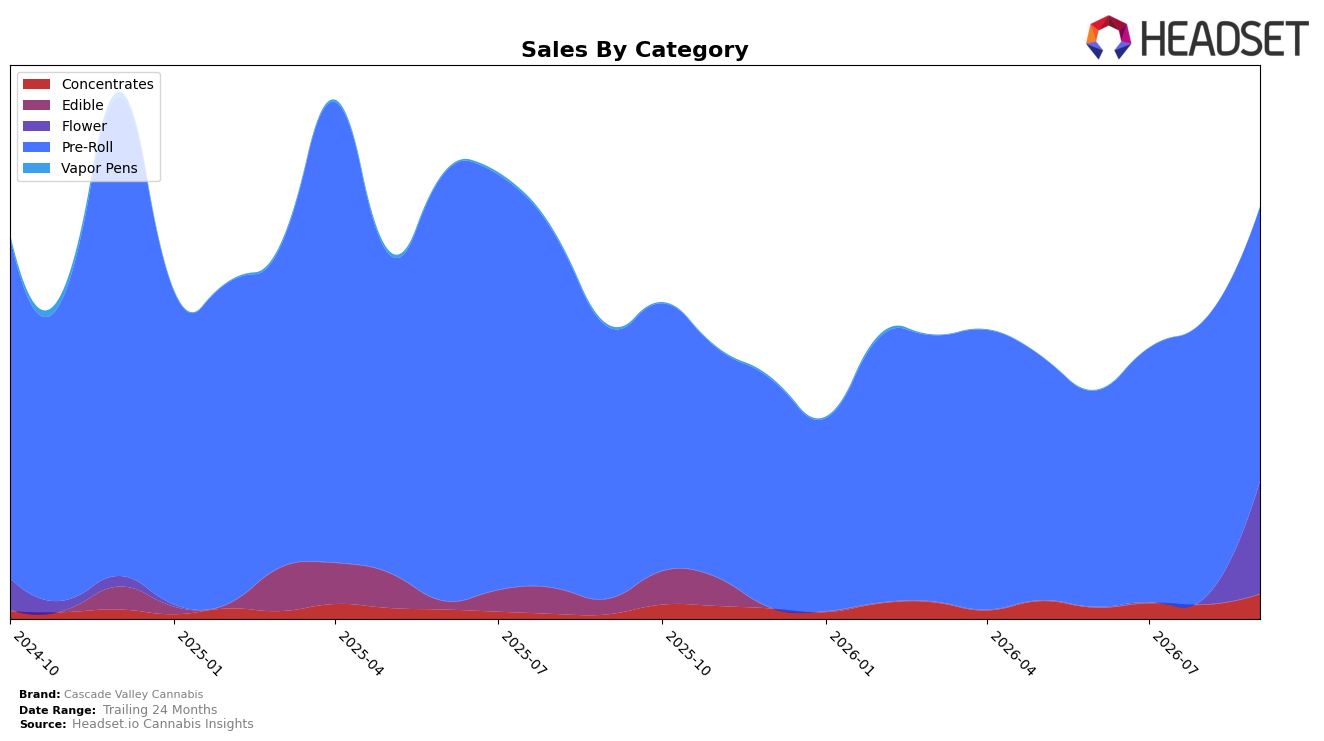
Cascade Valley Cannabis concentrated 66.73% of September 2026 sales in Pre-Roll, down 1.36% month over month but up 1.13% year over year, while Flower jumped to 27.29% share on a 1,739.18% month-over-month surge with no reported year-over-year rate. Concentrates reached 5.98% share with 77.07% month-over-month growth and a 449.33% year-over-year increase, and the brand’s overall average price declined 36.81% year over year to $5.89, coinciding with total brand sales up 40.47% year over year. In Oregon Pre-Rolls, the brand sat at rank 22, indicating mid-pack presence even as the category still anchors two-thirds of mix; the pattern implies volume expansion is being driven by aggressive price moves and rapid expansion in Flower and Concentrates rather than gains in Pre-Roll rank.
The mix shift toward Flower and faster-growing Concentrates, alongside a 36.81% drop in average price and a 40.47% year-over-year brand sales increase, implies a pivot toward value-led recruitment and basket-filling rather than premium positioning. With Pre-Roll share easing 1.36% month over month at rank 22 and Concentrates up 77.07% month over month and 449.33% year over year, the brand’s near-term positioning skews toward capturing price-sensitive demand and cross-category trial; sustaining this will likely require defending Pre-Roll velocity while converting September 2026’s 1,739.18% Flower spike into repeat, or risk over-reliance on promotional elasticity.
Competitive Landscape
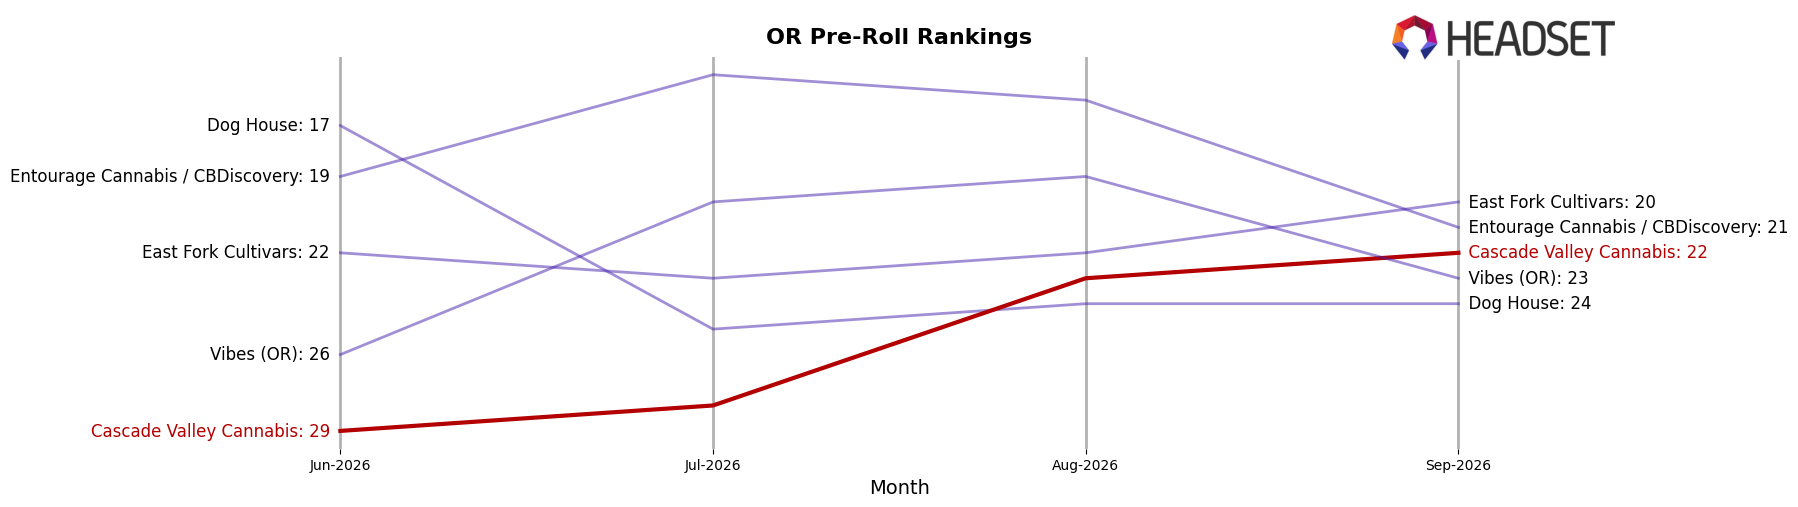
Cascade Valley Cannabis sits at rank #22 in OR Pre-Roll in September 2026, unchanged YoY from #22, but up 7 positions from #29 in June 2026, while still trailing its peak of #9 from December 2024; in contrast, STiCKS holds #1 with a 91.7% YoY sales increase and Kaprikorn climbed from #6 to #2 with 160.0% YoY growth, signaling that Cascade Valley Cannabis’s flat YoY rank alongside a recent 7-rank recovery implies share stabilization rather than category leadership momentum.
Notable Products
Blueberry Pre-Roll (1g) posted the largest month-over-month gain at +96.5% to reach rank 9, while Concrete Jungle Pre-Roll (1g) slid -22.0% to rank 8, signaling a rapid shift within the Pre-Roll lineup. Yoga Pants Pre-Roll (1g) also surged +51.8% at rank 10, and six of the top ten SKUs are Pre-Rolls, indicating category concentration even as Sour Tangie (Bulk) and Punch Breath (Bulk) hold ranks 1 and 2. With Pre-Rolls clustering at ranks 3 through 10 and two SKUs growing over +50%, the mix points to a pivot toward value-driven, fast-turn Pre-Roll velocity while Flower anchors the top with a single high-dollar leader at $29,215.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

