

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
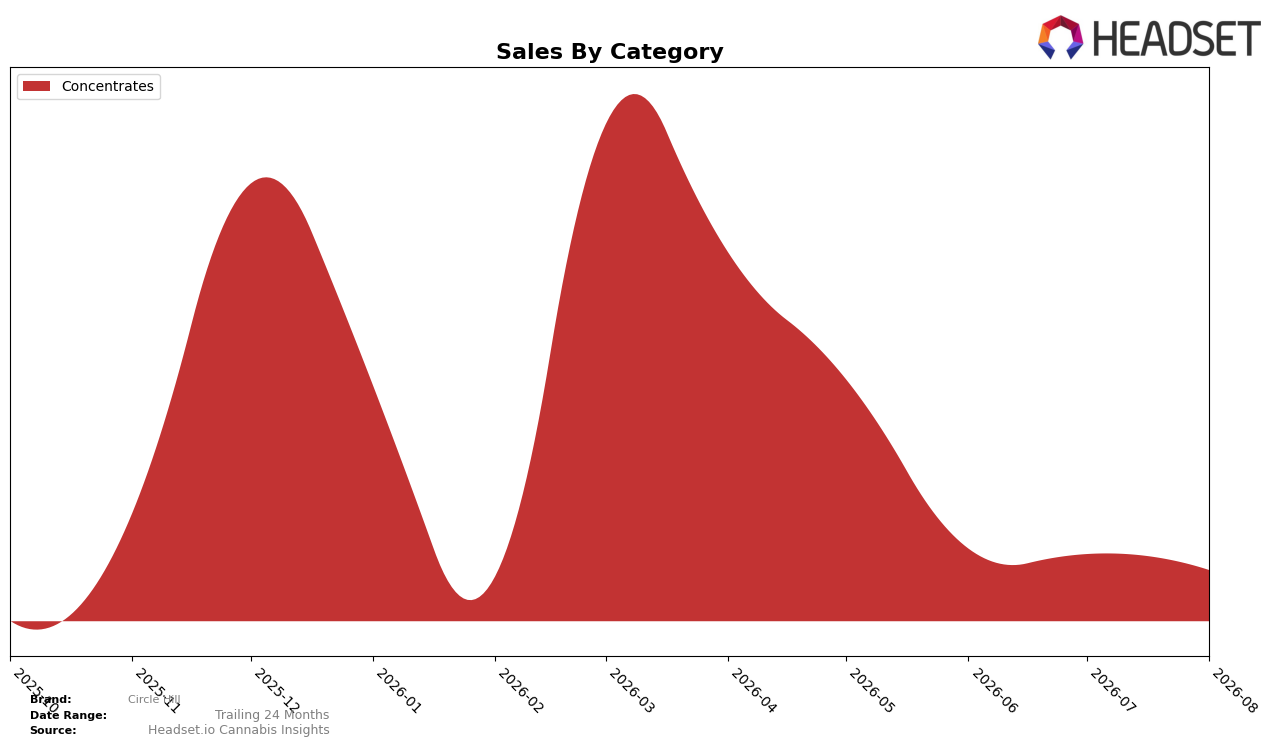
In August 2026, Circle Hill concentrated entirely in Concentrates with a 100.0% category share, indicating no diversification versus July 2026 or August 2025, while month-over-month sales in Concentrates fell 13.54% alongside an average price of $73.84. Within the New York context for Concentrates, the brand held rank 39, which places it behind at least 38 peers and implies pressure on visibility despite the single-category focus; the pattern suggests that a pure-play mix paired with a double‑digit MoM decline limits cushion against seasonal volatility and price-led repositioning.
The fixed 100.0% mix in Concentrates and the 13.54% MoM decline in August 2026 point to a positioning anchored in a narrow assortment where volume sensitivity likely outweighs price leverage at an average ticket of $73.84, while rank 39 in New York implies late‑tier shelf access rather than premium leadership. The implication is that Circle Hill’s current stance trades operational simplicity for exposure to category‑specific downswings, and that moving even 10–20% of sales into an adjacent format could buffer month-to-month swings and support an ascent of several rank positions in Concentrates without requiring a broad overhaul.
Competitive Landscape
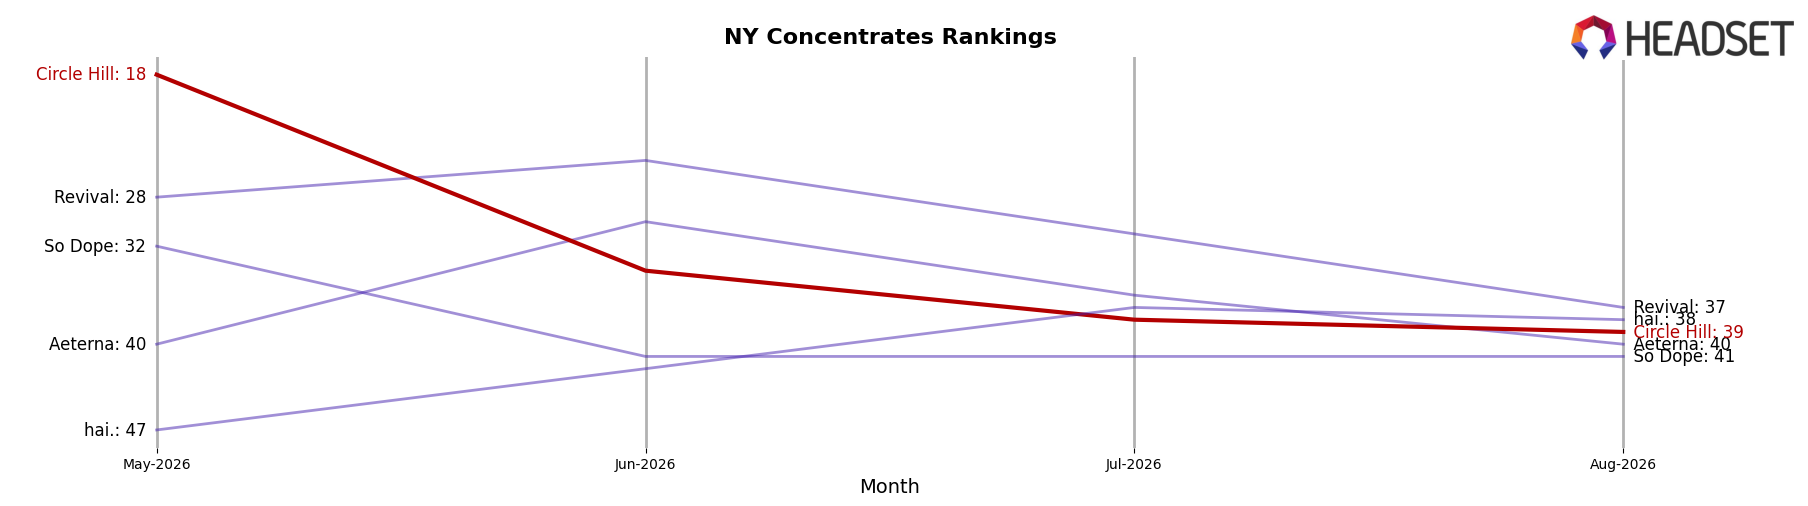
Circle Hill sits at rank #39 in August 2026, down 21 places from #18 in May 2026, and 29 spots below its peak of #10 in March 2026; meanwhile category leaders tightened their positions, with Mfny (Marijuana Farms New York) holding #1 year over year and UMAMII leaping from #33 to #3 alongside a 3,294.5% YoY sales change. The current #39 rank places Circle Hill 37 places behind Jetpacks at #2 and 35 behind RYTHM at #4, while Nyce advanced from #8 to #5 with an 81.5% YoY increase; the directional gap versus multiple climbers implies Circle Hill’s rank trajectory is signaling lost shelf momentum that will require either mix resets or price-pack changes to arrest further share erosion.
Notable Products
Strawguava Live Rosin (2g) posted the standout move in August 2026 with a +480% month-over-month surge, jumping to rank 5 while Strawberry Guava Cold Cured Live Rosin (1g) fell -50% to rank 4. Dulce De Uva Cold Cured Live Rosin (2g) declined -16% at rank 3, and Dulce De Uva Live Rosin (1g) slid -10% at rank 2, indicating share rotation toward larger pack sizes even as top-three ranks stayed concentrated in legacy SKUs. With all top-10 positions in Concentrates and multiple Strawguava and Dulce De Uva variants present, the portfolio is clustering in a few strain families, which implies a deliberate push toward 2g formats and fewer, deeper winners rather than broad SKU proliferation.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

