

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Cizi is stocked at 230 licensed dispensaries across California, with the deepest coverage in Los Angeles, San Diego, Long Beach, San Bernardino, and San Jose. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
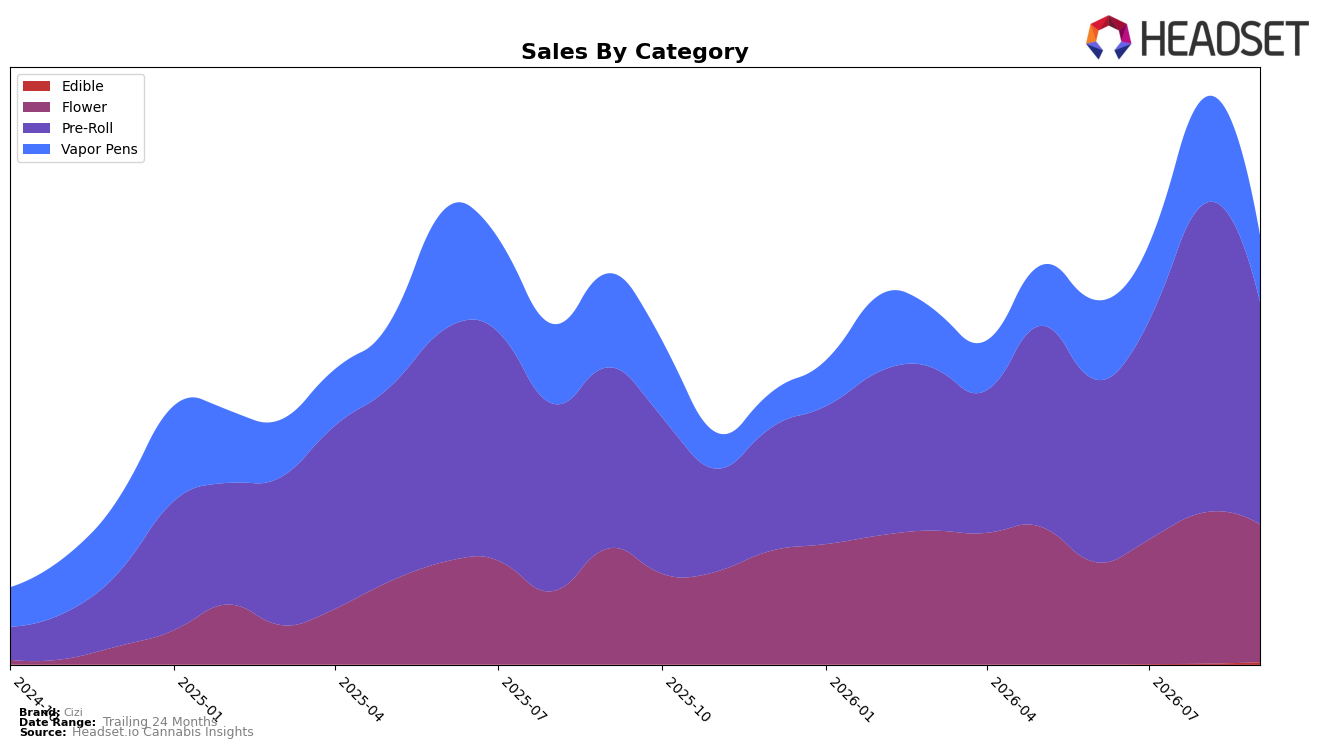
In September 2026, Cizi concentrated over half of sales in Pre-Roll at 51.88% share with year-over-year growth of 23.01% but a month-over-month drop of 27.91%, while Flower held 32.07% share with 18.77% YoY growth and an 8.93% MoM decline. Vapor Pens contracted to 15.51% share with a 29.09% YoY decline and a 37.10% MoM decline, as Edible remained a rounding-error at 0.54% share despite a 160.47% MoM spike. The brand’s average price rose 7.82% YoY to $7.16, and Pre-Roll’s category rank in California sat at 26, indicating category reliance even as Pre-Roll volumes softened month-over-month; the pattern implies a portfolio anchored to value-led Pre-Roll and Flower that is exposed to short-term volatility when those two categories retrench simultaneously.
The sharp MoM pullbacks in both Pre-Roll (-27.91%) and Vapor Pens (-37.10%) alongside Flower’s smaller MoM decline (-8.93%) imply the current mix skews toward lower-ticket, higher-churn formats where demand can whipsaw, while the 23.01% YoY gain in Pre-Roll and 18.77% YoY in Flower suggest sustained shopper adoption that offsets Vapor Pens’ 29.09% YoY erosion. With Pre-Roll at rank 26 in California and brand-wide sales up 9.83% YoY, the mix implies Cizi’s positioning is mid-pack in a volume-driven segment where modest price increases can lift revenue but won’t counteract category-specific MoM swings; strategically, this points to doubling down on sticky Flower cohorts while using Edible’s 160.47% MoM momentum as a low-risk expansion wedge to reduce dependence on Pre-Roll cyclicality.
Competitive Landscape
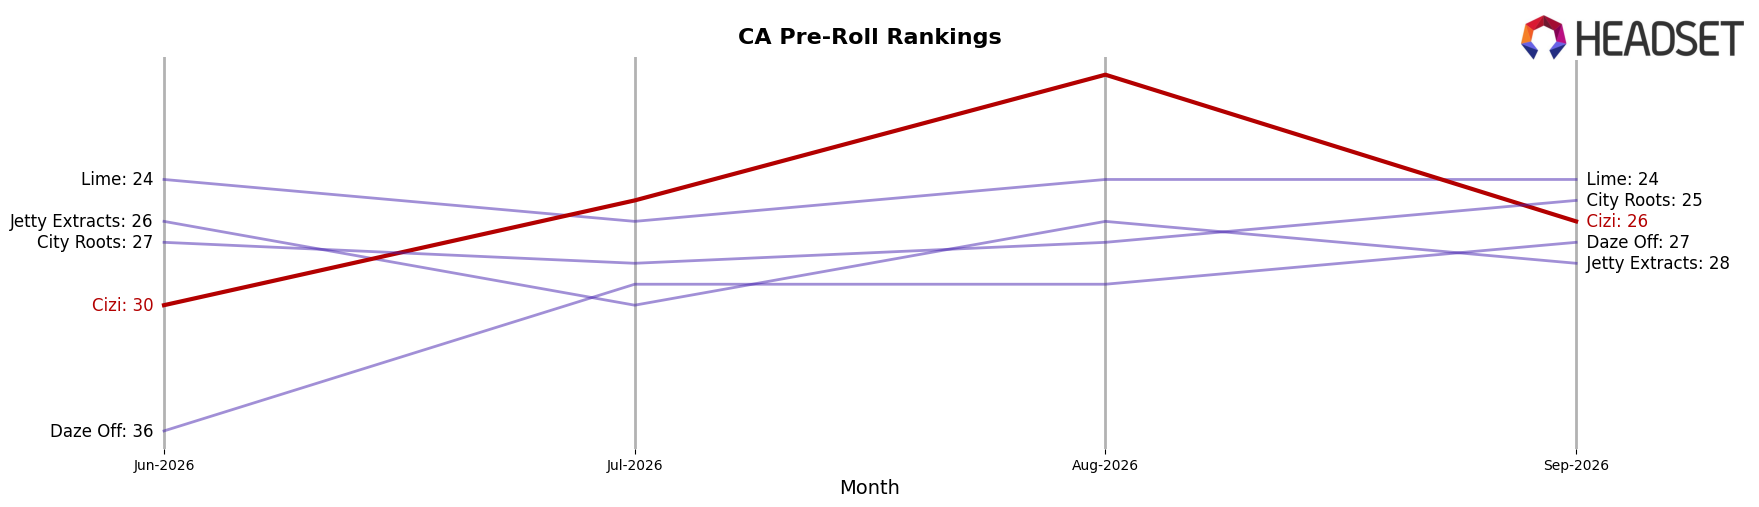
Cizi sits at rank #26 in CA Pre-Roll for September 2026 with no year-over-year rank change from #26, yet it improved 4 positions versus June 2026 when it was #30 and briefly peaked at #19 in August 2026 before sliding 7 spots month over month; in contrast, Jeeter held #1 year over year and in September 2026 while growing sales 16.0%, and Claybourne Co. moved up from #6 to #4 alongside a 19.3% sales increase. The pattern—flat YoY rank at #26 alongside a short-lived August 2026 peak and a 4-rank gain over three months—implies Cizi is competing for mid-tier share with episodic spikes that have not converted into sustained top-20 placement.
Notable Products
MAC 1 Pre-Roll (1g) posted the steepest month-over-month decline at -47.2% while holding rank 10, and White Widow Pre-Roll (1g) fell -44.7% at rank 5, signaling strain-specific fatigue at both the middle and tail of the leaderboard. At the top, Maui Wowie Pre-Roll (1g) retained rank 1 despite a -33.0% drop, and Godfather OG Pre-Roll (1g) slid -39.3% at rank 4, indicating that share is consolidating around incumbents even as volumes retreat. Nine of the top ten are Pre-Roll SKUs, with Super Silver Haze Pre-Roll (1g) at rank 2 down -28.1% and F1 Pre-Roll (1g) at rank 3 down -18.6%, and the lone new entrant Purple Octane Pre-Roll (1g) debuted at rank 7 with $29,710 in September 2026. The pattern implies Cizi is over-indexed in Pre-Rolls and may be trading rank stability for unit velocity, suggesting a need to refresh assortments or diversify form factors to protect revenue.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

